|
시장보고서
상품코드
2116466
외래수술센터(ASC) 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Ambulatory Surgery Center - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
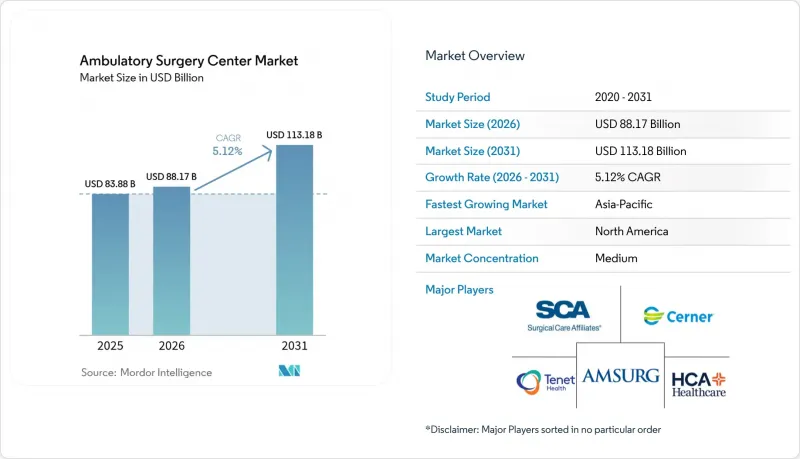
에 의하면, 2026년 외래수술센터(ASC) 시장 규모는 881억 7,000만 달러로 추정되고 있어 2025년 838억 8,000만 달러에서 확대해, 2031년에는 1,131억 8,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 5.12%가 될 것으로 전망됩니다.
본 보고서에서는 업계를 센터 유형(단일 전문센터, 다중 전문센터), 운영 형태(병원 병설형 ASC, 독립형 ASC), 소유 형태(의사 소유 등), 서비스, 전문 분야 및 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류하고 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 외래수술센터(ASC) 시장 동향 및 인사이트
CMS 승인 ASC 시술 목록의 확대가 고도화된 치료로의 전환을 가속화
2025 회계연도 병원 외래 환자 전향적 지불 시스템(OPPS)의 최종 규정에 따라, 특정 경피적 관상동맥 중재술을 포함한 20가지의 복잡한 중재 시술이 외래 수술 목록에 추가되었습니다. 영상 진단실을 업그레이드하고 다학제 팀의 자격 인증을 취득한 센터는 이미 새로운 환자 유입을 확보하고 고액의 민간 보험 계약을 체결하고 있습니다. 심혈관 질환 치료 건수는 2030년까지 연평균 성장률(CAGR) 9.65%를 유지할 것으로 예상되며, 선점한 업체에게는 보험사 구성 측면에서 확고한 우위를 가져다줄 것입니다. 대규모 의료 시스템에서는 24시간 퇴원 규정을 준수하면서도 더 많은 환자 수를 확보하기 위해, 이용률이 낮은 병원의 외래 진료 부서를 전용 하이브리드형 외래수술센터(ASC)로 전환하고 있습니다.
‘필요성 증명서(CON)’ 규제 완화로 급속한 시설 확장이 가능해짐
조지아주, 플로리다주, 웨스트버지니아주의 규제 완화로 인해 신규 개발에 대한 진입 장벽이 낮아지고 있습니다. 2024년 7월부터 시행되고 있는 조지아주 HB 1339호 법안은 많은 신규 센터를 기존의 CON( 수요 증명서) 절차에서 면제하고 있으며, 애틀랜타 광역권에서만 30건 이상의 신청이 잇따르고 있습니다. 고도의 입지 선정 분석 능력을 갖춘 운영 사업자들은 경쟁사보다 앞서 인구 증가가 예상되는 지역 인근에서 임대 계약을 체결하고, 현지 의사와의 제휴를 활용하여 보험사 인가를 신속히 취득하고 있습니다. 신청 속도를 고려할 때 공급량의 급증으로 인해 중기적으로는 가동률이 하락할 가능성이 있지만, 그동안 의료 서비스가 충분하지 않았던 교외 지역의 환자 접근성은 확대될 것입니다.
수술 전후 간호사 및 마취 전문 간호사의 부족이 수술실 이용률을 제한
인증 등록 마취 간호사공급은 여전히 수요를 밑돌고 있으며, 특히 그들이 유일한 마취 제공업체가 되는 경우가 많은 지방 시장에서 그 경향이 두드러집니다. 임금 인플레이션의 진행과 번아웃이 채용난을 더욱 심각하게 만들고 있어, 수요가 있음에도 불구하고 일부 시설에서는 수술 블록 시간을 제한할 수밖에 없는 상황에 처해 있습니다. 의료기관 측은 레지던트 양성 프로그램 가속화나, 다년 고용 계약과 연계된 학비 지원 제도 도입 등으로 대응하고 있습니다. 유연한 근무 일정과 경력 발전 기회를 제공하는 기관에서는 이직률을 한 자릿수 초반으로 억제하며 가동률을 유지하고 있습니다.
부문 분석
단일 전문 분야 시설은 임상 효율이 높은 근골격계, 안과, 통증 관리 각 서비스 라인에 힘입어 2025년 매출의 61.78%를 창출했습니다. 단일 전문 분야 시설을 운영하는 사업자들은 동일 수술실의 평균 회전 시간이 14분 미만이라고 보고하고 있으며, 이는 의사들의 정착률을 높이는 중요한 요인이 되고 있습니다. 중점적인 인력 배치 모델, 장비 재사용, 그리고 통일된 임플란트 처방 목록을 통해 EBITDA 마진은 그동안 30%대 중반 수준을 유지해 왔습니다.
다학제 진료 센터는 현재 규모는 작지만, 2031년까지 연평균 8.09%의 성장률을 기록하며 단일 전문 분야 시설을 능가할 것으로 예측됩니다. 다양한 진료 사례 구성은 진료 보수의 변동을 완화하고 주간 예약 밀도를 높입니다. 대규모 의료 시스템에서는 기존 정형외과 거점에 내시경 검사, 이비인후과, 산부인과를 통합함으로써 고정비 대비 수익성을 높이고 있습니다. 이러한 전환으로 인해 향후 5년 동안 외래수술센터(ASC) 시장에서 다학제 진료 시설의 점유율이 몇 포인트 상승할 것으로 예측됩니다.
독립형 시설은 2025년 수익의 66.10%를 차지했습니다. 병원 캠퍼스에서 독립되어 있기 때문에 고소득층이 거주하는 교외나 기업 집적지 근처를 유연하게 입지로 선정할 수 있어 접근성 면에서 뚜렷한 우위를 점하고 있습니다. 또한, 많은 시설이 장시간 영업을 하고 있어 병원이 일정 조정에 어려움을 겪는 퇴근길 환자층을 유치하고 있습니다.
병원 내형 ASC는 수익의 33.90%를 차지하고 있으나, 연평균 성장률(CAGR) 8.76%로 성장할 전망입니다. 의료 시스템 각사는 의뢰 환자 기반을 유지하고, 이후 영상 진단 및 입원 환자 수를 확보하기 위해 이용률이 낮은 시술실을 규정에 부합하는 외래 수술 시설로 전환하고 있습니다. 초기 분석 결과에 따르면, 병원의 전자차트 시스템과의 연동을 통해 의뢰 사이클이 단축되었으며, 이것이 추가적인 성장을 견인하고 있습니다. 이러한 변화로 인해 외래수술센터(ASC) 시장에서 병원 제휴 시설의 점유율은 꾸준히 확대될 전망이며, 특히 고가의 영상 진단 인프라가 필요한 척추 및 구조적 심장 질환 프로그램에서 이러한 경향이 두드러집니다.
지역별 분석
북미는 2025년 매출의 36.10%를 차지하며 선도적 지위를 공고히 했습니다. ‘필요성 증명서(Certificate-of-Need)’의 지속적인 완화와 CMS(미국 의료보험서비스센터)에 의한 일관된 지급 기준 업데이트가 지역적 확장을 뒷받침하고 있습니다. 2024년 1월 핼리팩스의 QEII 헬스 사이언스 센터에 100만 달러가 기부된 것을 배경으로, 로봇 보조 척추 프로그램은 이 지역이 기술 집약적이고 중증도가 높은 사례에 주력하고 있음을 보여줍니다. 이러한 투자를 통해 해당 지역의 사례 중증도는 향상될 것이며, 지불 주체의 면밀한 검토가 있음에도 불구하고 적정한 가격 결정력이 유지될 전망입니다.
유럽에서는 도입 양상이 더욱 다양해지고 있습니다. 영국, 독일, 프랑스가 개발을 주도하고 있으며, 각국의 공공-민간 협력(PPP) 체계를 활용하여 의료 접근성 확보 의무와 민간 부문의 효율성을 양립시키고 있습니다. 엄격한 수술 후 품질 지표와 통합 치료 경로를 통해 당일 수술의 잠재적 수요가 꾸준히 외래 수술 건수로 전환되고 있습니다.
아시아는 가장 빠른 성장세를 보이고 있으며, 2031년까지의 연평균 성장률(CAGR)은 9.95%로 예측됩니다. 중산층 수요 증가, 민간 의료보험의 확대, 그리고 인프라 구축에 대한 공공 인센티브가 중국과 인도 전역에서의 건설을 뒷받침하고 있습니다. 다국적 기업들은 규제 위험을 완화하면서 비보험 수요를 흡수하기 위해, 3차 의료기관 내에 합작 투자 형태로 당일 수술센터(ASC)를 시범적으로 설립하기 시작했습니다. 수술의 전환이 진행됨에 따라, 전 세계 외래수술센터(ASC) 시장에서 아시아의 점유율은 크게 상승할 전망입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.28According to Mordor Intelligence, ambulatory surgery center market size in 2026 is estimated at USD 88.17 billion, growing from 2025 value of USD 83.88 billion with 2031 projections showing USD 113.18 billion, growing at 5.12% CAGR over 2026-2031.
This report Segments the Industry Into by Center Type (Single-Specialty Centers, Multi-Specialty Centers), Modality (Hospital-Based ASCs, Freestanding ASCs), Ownership (Physician-Owned, and More), Services, Specialty, and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Ambulatory Surgery Center Market Trends and Insights
Expansion of CMS-Approved ASC Procedure List Accelerating High-Acuity Shift
The CY 2025 Hospital Outpatient Prospective Payment System final rule added 20 complex interventions, including select percutaneous coronary procedures, to the ambulatory list.Centers that upgrade imaging suites and credential multidisciplinary teams are already capturing new referral streams and securing premium commercial contracts. Cardiovascular throughput is expected to sustain a 9.65% CAGR to 2030, giving early movers a defensible payor-mix advantage. Larger health systems are converting underutilised hospital outpatient departments into dedicated hybrid ASCs to comply with the 24-hour discharge rule while tapping higher case volumes.
Certificate-of-Need Deregulation Enabling Rapid Build-Outs
Legislative rollbacks in Georgia, Florida, and West Virginia are lowering barriers to entry for greenfield developments. Georgia's HB 1339, in force since July 2024, exempts many new centers from the previous CON process, prompting a pipeline of more than 30 filings in metro Atlanta alone. Operators with sophisticated site-selection analytics are locking in leases near population growth corridors ahead of rivals and leveraging local physician partnerships to accelerate payer credentialing. The pace of filings indicates a likely supply surge that could compress occupancy in the medium term yet should widen patient access in historically underserved suburbs.
Peri-operative Nurse & Anesthetist Shortages Limiting OR Utilisation Rates
The supply of certified registered nurse anesthetists remains below demand, especially in rural markets where they are often the sole anaesthesia providers. Rising wage inflation and burnout have compounded recruitment challenges, forcing some centers to cap block times even when demand exists. Operators are responding with accelerated residency pipelines and tuition assistance agreements tied to multi-year employment contracts. Centers that offer flexible scheduling and clinical ladders are holding turnover to the low single digits, sustaining utilisation levels.
Other drivers and restraints analyzed in the detailed report include:
- High-Deductible Health Plans & Price Transparency Steering Patients Toward Low-Cost ASCs
- AI-Driven Workflow Solutions Raising Throughput in Ophthalmology & Orthopedics
- Reimbursement Gaps vs HOPD Eroding Margins in Cardiac & Spine Cases
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Single-specialty centers generated 61.78% of 2025 revenue, underpinned by clinically efficient musculoskeletal, ophthalmic, and pain-management service lines. The operators of single-specialty sites reported average same-room turnover times under 14 minutes, a key factor in physician loyalty. Focused staffing models, equipment reuse, and aligned implant formularies have historically driven EBITDA margins into the mid-30% range.
Multi-specialty centers, while smaller today, are forecast to outgrow single-discipline peers at 8.09% annually through 2031. Diversified case mixes cushion reimbursement volatility and boost scheduling density across the week. Larger systems are layering endoscopy, ENT, and women's health into existing orthopedic hubs, raising yield on fixed costs. This pivot is expected to push the multi-specialty slice of the ambulatory surgical centers market share several points higher over the next five years.
Freestanding facilities held 66.10% of 2025 revenue. Their independence from hospital campuses allows flexible site selection near high-income suburbs and employer clusters, a distinct access advantage. Many also operate extended hours, capturing after-work cases that hospitals struggle to schedule.
Hospital-based ASCs represented 33.90% of revenue but are set to grow at a 8.76% CAGR. Health systems are converting underused procedural suites into compliant ambulatory sites to defend referral bases and secure downstream imaging and inpatient volumes. Early evidence suggests that alignment with hospital electronic health records shortens referral cycles, driving incremental growth. This shift should steadily lift the hospital-affiliated slice of the ambulatory surgical centers market size, especially for spine and structural heart programs that demand costly imaging infrastructure.
Complete Report Scope:
- By Center Type
- Single-Specialty Centers
- Gastroenterology Centers
- Ophthalmology Centers
- Orthopedic Centers
- Pain Management Centers
- Cardiology Centers
- Cosmetic Surgery Centers
- Other Single-Specialty
- Multi-Specialty Centers
- Single-Specialty Centers
- By Modality
- Hospital-based ASCs
- Freestanding ASCs
- By Ownership
- Physician-Owned
- Hospital-Owned
- Corporate / Private-Equity-Owned
- Joint-Venture
- By Services
- Surgical Services
- Diagnostic and Imaging Services
- By Specialty
- Gastroenterology
- Ophthalmology
- Orthopedics
- Pain / Neurology
- Cardiovascular
- ENT
- Urology
- Gynecology
- Plastics and Reconstructive
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 36.10% of 2025 revenue, cementing its leadership position. Continued Certificate-of-Need rollbacks and consistent CMS payment updates encourage regional expansion. Robotic-enabled spine programs, underpinned by a USD 1 million donation to Halifax's QEII Health Sciences Centre in January 2024, showcase the region's tilt toward technology-rich high-acuity cases. These investments should lift regional case acuity and support modest pricing power despite payer scrutiny.
Europe presents a more heterogeneous adoption pattern. The United Kingdom, Germany, and France lead development, each leveraging public-private partnership frameworks that balance access mandates with private-sector efficiency. Stringent postoperative quality metrics and integrated care pathways support steady conversion of day-case potential into ambulatory volumes.
Asia delivers the fastest expansion, logging a projected 9.95% CAGR through 2031. Rising middle-class demand, private health-insurance growth, and public incentives for infrastructure build-outs spur construction across China and India. Multinational operators are trial-launching joint-venture ASCs within tertiary hospitals to mitigate regulatory risk while capturing self-pay demand. As procedure migration takes hold, the Asian contribution to global ambulatory surgical centers market share is set to rise materially.
- AMSURG
- United Surgical Partners International
- HCA Healthcare
- Surgery Partners
- Surgical Care Affiliates (Optum)
- Envision Healthcare
- SurgCenter Development
- Regent Surgical Health
- PE GI Solutions
- NueHealth / ValueHealth
- NorthStar Healthcare
- TriasMD
- Vision Integrated Partners
- Nobilis Health
- Covenant Physician Partners
- Mednax Services
- TeamHealth
- SCA Health International
- St. George Surgical Center
- Muve Health (ValueHealth)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of CMS-approved ASC Procedure List Accelerating High-Acuity Shift
- 4.2.2 Certificate-of-Need (CON) Deregulation Enabling Rapid ASC Build-Outs
- 4.2.3 High-Deductible Health Plans & Price-Transparency Rules Steering Patients Toward Low-Cost ASCs
- 4.2.4 AI-driven Workflow/Navigation Solutions Raising Throughput in Ophthalmology and Ortho ASCs
- 4.2.5 Rising Demand for Outpatient Surgeries
- 4.2.6 Patient Convenience and Expansion in Emerging Markets
- 4.3 Market Restraints
- 4.3.1 Peri-operative Nurse and Anesthetist Shortages Limiting OR Utilisation Rates
- 4.3.2 Reimbursement Gaps vs HOPD Eroding Margins in Cardiac & Spine Cases
- 4.3.3 High Initial Setup Costs
- 4.3.4 Shortage of Skilled Healthcare Professionals
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers/Consumers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitute Products
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Center Type
- 5.1.1 Single-Specialty Centers
- 5.1.1.1 Gastroenterology Centers
- 5.1.1.2 Ophthalmology Centers
- 5.1.1.3 Orthopedic Centers
- 5.1.1.4 Pain Management Centers
- 5.1.1.5 Cardiology Centers
- 5.1.1.6 Cosmetic Surgery Centers
- 5.1.1.7 Other Single-Specialty
- 5.1.2 Multi-Specialty Centers
- 5.1.1 Single-Specialty Centers
- 5.2 By Modality
- 5.2.1 Hospital-based ASCs
- 5.2.2 Freestanding ASCs
- 5.3 By Ownership
- 5.3.1 Physician-Owned
- 5.3.2 Hospital-Owned
- 5.3.3 Corporate / Private-Equity-Owned
- 5.3.4 Joint-Venture
- 5.4 By Services
- 5.4.1 Surgical Services
- 5.4.2 Diagnostic and Imaging Services
- 5.5 By Specialty
- 5.5.1 Gastroenterology
- 5.5.2 Ophthalmology
- 5.5.3 Orthopedics
- 5.5.4 Pain / Neurology
- 5.5.5 Cardiovascular
- 5.5.6 ENT
- 5.5.7 Urology
- 5.5.8 Gynecology
- 5.5.9 Plastics and Reconstructive
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 AMSURG
- 6.3.2 United Surgical Partners International
- 6.3.3 HCA Healthcare
- 6.3.4 Surgery Partners
- 6.3.5 Surgical Care Affiliates (Optum)
- 6.3.6 Envision Healthcare
- 6.3.7 SurgCenter Development
- 6.3.8 Regent Surgical Health
- 6.3.9 PE GI Solutions
- 6.3.10 NueHealth / ValueHealth
- 6.3.11 NorthStar Healthcare
- 6.3.12 TriasMD
- 6.3.13 Vision Integrated Partners
- 6.3.14 Nobilis Health
- 6.3.15 Covenant Physician Partners
- 6.3.16 Mednax Services
- 6.3.17 TeamHealth
- 6.3.18 SCA Health International
- 6.3.19 St. George Surgical Center
- 6.3.20 Muve Health (ValueHealth)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment