

|
시장보고서
상품코드
2116470
정제 코팅 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Tablet Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 정제 코팅 시장 규모는 10억 4,000만 달러로 추정되고 2025년 9억 8,600만 달러에서 확대해, 2031년에는 13억 3,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 5.12%가 될 것으로 전망됩니다.
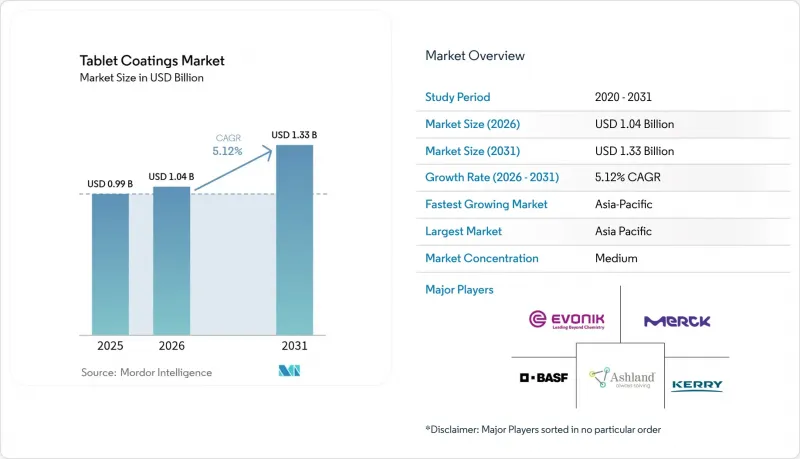
본 보고서는 코팅 유형(필름 코팅, 설탕 코팅 등), 폴리머(셀룰로오스 에테르, 아크릴산 폴리머 등), 제제 성분(가소제 등), 제조 공정/설비(기존 팬 코팅 등), 용도(즉방성 제제 등), 최종 사용자(제약 제조업체 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 정제 코팅 시장 동향 및 인사이트
전 세계 제약 제조 거점의 급속한 확대
각 제약사는 전례 없는 규모의 오프라인 시설 확장 열풍을 일으키고 있습니다. PCI Pharma Services는 미국 및 유럽에서 코팅에 적합한 생산 라인에 3억 6,500만 달러를 배정했으며, 한편 CordenPharma는 고도의 보호층이 필요한 펩타이드 사업에 9억 유로를 투자했습니다. 아시아에서는 WuXi STA가 169에이커 규모의 활성 성분 캠퍼스를 가동하며 펩타이드 생산 능력을 3배로 확대했습니다. 이는 해당 지역에서 복잡한 고형 제형에 대한 수요가 증가하고 있음을 반영합니다. 이러한 수백만 달러 규모의 움직임은 코팅용 폴리머, 안료, 가소제의 기초 소비량을 즉각적으로 끌어올립니다. 또한 롯데송진화학이 Colorcon과 체결한 7억 4,000만 달러 규모의 셀룰로오스 공급 계약 등 하류 부문에 대한 투자도 촉진하고 있습니다. 이 계약은 부형제 공급 분야에서 주도적인 입지를 확보하기 위한 것입니다. 더 많은 생물학적 제제가 경구 제형으로 전환됨에 따라, 수요는 기존의 배리어 필름에 그치지 않고, 민감한 유효 성분(API)을 위해 설계된 방습층 및 장용층까지 확대되고 있습니다. 공급업체에게 있어 공장 규모 확대는 지속적인 원료 수요, 노후화된 제조 설비의 착실한 갱신, 그리고 고품질의 즉시 사용 가능한 분말을 중시하는 인라인 품질 관리의 도입으로 이어집니다.
희귀질환 치료제 및 영양보조제의 급속한 보급
희귀질환 치료제의 승인 건수가 사상 최고치를 기록하고, 영양 보조제의 출시가 급증함에 따라 코팅 기술의 선택 폭도 넓어지고 있습니다. Vertex, Gilead 및 동종 업계의 혁신 기업들은 2024년에 각각 40억 달러 이상을 투자하여 희귀질환 치료제 후보 물질을 확보했습니다. 이러한 의약품에는 pH 의존성 방출 기전, 저용량에서 정확한 투여를 실현하기 위한 미세층 구조의 유효 성분이 요구되는 경우가 많습니다. 건강기능식품 분야에서는 컬러콘(Colorcon)사가 안정성을 해치지 않으면서 클린 라벨을 원하는 소비자의 요구를 충족하도록 설계된 최초의 수성 투명 유기 필름 시스템 ‘Nutrapure’를 출시했습니다. 에보닉(Evonik)의 ‘EUDRAGUARD(R)’ 시리즈는 프로바이오틱스에 적합한 장용 기능을 제공하며, 의약품 수준의 과학이 웰니스 제품에 응용되고 있음을 보여줍니다. 호비온(Hovion)과 젤리온 파마(Zelion Pharma)의 제휴를 통해, 높은 비표면적을 가진 ‘Dispersome’ 캐리어가 비타민 블렌드 분야로도 확대되면서, 처방약(Rx)과 일반의약품(OTC) 기술 간의 상호 교류가 두드러지고 있습니다. FDA가 신규 식품 성분에 관한 공고 규정을 명확히 함에 따라, 혁신적인 코팅 기술은 높은 이익률을 확보하면서도 더 신속하게 시장에 출시될 수 있게 되었습니다.
엄격하고 지역마다 다른 GMP 요건
규제의 미로가 실무 작업을 복잡하게 만들고 있습니다. 유럽의 2024년 의약품 법안 초안은 공급망 추적성에 대한 추가 요건을 부과하는 한편, FDA의 CFR 211.110 개정안에서는 과학적으로 정당화된 샘플링 계획을 의무화하고 있습니다. 아시아태평양에서는 PIC/S에 의한 조화가 진행되고 있음에도 불구하고, 각국 고유의 요건이 도입되어 제조업체는 인도, 중국, 일본을 대상으로 중복되는 신청 서류를 작성할 수밖에 없습니다. 코팅 업체의 경우, 각 관할 구역별로 흡기 온도, 분무 패턴, 세척 주기에 대한 새로운 검증이 요구될 수 있습니다. 이러한 행정 업무 증가는 출시 예산을 부풀리고, 세계 시장 진출을 지연시키며, 정제 코팅 시장에서 예상되었던 연평균 성장률(CAGR)의 상승세를 부분적으로 둔화시키고 있습니다.
부문별 분석
필름 코팅 정제는 2025년 매출의 52.74%를 차지했으며, 단일 코팅층으로 방습, 자외선 차단, 브랜드 색상을 한 번의 경제적인 공정으로 실현할 수 있음을 보여줍니다. 장용 코팅 정제 시장 규모는 생물학적 활성 물질이나 프로바이오틱스가 장내에서 방출되어야 하기 때문에 연평균 성장률(CAGR) 6.73%로 확대될 것으로 예측됩니다. 향후 5년 동안 필름 제제에는 위조 방지를 위한 디지털 워터마크 안료와 연속 생산 라인에 대응하기 위한 저발포성 계면활성제가 적용될 것입니다. 한편, 설탕 코팅에 대한 수요는 틈새 시장에 그칠 것으로 보이며, 주로 소아용 시럽을 씹을 수 있는 코어로 전환하는 용도로 활용될 전망입니다.
연속 처리는 이 공정의 체류 시간이 짧고, 즉시 사용 가능한 수성 시스템과 잘 어울리기 때문에 필름 코팅의 장점을 더욱 높여줍니다. 호비오네(Hovione)사의 리스본 공장에서는 연속 과립화와 직접 팬 코팅을 연계하여 배치 처리에 비해 사이클 타임을 30% 단축하고 있습니다. 장용 코팅 분야의 각 기업은 에보니크(Evonik)사의 ‘EUDRAGIT FL 30 D-55’를 필두로 가소제를 포함하지 않는 아크릴계 분산액을 사용하여 혁신을 추진하고 있으며, 이를 통해 조제 시간을 70% 단축하고 있습니다. 각 공급업체에서는 지연 방출층과 지속 방출층을 단일 공정으로 결합한 기능성 필름에 대한 주문이 증가하고 있으며, 이를 통해 설치 면적과 검증에 소요되는 시간을 절감할 수 있습니다.
셀룰로오스 에테르는 수십 년에 걸친 안전성 실적과 모든 약전에 등재됨에 따라 2025년 수요의 38.25%를 차지했습니다. 한편, 아크릴계는 향후 7.86%의 연평균 성장률(CAGR)을 보일 것으로 예측되며, 광범위한 정제 코팅 시장에서 가장 빠르게 성장하는 폴리머 분류로 자리매김하고 있습니다. 제약 업계의 구매자들은 저고형분 조건에서 뛰어난 필름 강도와 pH 조절의 용이성을 아크릴 계열의 장점으로 평가하고 있으며, 이 두 가지 모두 연속 분무법에서 중요한 요소입니다. 롯데송진화학과 칼라콘(Colorcon)의 제휴는 셀룰로오스 생산량을 대폭 확대하는 것을 목표로 하고 있으며, 이는 주요 사용자들이 여전히 기존 등급공급 안정성을 우선시하고 있음을 보여줍니다.
차세대 아크릴계 수지는 대장 표적화를 위해 4급 아민기를 포함하고 있는 반면, 바이오 유래 셀룰로오스는 지속가능성 감사에서 그 중요성이 커지고 있습니다. 아크릴계 수지가 확보하게 될 정제 코팅 시장 점유율은 TiO2에 대한 규제 압력으로부터도 혜택을 받을 것입니다. 많은 아크릴계 분산액은 불투명화제를 추가하지 않고도 정제 내부의 변색을 가릴 수 있기 때문입니다. 각 폴리머 제조업체는 상위 20개 제약 고객사의 ESG 요건에 부합하는 형태로, 스코프 1 배출량을 감축하기 위해 그린 케미스트리에 기반한 용매 회수 및 에너지 효율이 높은 반응 장치에 대한 투자를 추진하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 33.67%를 차지했으며, 연평균 성장률(CAGR) 7.72%를 나타낼 것으로 전망되어, 정제 코팅 시장에서 가장 크고 가장 빠르게 성장하는 지역이 될 것입니다. 인도의 CRDMO 사업자들은 정부의 생산 장려 정책에 힘입어 2030년까지 코팅정 생산량을 두 배로 늘리는 것을 목표로 하는 다년간의 설비 투자를 잇달아 발표하고 있습니다. 중국의 현대화 추진의 일환으로, WuXi STA는 펩타이드 복합 시설을 건설하여 분무 건조 및 필름 코팅 생산 능력을 3배로 확대되고 있습니다. 또한 한국의 SK pharmteco는 저분자 의약품 라인에 2억 6,000만 달러를 투자하며 이 지역의 성장세를 뒷받침하고 있습니다. 이러한 투자로 인해 하이드록시프로파일메틸셀룰로오스부터 특수 색상 혼합물에 이르기까지 코팅용 원자재 수요가 견인되고 있습니다.
북미는 여전히 혁신 면에서 우위를 유지하고 있습니다. FDA의 2025년 연속 제조 지침은 새로운 설비 발주를 촉진하고 있으며, 예상되는 1,600억 달러 규모의 제약 설비 투자는 기존 설비 개조 기회를 위한 안정적인 파이프라인을 제공합니다. PCI Pharma의 3억 6,500만 달러 규모의 설비 갱신과 Hovione의 뉴저지주에서 1억 7,000만 달러 규모의 확장 사업은 고부가가치 코팅 기술에 대한 노력을 두드러지게 하고 있습니다.
유럽에서는 이산화티타늄(TiO2)을 둘러싼 규제 불확실성에 직면해 있지만, 기술적 리더십과 대규모 펩타이드 프로젝트를 통해 이를 보완하고 있습니다. 코덴파마의 9억 유로 투자 결정은 지속적인 자신감을 뒷받침하고 있으며, 에보닉의 사업 재편을 통해 고성장이 예상되는 약물 전달용 코팅 분야에 자원이 집중되고 있습니다. 곧 발표될 EMA의 TiO₂에 대한 견해는 제제 재설계의 물결을 일으킬 가능성이 있으며, 탄산칼슘계 불투명제 및 고분자계 백색제 공급업체에 새로운 수익원을 가져다줄 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.31According to Mordor Intelligence, tablet coatings market size in 2026 is estimated at USD 1.04 billion, growing from 2025 value of USD 0.986 billion with 2031 projections showing USD 1.33 billion, growing at 5.12% CAGR over 2026-2031.
This report is Segmented by Coating Type (Film-Coated, Sugar-Coated, and More), Polymer (Cellulose Ethers, Acrylic Acid Polymers, and More), Formulation Component (Plasticizers, and More), Process/Equipment (Conventional Pan Coating, and More), Application (Immediate-Release, and More), End-User (Pharmaceutical Manufacturers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD)
Global Tablet Coatings Market Trends and Insights
Expeditious Growth Of The Global Pharmaceutical Manufacturing Base
Drug makers have launched an unprecedented wave of bricks-and-mortar expansion. PCI Pharma Services earmarked USD 365 million for coating-friendly lines in the United States and Europe, while CordenPharma allocated EUR 900 million to peptides that rely on sophisticated protective layers. In Asia, WuXi STA activated a 169-acre active-ingredient campus and tripled peptide capacity, reflecting the region's appetite for complex solid forms. These multimillion-dollar moves immediately lift baseline consumption of coating polymers, pigments, and plasticizers. They also spur downstream investments such as Lotte Fine Chemical's USD 740 million cellulose pact with Colorcon, which aims to secure a leadership position in excipient supply. As more biologicals make the leap to oral dosage, demand extends beyond conventional barrier films into moisture-tight or enteric layers engineered for fragile APIs. For suppliers, the expanding factory footprint translates into recurring raw-material volumes, steady retrofits of aging pans, and adoption of inline quality controls that favor premium, ready-to-use powders.
Rapid Adoption Of Orphan Drugs & Nutraceuticals
Record orphan-drug approvals and booming nutraceutical launches broaden the coating toolbox. Vertex, Gilead, and peer innovators each spent more than USD 4 billion in 2024 to secure rare-disease candidates that often demand pH-dependent release or micro-layered actives for low-dose accuracy. On the supplement side, Colorcon debuted Nutrapure, the first aqueous clear organic film system, crafted to satisfy clean-label consumers without compromising stability. Evonik's EUDRAGUARD(R) line delivers probiotic-friendly enteric functionality, showing how pharmaceutical-grade science migrates into wellness products. Hovione's pact with Zerion Pharma extends high-surface-area Dispersome carriers to vitamin blends, highlighting the cross-pollination of Rx and OTC technologies. With the FDA now offering clearer notification rules for new dietary ingredients, novel coatings can reach shelves faster while capturing premium margins.
Stringent & Divergent Regional GMP Requirements
Regulatory labyrinths complicate execution. Europe's 2024 draft medicines law adds layers of supply-chain traceability, while the FDA's CFR 211.110 revision mandates scientifically justified sampling plans. Asia-Pacific introduces country-specific modules despite PIC/S harmonization, forcing manufacturers to compile overlapping dossiers for India, China, and Japan. For coaters, each jurisdiction can demand fresh validation of inlet air temperature, spray pattern, and cleaning cycles. The added paperwork inflates launch budgets and slows global rollout, blunting some CAGR upside predicted for the tablet coatings market.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand For Taste-Masking & Aesthetic Coatings For Pediatric And Geriatric Compliance
- Shift Toward Continuous Manufacturing In Solid-Dose Formulations
- Time- and Cost-Intensive Coating Process Validation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Film-coated tablets contributed 52.74% of 2025 revenue, underscoring how a single layer can combine moisture protection, UV shielding, and brand color in one economical pass. The tablet coatings market size for enteric-coated formats is projected to rise at 6.73% CAGR as biologic actives and probiotics demand intestine-directed release. Over the next five years, film formulations will integrate digital watermark pigments for anti-counterfeiting and low-foaming surfactants to support continuous lines. Concurrently, sugar-coat demand will stay niche, serving mainly pediatric syrups converted into chewable cores.
Continuous processing magnifies film-coat advantages because the step's short residence time aligns well with ready-to-use aqueous systems. Hovione's Lisbon installation links continuous granulation to direct pan coating, demonstrating 30% faster cycle times versus batch. Enteric players innovate with plasticizer-free acrylic dispersions that cut preparation time by 70%, led by Evonik's EUDRAGIT FL 30 D-55. Suppliers see rising orders for functional films combining delayed and sustained-release layers in single-step processes, saving floor space and validation hours.
Cellulose ethers owned 38.25% of 2025 demand thanks to a decades-long safety record and universal compendial listings. Acrylics, however, show an 7.86% forward CAGR, positioning them as the fastest polymer class in the broader tablet coatings market. Pharmaceutical buyers value acrylics for superior film strength under low solids and for ease of pH tuning, both key for continuous spray. Lotte Fine Chemical's partnership with Colorcon aims to enlarge cellulose output dramatically, a sign core users still prioritize supply security for traditional grades.
Next-generation acrylics integrate quaternary-amine groups for colon targeting, while bio-based celluloses gain momentum in sustainability audits. The tablet coatings market share that acrylics capture will also benefit from regulatory pressures on TiO2 because many acrylic dispersions mask core discoloration without added opacifiers. Polymer producers invest in green-chemistry solvent recovery and energy-efficient reactors to lower scope-1 emissions, aligning with ESG mandates from top-20 pharma customers.
Complete Report Scope:
- By Coating Type
- Film-coated
- Sugar-coated
- Enteric-coated
- Functional coatings
- Other coating types
- By Polymer
- Cellulose ethers
- Acrylic acid polymers
- Vinyl alcohol polymers
- Polyethylene glycol & derivatives
- Other polymers
- By Formulation Component
- Plasticizers
- Colorants
- Solvents / Vehicles
- Opacifiers & anti-tack agents
- By Process / Equipment
- Conventional pan coating
- Perforated pan coating
- Fluidized-bed coating
- Continuous coating systems
- By Application
- Immediate-release
- Sustained-release
- Extended-release
- Delayed / enteric release
- By End-User
- Pharmaceutical manufacturers
- Nutraceutical & dietary-supplement companies
- CDMOs & CMOs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific controlled 33.67% of 2025 revenue and is projected for an 7.72% CAGR, making it both the largest and the fastest region in the tablet coatings market. India's CRDMO operators collectively announce multi-year capex aimed at doubling coated-tablet output by 2030, supported by government production incentives. China's modernization drive includes WuXi STA's peptide complex that triples spray-drying and film-coating capacity; Korean player SK pharmteco injects USD 260 million into small-molecule lines, underscoring regional momentum. These investments pull in coating raw materials ranging from hydroxypropyl methylcellulose to specialized color blends.
North America retains its innovation edge. The FDA's 2025 guideline on continuous processing triggers fresh equipment orders, while USD 160 billion in projected pharmaceutical capex provides a steady pipeline for retrofit opportunities. PCI Pharma's USD 365 million upgrade and Hovione's USD 170 million New Jersey expansion highlight the commitment to higher-value coating technologies.
Europe wrestles with regulatory unknowns surrounding TiO2 but compensates through technology leadership and large-scale peptide projects. CordenPharma's EUR 900 million commitment underlines continued confidence, and Evonik's restructuring channels resources into high-growth drug-delivery coatings. The upcoming EMA opinion on TiO2 may catalyze a wave of reformulations, providing suppliers of calcium-carbonate opacifiers and polymeric whiteners with new revenue streams.
- BPSI Holdings
- BASF
- Evonik Industries
- Ashland Global Holdings
- Kerry Group plc
- Merck
- DuPont
- Sensient Technologies Corp.
- Wincoat Colours & Coatings Pvt Ltd
- Corel Pharma Chem
- JRS Pharma
- Eastman Chemical Company
- Roquette Freres
- Biogrund GmbH
- Ideal Cures Pvt Ltd
- Seppic (Air Liquide)
- Omya AG
- IMCD Group
- DFE Pharma
- ABITEC Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expeditious Growth Of The Global Pharmaceutical Manufacturing Base
- 4.2.2 Rapid Adoption Of Orphan Drugs & Nutraceuticals
- 4.2.3 Growing Demand For Taste-Masking & Aesthetic Coatings For Pediatric And Geriatric Compliance
- 4.2.4 Shift Toward Continuous Manufacturing In Solid-Dose Formulations
- 4.2.5 Personalized Medicine Driving Demand For Mini-Tabs & Micro-Encapsulation
- 4.2.6 Accelerated Regulatory Approvals Shortening Time-To-Market For Reformulated Tablets
- 4.3 Market Restraints
- 4.3.1 Stringent & Divergent Regional GMP Requirements
- 4.3.2 Time- And Cost-Intensive Coating Process Validation
- 4.3.3 Rising Scrutiny Of Titanium-Dioxide Use
- 4.3.4 Supply-Chain Volatility In Specialty Polymers
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Coating Type
- 5.1.1 Film-coated
- 5.1.2 Sugar-coated
- 5.1.3 Enteric-coated
- 5.1.4 Functional coatings
- 5.1.5 Other coating types
- 5.2 By Polymer
- 5.2.1 Cellulose ethers
- 5.2.2 Acrylic acid polymers
- 5.2.3 Vinyl alcohol polymers
- 5.2.4 Polyethylene glycol & derivatives
- 5.2.5 Other polymers
- 5.3 By Formulation Component
- 5.3.1 Plasticizers
- 5.3.2 Colorants
- 5.3.3 Solvents / Vehicles
- 5.3.4 Opacifiers & anti-tack agents
- 5.4 By Process / Equipment
- 5.4.1 Conventional pan coating
- 5.4.2 Perforated pan coating
- 5.4.3 Fluidized-bed coating
- 5.4.4 Continuous coating systems
- 5.5 By Application
- 5.5.1 Immediate-release
- 5.5.2 Sustained-release
- 5.5.3 Extended-release
- 5.5.4 Delayed / enteric release
- 5.6 By End-User
- 5.6.1 Pharmaceutical manufacturers
- 5.6.2 Nutraceutical & dietary-supplement companies
- 5.6.3 CDMOs & CMOs
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 BPSI Holdings LLC (Colorcon)
- 6.3.2 BASF SE
- 6.3.3 Evonik Industries AG
- 6.3.4 Ashland Global Holdings
- 6.3.5 Kerry Group plc
- 6.3.6 Merck KGaA
- 6.3.7 DuPont de Nemours Inc.
- 6.3.8 Sensient Technologies Corp.
- 6.3.9 Wincoat Colours & Coatings Pvt Ltd
- 6.3.10 Corel Pharma Chem
- 6.3.11 JRS Pharma
- 6.3.12 Eastman Chemical Company
- 6.3.13 Roquette Freres
- 6.3.14 Biogrund GmbH
- 6.3.15 Ideal Cures Pvt Ltd
- 6.3.16 Seppic (Air Liquide)
- 6.3.17 Omya AG
- 6.3.18 IMCD Group
- 6.3.19 DFE Pharma
- 6.3.20 ABITEC Corporation
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


