|
시장보고서
상품코드
2116474
혈액 스크리닝 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Blood Screening - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
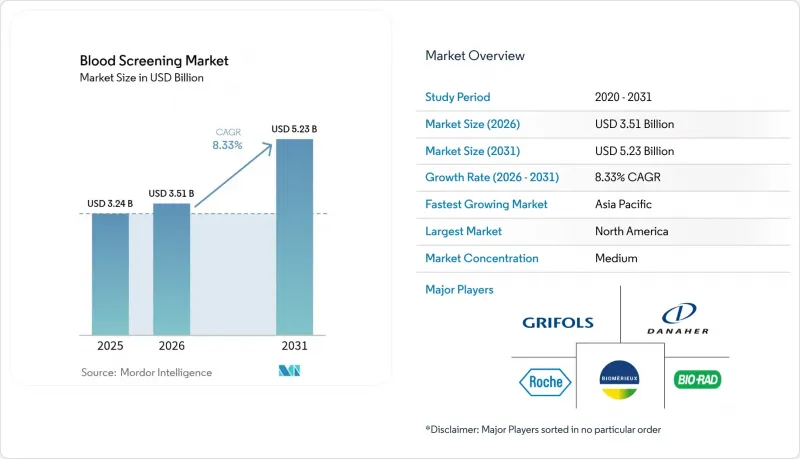
에 의하면, 2026년 혈액 스크리닝 시장 규모는 35억 1,000만 달러로 추정되고 2025년 32억 4,000만 달러에서 확대해, 2031년에는 52억 3,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 8.33%가 될 것으로 전망됩니다.
본 보고서는 제품별(시약 및 키트, 기기 등), 기술별(핵산 증폭 검사(TMA 등), 면역 측정법, 신속 검사 등),스크리닝 대상별(감염병 패널(HIV 등), 혈액형 판정 등), 최종 사용자별(혈액은행, 병원 등), 지역별(북미 등)로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 혈액 스크리닝 시장 동향 및 인사이트
헌혈 증가에 따라 수혈용 스크리닝 수요가 높아지고 있습니다.
중국에서 재기증자에게 보상을 제공하는 ‘2025 이니셔티브’와 같은 집단 헌혈 캠페인을 통해, 팬데믹 당시 감소했던 공급량이 회복되면서 확장 가능한 스크리닝에 대한 새로운 수요가 발생하고 있습니다. 이와 동시에, 미국 식품의약국(FDA)이 위험 기반 헌혈자 평가로 전환함에 따라 남성 간 성행위를 하는 사람에 대한 일률적인 헌혈 금지 조치가 철폐되어 헌혈 적격자층이 확대되는 한편, 1단위당 스크리닝의 복잡성이 증가하고 있습니다. 헌혈량 증가와 헌혈자의 다양화가 맞물리면서, 혈액 기관들은 민감도를 저하시키지 않으면서 처리 능력을 높이기 위해 완전 자동화된 검사법과 로봇 기술의 도입을 촉진하고 있습니다.
수혈을 통해 전파되는 감염병 유병률 증가
미국 질병통제예방센터(CDC)는 2024년 북미와 남미 대륙에서 뎅기열 사례 수가 1,300만 건에 달하고, 전년 대비 2배 이상 증가함에 따라, 2025년을 대비해 경보를 발령했습니다. 불가리아에서 발생한 서부 나일열의 동시 다발적 유행과 혈소판 제제를 매개로 한 원숭이두창의 산발적 감염 사례는 HIV·HBV·HCV 등 3대 감염병에 국한되지 않는 다항목 검사의 필요성을 부각시키고 있습니다. 이러한 검사 패널의 급속한 확대에 따라, 단일 워크플로우 내에서 신종 플라비바이러스, 오르토포크스바이러스 및 지역 특유의 병원체를 선별할 수 있는 NAT 시약에 대한 수요가 증가하고 있습니다.
높은 설비 투자 및 소모품 비용
FDA의 추산에 따르면, 새로 확정된 LDT 규정을 준수하기 위해서는 미국 내 스크리닝 부문에서 연간 약 5억 6,600만 달러에서 35억 6,000만 달러의 비용이 소요될 것으로 예측됩니다. 신흥 경제국에서는 NAT 플랫폼에 막대한 초기 투자와 고품질의 콜드체인 시약이 필요하기 때문에 더욱 큰 어려움에 직면해 있습니다. 마이크로플루이딕스 칩의 도입으로 검사당 비용은 9.5달러까지 낮아졌지만, 소규모 혈액 센터의 경우 전반적인 비용 부담이 여전히 과제로 남아 있습니다.
부문별 분석
시약 및 키트는 NAT, 면역 분석법 및 확인 검사용 구성 요소에 대한 지속적인 수요로 인해 2025년에도 혈액 선별 검사 시장 점유율의 55.62%를 유지했습니다. 이러한 우위는 독자적인 배합을 고정화하는 로트별 규제 검증에 의해 더욱 공고해졌습니다. 장비 부문은 연평균 성장률(CAGR) 9.78%로 확대되고 있습니다. 이는 실험실이 로봇 피펫팅, 바코드 추적, LIS 연결 기능을 통합한 완전 자동 NAT 워크셀 및 차세대 면역 분석기로 업그레이드하고 있기 때문입니다.
AI 지원 미들웨어의 급증도 주목할 만합니다. OneBlood의 도입으로 재고 수준이 40% 감소하여 실시간 분석의 운영적 가치가 입증되었습니다. 따라서 혈액은행이 예측 대시보드와 자동 이상치 보고서를 요구함에 따라 소프트웨어 및 서비스 매출이 가속화되고 있으며, 이러한 추세는 2028년 이후 시약의 성장률을 상회할 가능성이 있습니다. 한편, Dragonfly 플랫폼으로 대표되는 휴대용 분자진단 기기의 등장은 분산형 검사가 장기적으로 기기 하위 부문의 세분화를 더욱 촉진할 가능성을 시사합니다.
NAT는 HIV-1/2, HBV, HCV의 윈도우 기간 동안 바이러스 핵산을 검출하는 능력이 여전히 타의 추종을 불허하기 때문에 2025년 혈액 선별 검사 시장에서 41.88%라는 견고한 점유율을 유지했습니다. 그럼에도 불구하고 차세대 염기서열 분석(NGS)은 연평균 성장률(CAGR) 11.02%라는 빠른 속도로 확대되고 있습니다. mNGS는 예상치 못한 병원체를 식별하고, 중복 감염을 파악하며, 집단 감염 시 유전체 감시를 지원할 수 있으며, 패혈증 연구에서 74.0%의 검출률이 그 증거입니다.
기존의 효소면역측정법(ELISA/CLIA)은 장비 비용이 저렴하고 워크플로가 단순하기 때문에 자원이 제한된 환경에서는 여전히 주류를 이루고 있습니다. 신속 검사는 긴급 상황의 요구를 충족시키지만, NAT와 비교할 때 민감도 측면에서 한계가 있습니다. 웨스턴 블롯은 HIV 확정 진단에서 여전히 틈새 분야로 자리 잡고 있습니다. AI 도구가 방대한 분자 데이터 세트를 분석함에 따라, 검사실에서는 NAT와 NGS를 공통의 정보 처리 계층 내에서 통합하고, 궁극적으로는 이러한 기술 간의 경계를 모호하게 만들 가능성이 있습니다.
지역별 분석
2025년, 북미는 혈액 선별 시장의 35.10%를 차지했습니다. FDA의 위험 기반 기증자 적격성 지침, AI를 활용한 재고 관리, 그리고 LDT(실험실 개발 검사)에 대한 감독 체계의 지속적인 도입이 맞물려 이 지역의 기술적 우위를 유지하고 있습니다. 캐나다의 진단 분야는 퀘스트 다이아그노스틱스(Quest Diagnostics)가 라이프랩(LifeLab)의 완전한 지배권을 확보함에 따라 확대되었으며, 분자 검사 역량과 국경을 넘는 검체 물류가 강화되었습니다. 한편, 멕시코에서는 지방의 헌혈 인프라가 정비되고 있어, 이에 따라 중급 면역 분석 기기에 대한 수요가 증가하고 있습니다.
아시아태평양은 성장의 원동력이며, 2031년까지의 연평균 성장률(CAGR)은 9.86%로 예측됩니다. 일본에서 2025년에 실시된 헤모글로빈 베시큘에 관한 임상시험(세계 최초의 인공 혈액 임상시험)은 향후 헌혈 공급에 대한 의존도를 낮추고, 상온에서의 보존 기간을 2년으로 연장할 가능성이 있습니다. 인도의 ‘Quick Vitals’ 안면 스캔 플랫폼은 1분 이내에 비침습적 혈액 검사 결과를 제공하며, 공립 병원에서 시범 도입이 진행되고 있어 이 지역이 혁신적인 진단 기술에 대해 긍정적인 태도를 보이고 있음을 보여줍니다. 중국의 지중해빈혈 전국 유병률 8.95%는 산전 및 헌혈자 선별 검사 건수가 상당히 많음을 시사하며, 현재 진행 중인 집단 헌혈 캠페인을 통해 2선 도시의 채혈 거점이 확대되고 있습니다.
유럽에서는 회원국 간의 감독 기능을 통합하고 위기 대응을 위한 자금을 배분하는 규정(EU) 2024/1938에 따라 꾸준한 진전이 나타나고 있습니다. 독일과 프랑스에서는 기존의 선별 검사에 더해 병원체 저감 혈소판의 시범 도입이 진행되고 있습니다. 한편, 불가리아에서는 서니로열열 유행에 따라 지역 혈액은행에서 NAT 검사 패널이 확충되었습니다. 해당 규정에 따른 통일된 지침으로 인해 공급업체 승인 절차가 합리화되고, 유럽 전역에서 플랫폼 표준화가 촉진될 전망입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.31According to Mordor Intelligence, blood screening market size in 2026 is estimated at USD 3.51 billion, growing from 2025 value of USD 3.24 billion with 2031 projections showing USD 5.23 billion, growing at 8.33% CAGR over 2026-2031.
This report is Segmented by Product (Reagents and Kits, Instruments and More), Technology (Nucleic Acid Amplification Test [TMA and More], Immunoassay, Rapid Tests and More), Screening Target (Infectious Disease Panels [HIV and More], Blood Group Typing and More), End-User (Blood Banks, Hospitals, and More), and Geography (North America and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Blood Screening Market Trends and Insights
Rising blood donations leading to higher transfusion screenings
Group-donation campaigns, such as China's 2025 initiative that rewards repeat donors, are reversing the pandemic dip in supply and creating fresh demand for scalable screening. A parallel shift by the United States Food and Drug Administration (FDA) to risk-based donor assessment removes categorical deferrals for men who have sex with men, enlarging the eligible pool while increasing the complexity of per-unit screening. Together, higher volumes and donor diversity are encouraging blood establishments to adopt fully automated assays and robotics so that throughput rises without compromising sensitivity.
Greater prevalence of transfusion-transmissible infections
The Centers for Disease Control and Prevention (CDC) issued a 2025 alert after 13 million dengue cases occurred in the Americas during 2024, more than twice the prior year.Concurrent West Nile outbreaks in Bulgaria and isolated monkeypox transmissions through platelet products underline the need for multiplex assays that go beyond the HIV-HBV-HCV triad. Rapid expansion of such panels has lifted demand for NAT reagents that can screen for emerging flaviviruses, orthopoxviruses, and region-specific pathogens within one workflow.
High capital and consumable costs
Compliance with the newly finalized LDT rule will cost the U.S. screening sector an estimated USD 566 million to USD 3.56 billion each year, according to FDA modelling. Emerging economies struggle even more because NAT platforms require significant upfront spending and high-grade cold-chain reagents. Although microfluidic chips have driven per-test costs down to USD 9.5, overall affordability remains a challenge for smaller blood centres.
Other drivers and restraints analyzed in the detailed report include:
- Stricter regulatory guidelines for blood safety
- Technological advances in screening methods
- Limited skilled workforce and lab infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reagents and kits retained 55.62% of blood screening market share in 2025 due to recurring demand for NAT, immunoassay and confirmatory components. Their dominance is reinforced by batch-specific regulatory validation that locks in proprietary formulations. The instruments category is expanding at 9.78% CAGR as laboratories upgrade to fully automated NAT workcells and next-generation immunoassay analyzers that integrate robotic pipetting, bar-code tracking and LIS connectivity.
A surge in AI-enabled middleware is also notable; OneBlood's deployment cut inventory levels by 40%, proving the operational value of real-time analytics. Software & services revenues therefore accelerate as blood banks seek predictive dashboards and automated deviation reporting, a trend likely to outpace reagent growth beyond 2028. Meanwhile, the emergence of portable molecular diagnostic devices, typified by the Dragonfly platform, suggests that decentralized testing could further fragment the instruments sub-segment over the long term.
NAT maintained a robust 41.88% share of the blood screening market in 2025 as its capacity to detect viral nucleic acids during window periods remains unmatched for HIV-1/2, HBV and HCV. Nevertheless, next-generation sequencing is scaling quickly at an 11.02% CAGR. mNGS can uncover unexpected pathogens, pinpoint co-infections and support genomic surveillance during outbreaks, evidenced by a 74.0% detection rate in sepsis studies.
Traditional enzyme immunoassays (ELISA/CLIA) still dominate in lower-resource settings because of lower instrumentation costs and simpler workflows. Rapid tests fill emergency needs but struggle with sensitivity versus NAT. Western blot retains a niche for confirmatory HIV workups. As AI tools mine large molecular datasets, labs may unify NAT and NGS within a common informatics layer, eventually blurring the boundaries between technologies.
Complete Report Scope:
- By Product
- Reagents & Kits
- NAT Reagents and Kits
- Immunoassay Reagents and Kits
- Other Reagents and Kits (WB, Rapid, WB)
- Instruments
- Automated NAT Systems
- Immunoassay Analysers (ELISA/CLIA)
- Point-of-Care Molecular Devices
- Software & Services
- Reagents & Kits
- By Technology
- Nucleic Acid Amplification Test (NAT)
- TMA
- Real-time PCR
- Immunoassay
- ELISA
- CLIA / EIA
- Rapid Tests (Lateral-flow)
- Next-Generation Sequencing (NGS)
- Western Blotting
- Emerging Point-of-Care Molecular Tests
- Nucleic Acid Amplification Test (NAT)
- By Screening Target
- Infectious Disease Panels
- HIV
- HBV
- HCV
- Emerging Pathogens (Zika, WNV, Dengue)
- Blood Group Typing
- Rare Antigen Genotyping
- Infectious Disease Panels
- By End-User
- Blood Banks
- Hospitals
- Clinical Laboratories
- Plasma Fractionation Centres
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 35.10% of the blood screening market in 2025. The FDA's risk-based donor eligibility guidance, AI-assisted inventory management, and ongoing implementation of LDT oversight collectively maintain the region's technology edge. Canada's diagnostics sector expanded after Quest Diagnostics took full control of LifeLabs, deepening molecular-testing capacity and cross-border sample logistics. Meanwhile, Mexico is improving rural donation infrastructure, which lifts demand for mid-tier immunoassay analyzers.
Asia-Pacific is the growth engine, projected at a 9.86% CAGR to 2031. Japan's 2025 hemoglobin-vesicle trial-the world's first artificial-blood clinical study-could eventually reduce dependence on donor supply and lengthen storage life to two years at room temperature. India's Quick Vitals facial-scan platform delivers non-invasive hemogram readouts within a minute and is being piloted in public hospitals, underscoring the region's openness to disruptive diagnostics. China's national carrier rate of 8.95% for thalassemia points to substantial prenatal and donor screening volume, while ongoing group-donation campaigns expand collection points in second-tier cities.
Europe shows steady progress under Regulation (EU) 2024/1938, which pools oversight across member states and allocates funds for crisis readiness. Germany and France are trial-ling pathogen-reduced platelets alongside traditional screening, whereas Bulgaria's West Nile outbreak prompted expanded NAT panels at regional blood bank. The regulation's unified guidance will streamline vendor approvals, encouraging pan-European platform standardization.
- Roche
- Grifols
- Abbott Laboratories
- bioMerieux
- Bio-Rad Laboratories
- Beckton Dickinson
- Danaher
- DiaSorin
- Siemens Healthineers
- Thermo Fisher Scientific
- Ortho Clinical Diagnostics
- Revvity
- Hologic
- QIAGEN
- Illumina
- GRAIL, Inc
- Immucor
- Meril Life Sciences
- Mindray
- Sysmex
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Blood Donations Leading To Increased Transfusion Screenings
- 4.2.2 Increasing Prevalence Of Transfusion-Transmissible Infections
- 4.2.3 Stringent Regulatory Guidelines For Blood Safety
- 4.2.4 Technological Advancement In Blood Screening Methods
- 4.2.5 Rising Awareness For Blood Transmitted Infections And Increasing Number Of Blood Banks
- 4.2.6 AI-Driven Inventory Optimisation Platforms In Blood Banks
- 4.3 Market Restraints
- 4.3.1 High Capital & Consumable Cost For Screening
- 4.3.2 Limited Skilled Workforce And Laboratory Infrastructure
- 4.3.3 Competition From Pathogen-Reduction Technologies
- 4.3.4 Reagent Supply-Chain Disruptions (Geo-Politics & Cold-Chain)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Product
- 5.1.1 Reagents & Kits
- 5.1.1.1 NAT Reagents and Kits
- 5.1.1.2 Immunoassay Reagents and Kits
- 5.1.1.3 Other Reagents and Kits (WB, Rapid, WB)
- 5.1.2 Instruments
- 5.1.2.1 Automated NAT Systems
- 5.1.2.2 Immunoassay Analysers (ELISA/CLIA)
- 5.1.2.3 Point-of-Care Molecular Devices
- 5.1.3 Software & Services
- 5.1.1 Reagents & Kits
- 5.2 By Technology
- 5.2.1 Nucleic Acid Amplification Test (NAT)
- 5.2.1.1 TMA
- 5.2.1.2 Real-time PCR
- 5.2.2 Immunoassay
- 5.2.2.1 ELISA
- 5.2.2.2 CLIA / EIA
- 5.2.3 Rapid Tests (Lateral-flow)
- 5.2.4 Next-Generation Sequencing (NGS)
- 5.2.5 Western Blotting
- 5.2.6 Emerging Point-of-Care Molecular Tests
- 5.2.1 Nucleic Acid Amplification Test (NAT)
- 5.3 By Screening Target
- 5.3.1 Infectious Disease Panels
- 5.3.1.1 HIV
- 5.3.1.2 HBV
- 5.3.1.3 HCV
- 5.3.1.4 Emerging Pathogens (Zika, WNV, Dengue)
- 5.3.2 Blood Group Typing
- 5.3.3 Rare Antigen Genotyping
- 5.3.1 Infectious Disease Panels
- 5.4 By End-User
- 5.4.1 Blood Banks
- 5.4.2 Hospitals
- 5.4.3 Clinical Laboratories
- 5.4.4 Plasma Fractionation Centres
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 F. Hoffmann-La Roche Ltd.
- 6.3.2 Grifols S.A.
- 6.3.3 Abbott Laboratories Inc.
- 6.3.4 bioMerieux SA
- 6.3.5 Bio-Rad Laboratories Inc.
- 6.3.6 Becton, Dickinson and Company
- 6.3.7 Danaher Corporation (Beckman Coulter)
- 6.3.8 DiaSorin S.p.A.
- 6.3.9 Siemens Healthineers
- 6.3.10 Thermo Fisher Scientific Inc.
- 6.3.11 Ortho Clinical Diagnostics
- 6.3.12 Revvity
- 6.3.13 Hologic Inc.
- 6.3.14 Qiagen N.V.
- 6.3.15 Illumina Inc.
- 6.3.16 GRAIL, Inc
- 6.3.17 Immucor Inc.
- 6.3.18 Meril Life Sciences
- 6.3.19 Shenzhen Mindray Bio-Medical Electronics
- 6.3.20 Sysmex Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment