|
시장보고서
상품코드
2117273
소프트웨어 컨설팅 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Software Consulting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
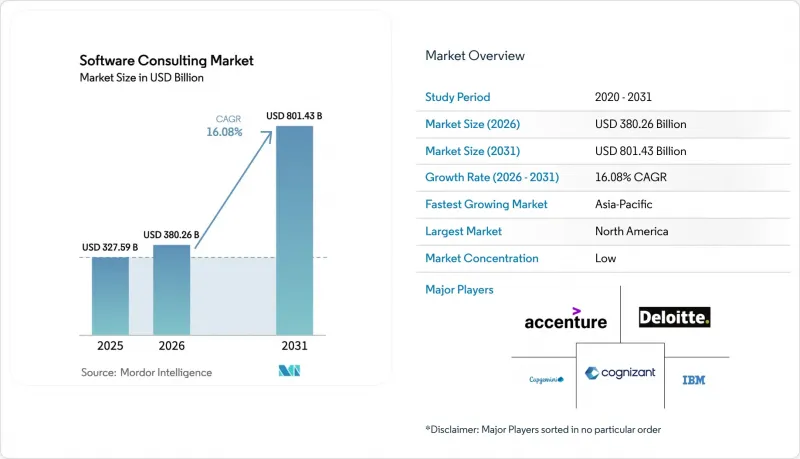
에 따르면 소프트웨어 컨설팅 시장 규모는 2025년에 3,275억 9,000만 달러로 평가되며, 2026년 3,802억 6,000만 달러에서 2031년까지 8,014억 3,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 16.08%가 될 전망입니다.
본 보고서는 서비스 유형(애플리케이션 개발·현대화, 엔터프라이즈 솔루션 통합 등), 도입 모델(클라우드, 온프레미스), 최종사용자의 기업 규모(대기업, 중소기업(SME)), 최종사용자의 업종(BFSI, 통신·미디어 등), 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계 소프트웨어 컨설팅 시장의 동향 및 인사이트
기업의 클라우드 전환 가속화
클라우드 전환은 디지털 전략의 기반이 되고 있습니다. 기업들은 분산된 직원과 실시간 분석을 지원하기 위해 미션 크리티컬 워크로드를 퍼블릭 클라우드 및 하이브리드 클라우드로 전환하고 있습니다. 2024년 유럽의 소프트웨어 지출은 5.1% 증가했으며, 독일, 프랑스, 영국에서 기성 AI 소프트웨어에 대한 투자는 매년 21% 증가하고 있습니다. 북유럽 국가들의 소프트웨어 매출은 440억 달러를 기록하며 연간 16%의 성장률을 보이고 있어, 클라우드 퍼스트 전략이 수출 경쟁력의 기반이 되고 있음을 여실히 보여주고 있습니다. 85%의 조직이 클라우드 퍼스트 개발을 채택하고 있는 만큼, 전 세계 클라우드 지출은 6,754억 달러를 넘어설 전망입니다. 이러한 복잡한 전환 과정에는 멀티 클라우드 아키텍처, 데이터 주권 설계, 워크로드 리팩토링에 정통한 컨설턴트가 필요하지만, 사내 팀은 이러한 분야에 대한 전문 지식이 부족한 경우가 많습니다.
포스트 코로나 시대의 디지털 전환 필요성
팬데믹 이후의 우선 과제로 인해 디지털 전환은 생존을 위한 필수 요건으로 재정의되었습니다. 조사에 따르면, 컨설팅 고객사의 87%가 지난 3년 동안 전사적 프로그램을 시작했으며, 92%는 그 실행을 외부 파트너에 의존했습니다. 2025년 기술 컨설팅 지출은 4,000억 달러를 넘어설 것이며, 그 절반 이상이 도입 서비스에 할당될 것입니다. 특히 공공 부문 기관들은 활발히 움직이고 있으며, 영국의 의사결정권자 중 이전의 노력을 성공으로 평가한 비율은 17%에 불과했고, 63%는 제3자 지원에 대한 예산 증액을 예상하고 있습니다. 디지털 역량이 단순한 효율화 수단에서 경쟁력의 기반으로 전환됨에 따라, 이러한 추세가 전 산업에 걸친 수요를 뒷받침하고 있습니다.
증가하는 사이버 보안 및 데이터 개인정보 보호에 대한 우려
사이버 위험은 방어 체계를 구축하는 속도보다 더 빠르게 확대되고 있습니다. 기업의 4분의 3이 보안 예산을 증액했으나, 인력 부족으로 인해 프로젝트 일정이 장기화되면서 실행이 지연되고 있습니다. 미국에서는 22만 5,000명의 사이버 보안 전문가가 추가로 필요한 반면, 유럽에서는 EU AI법 및 데이터법 등 중복되는 규제 요건에 직면해 있습니다. 컨설턴트가 비즈니스 목표와 병행하여 ‘프라이버시 바이 디자인(Privacy by Design)’ 요건을 충족해야 하기 때문에 이러한 프레임워크는 도입 일정을 장기화시키고 아웃소싱 비용을 상승시키고 있습니다. 이러한 딜레마는 보안 컨설팅 수요를 촉진하는 한편, 전반적인 서비스 제공 속도를 제약하는 요인이 되고 있습니다.
부문 분석
애플리케이션 개발 및 현대화는 2025년 소프트웨어 컨설팅 시장 점유율의 37.72%를 차지했습니다. 이는 레거시 애플리케이션을 클라우드 네이티브 및 API 중심의 스택으로 재구축해야 하는 시급성을 반영합니다. 기업들은 지속적인 배포 구현, 시스템 복원력 향상, 그리고 소유 비용 절감을 위해 이러한 서비스에 의존하고 있습니다. 이 부문은 모든 산업에 걸친 옴니채널 및 실시간 사용 사례를 지원하는 대규모 리팩토링 및 컨테이너화 프로젝트를 기반으로 계속 성장하고 있습니다.
데이터 및 AI/ML 컨설팅은 2031년까지 17.02%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 고객들은 머신러닝 모델, 예측 분석, 생성형 AI 프레임워크를 단순한 효율화 수단이 아닌 차별화 요인으로 인식하고 있습니다. 자문 서비스의 범위는 알고리즘 선정에서 데이터 패브릭 설계, 윤리적 가드레일, 가치 추적 대시보드까지 확대되고 있습니다. 모델 리스크가 규제 당국의 감시 대상이 됨에 따라, 수요는 설명 가능성 평가 및 엔드투엔드 AI 파이프라인에 통합된 거버넌스 프로토콜로 이동하고 있습니다.
2025년, 온프레미스형은 소프트웨어 컨설팅 시장 규모의 53.88% 점유율을 유지했습니다. 이는 신규 도입(그린필드) 및 현대화 프로그램 양쪽 모두에서 매력적인 확장성과 종량제 요금제의 경제성에 힘입은 결과입니다. 현재 제공되는 서비스는 플랫폼 리팩토링, DevSecOps 자동화, 그리고 기업의 증가하는 이용 비용을 억제하는 클라우드 FinOps 자문까지 확대되고 있습니다.
또한, 클라우드 아키텍처는 19.12%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 고객들은 데이터 주권 확보 및 벤더 리스크 완화를 위해 워크로드의 이식성을 중시하고 있습니다. 컨설팅 수요는 클라우드 센터 오브 엑설런스(Cloud Center of Excellence) 설계, 통합된 가시성 스택, 그리고 온프레미스,엣지, 퍼블릭 클라우드의 각 노드 간 보안 연결에 집중되고 있습니다. 기업 데이터의 75%가 소스에 가까운 곳에서 처리되게 되면서 엣지 컴퓨팅은 복잡성이 증가하고 있으며, 분산형 데이터 거버넌스에 정통한 아키텍트에게 새로운 기회가 열리고 있습니다.
지역별 분석
북미는 견조한 기업 IT 예산과 기술 벤더 및 하이퍼스케일 클라우드로 구성된 밀집된 생태계의 뒷받침을 받아, 2025년에는 27.55%의 시장 점유율로 선두를 유지했습니다. 미국의 컨설팅 지출은 연간 4,000억 달러에 육박하고 있으며, 고급 분석에 대한 지출은 2025년에 11% 증가할 것으로 예상됩니다. 캐나다는 공공 부문의 현대화 및 에너지 부문의 디지털화 프로젝트를 통해 상당한 성장에 기여하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR) 18.02%를 기록하며 확장되고 있습니다. 인도의 기술 지출은 정부의 디지털화 이니셔티브와 제조업 현대화에 힘입어 2025년에는 590억 달러에 달할 전망입니다. 중국의 기업들은 AI를 활용한 공급망 및 스마트 팩토리에 막대한 투자를 하고 있는 반면, 동남아시아 국가 정부들은 외부 자문 역량이 필요한 전자 서비스 및 사이버 보안 체계를 확충하고 있습니다. 일본과 한국은 첨단 제조업 및 5G를 활용한 애플리케이션을 통해 성장 모멘텀을 유지하고 있습니다.
유럽에서는 지역 전체 소프트웨어 시장 규모의 약 4분의 1을 차지하는 독일을 중심으로 꾸준한 확대세가 나타나고 있습니다. 중소기업은 세계 경쟁력을 높이기 위해 ERP 및 고객 경험 플랫폼의 업그레이드를 추진하고 있습니다. EU의 AI 법에는 엄격한 거버넌스 의무가 도입되어 있어, 규정 준수 평가 및 감사에 대응 가능한 AI 아키텍처에 대한 컨설팅 수요가 증가하고 있습니다. 북유럽 국가들은 수출 지향형 소프트웨어 생태계와 ‘클라우드 퍼스트’ 정책의 조기 도입을 통해 여전히 큰 영향력을 유지하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.26According to Mordor Intelligence, the software consulting market size was valued at USD 327.59 billion in 2025 and estimated to grow from USD 380.26 billion in 2026 to reach USD 801.43 billion by 2031, at a CAGR of 16.08% during the forecast period (2026-2031).
This report is Segmented by Service Type (Application Development and Modernization and Enterprise Solution Integration and More), Deployment Model (Cloud and On-Premise), End-User Enterprise Size (Large Enterprises and Small and Medium Enterprises (SMEs)), End-User Vertical (BFSI, Telecom and Media and More) and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Software Consulting Market Trends and Insights
Enterprise Cloud-Migration Acceleration
Cloud migration has become foundational for digital agendas. Enterprises are shifting mission-critical workloads to public and hybrid clouds to support distributed workforces and real-time analytics. European software spending climbed 5.1% in 2024, and off-the-shelf AI software investments in Germany, France, and the United Kingdom are rising 21% each year. Nordic economies recorded USD 44 billion in software revenues with 16% annual growth, underscoring how cloud-first strategies underpin export competitiveness. With 85% of organizations adopting cloud-first development, global cloud outlays are set to surpass USD 675.4 billion. These complex transitions require consultants skilled in multi-cloud architecture, data-sovereignty design, and workload refactoring, areas where in-house teams often lack depth.
Digital-Transformation Mandates Post-COVID
Post-pandemic priorities have reframed digital transformation as a survival requirement. Surveys show 87% of consulting clients launched enterprise-wide programs in the last three years and 92% relied on external partners for execution. Technology consulting spend exceeds USD 400 billion in 2025, with implementation services representing more than half. Public-sector agencies are especially active; only 17% of UK decision makers deemed earlier initiatives successful, and 63% expect higher budgets for third-party support. This momentum sustains demand across all industries as digital capabilities shift from optional efficiency plays to the baseline for competitiveness.
Heightened Cybersecurity and Data-Privacy Concerns
Cyber risk escalates faster than defensive postures. Three-quarters of enterprises raised security budgets, yet execution lags as talent shortages stretch project timelines. The United States needs 225,000 additional cybersecurity professionals, while Europe faces overlapping mandates such as the EU AI Act and Data Act. These frameworks lengthen deployment schedules and inflate engagement costs as consultants navigate privacy-by-design requirements alongside business goals. The dilemma both fuels security consulting demand and constrains overall delivery velocity.
Other drivers and restraints analyzed in the detailed report include:
- Growing Data-Analytics and AI Adoption
- Looming SAP ECC Sunset Fuelling S/4HANA Consulting Demand
- Talent Shortage and Rising Consulting Rates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Application development and modernization retained 37.72% software consulting market share in 2025, reflecting the urgency to re-platform legacy applications on cloud-native, API-centric stacks. Enterprises depend on these services to unlock continuous deployment, improve system resilience, and reduce ownership costs. The segment remains anchored in large-scale refactoring and containerization projects that support omnichannel and real-time use cases across verticals.
Data and AI/ML consulting posts the fastest 17.02% CAGR toward 2031. Clients view machine learning models, predictive analytics, and generative AI frameworks as differentiators rather than efficiency levers. Advisory scope is expanding from algorithm selection to data-fabric design, ethical guardrails, and value-tracking dashboards. As model risks attract regulatory scrutiny, demand is shifting toward explainability assessments and governance protocols embedded into end-to-end AI pipelines.
On Premises retained 53.88% share of the software consulting market size in 2025, propelled by scalability and pay-as-you-go economics that appeal to both greenfield and modernization programs. Offerings now span platform refactoring, DevSecOps automation, and cloud FinOps advisory that helps enterprises rein in rising consumption costs.
Also the cloud architectures record the highest 19.12% CAGR. Clients favor workload portability for data sovereignty and vendor risk mitigation. Consulting demand concentrates on cloud center-of-excellence design, unified observability stacks, and secure connectivity between on-premise, edge, and public cloud nodes. Edge computing adds complexity as 75% of enterprise data is processed closer to its source, generating new opportunities for architects versed in distributed data governance.
Complete Report Scope:
- By Service Type
- Application development and modernisation
- Enterprise solution integration
- Cloud migration and managed services
- Software security consulting
- Data and AI/ML consulting
- Others
- By Deployment Model
- On-premise
- Cloud
- By End-user Enterprise Size
- Large enterprises
- Small and medium enterprises (SMEs)
- By End-user Industry
- BFSI
- Healthcare and life-sciences
- Manufacturing and industrial
- Retail and e-commerce
- Government and public sector
- Telecom and media
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Spain
- Switzerland
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Singapore
- Vietnam
- Indonesia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- Nigeria
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led with 27.55% market share in 2025, backed by strong enterprise IT budgets and a dense ecosystem of technology vendors and hyperscale clouds. US consulting expenditure approaches USD 400 billion annually, with advanced analytics outlays expected to rise 11% in 2025. Canada contributes meaningful growth through public-sector modernization and energy-sector digitization projects.
Asia-Pacific is the fastest-growing region, advancing at an 18.02% CAGR. India's technology spending will reach USD 59 billion in 2025, driven by government digital initiatives and manufacturing modernization. China's enterprises invest heavily in AI-enabled supply chains and smart factories, while Southeast Asian governments ramp up e-services and cybersecurity frameworks that require external advisory capabilities. Japan and South Korea sustain momentum through advanced manufacturing and 5G-driven applications.
Europe demonstrates steady expansion anchored by Germany, which holds roughly one-quarter of regional software value. SMEs are upgrading ERP and customer-experience platforms to compete globally. The EU AI Act introduces stringent governance obligations, boosting consulting demand for compliance assessments and audit-ready AI architectures. Nordic countries maintain outsized influence thanks to export-oriented software ecosystems and early adoption of cloud-first policies.
- Accenture
- IBM
- Capgemini
- Cognizant
- Deloitte
- Infosys
- Tata Consultancy Services (TCS)
- Wipro
- HCLTech
- CGI
- Atos SE
- SAP Services
- Oracle Consulting
- EPAM Systems
- ThoughtWorks
- Booz Allen Hamilton
- NTT DATA
- DXC Technology
- Slalom
- Persistent Systems
- Globant
- KPMG
- PwC
- EY
- Bain and Co. (Digital practice)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Enterprise cloud-migration acceleration
- 4.2.2 Digital-transformation mandates post-COVID
- 4.2.3 Need for operational efficiency and cost optimisation
- 4.2.4 Growing data-analytics and AI adoption
- 4.2.5 Looming SAP ECC sunset fuelling S/4HANA consulting demand
- 4.2.6 Emerging AI-governance and compliance mandates
- 4.3 Market Restraints
- 4.3.1 Heightened cybersecurity and data-privacy concerns
- 4.3.2 Talent shortage and rising consulting rates
- 4.3.3 Rapid low-code / no-code adoption reducing custom dev work
- 4.3.4 Gen-AI automating basic advisory tasks, eroding billable hours
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Application development and modernisation
- 5.1.2 Enterprise solution integration
- 5.1.3 Cloud migration and managed services
- 5.1.4 Software security consulting
- 5.1.5 Data and AI/ML consulting
- 5.1.6 Others
- 5.2 By Deployment Model
- 5.2.1 On-premise
- 5.2.2 Cloud
- 5.3 By End-user Enterprise Size
- 5.3.1 Large enterprises
- 5.3.2 Small and medium enterprises (SMEs)
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 Healthcare and life-sciences
- 5.4.3 Manufacturing and industrial
- 5.4.4 Retail and e-commerce
- 5.4.5 Government and public sector
- 5.4.6 Telecom and media
- 5.4.7 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Spain
- 5.5.3.7 Switzerland
- 5.5.3.8 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Malaysia
- 5.5.4.6 Singapore
- 5.5.4.7 Vietnam
- 5.5.4.8 Indonesia
- 5.5.4.9 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 Nigeria
- 5.5.5.2.2 South Africa
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture
- 6.4.2 IBM
- 6.4.3 Capgemini
- 6.4.4 Cognizant
- 6.4.5 Deloitte
- 6.4.6 Infosys
- 6.4.7 Tata Consultancy Services (TCS)
- 6.4.8 Wipro
- 6.4.9 HCLTech
- 6.4.10 CGI
- 6.4.11 Atos SE
- 6.4.12 SAP Services
- 6.4.13 Oracle Consulting
- 6.4.14 EPAM Systems
- 6.4.15 ThoughtWorks
- 6.4.16 Booz Allen Hamilton
- 6.4.17 NTT DATA
- 6.4.18 DXC Technology
- 6.4.19 Slalom
- 6.4.20 Persistent Systems
- 6.4.21 Globant
- 6.4.22 KPMG
- 6.4.23 PwC
- 6.4.24 EY
- 6.4.25 Bain and Co. (Digital practice)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment