

|
시장보고서
상품코드
2117285
수혈 진단 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Blood Transfusion Diagnostics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 수혈 진단 시장 규모는 64억 1,000만 달러로 추정되고, 2025년 59억 7,000만 달러에서 확대해, 2031년에는 91억 4,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 7.34%로 성장할 것으로 전망됩니다.
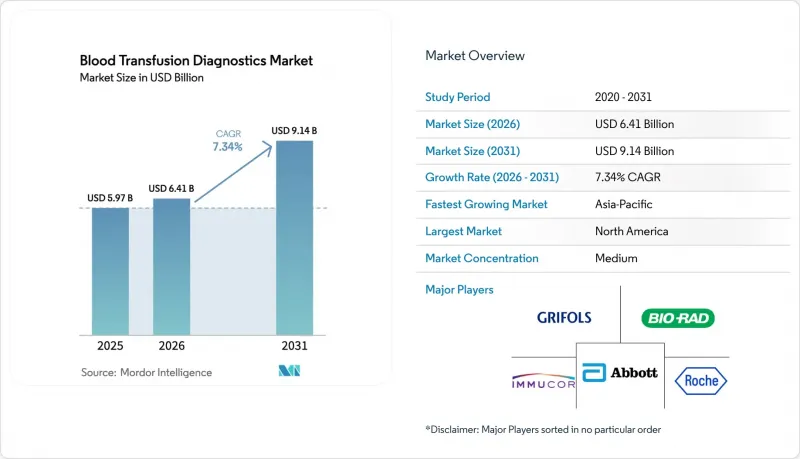
본 보고서는 제품 유형별(장비, 소모품), 기술별(혈청학, 핵산 검사, 기타), 용도별(질병 선별 검사, 혈액형 판정), 최종 사용자별(병원, 진단 실험실, 기타), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 수혈 진단 시장 동향 및 인사이트
전 세계 헌혈 및 수혈 수요 증가
자발적인 헌혈 캠페인과 혈액 감시 프로그램이 수혈 진단 시장의 꾸준한 성장을 뒷받침하고 있습니다. 중국의 국가위생건강위원회는 단체 헌혈을 확대하기 위해 청년 단체와 제휴하고 있는 반면, 인도의 혈액 감시 프로그램은 유해 사건 보고 체계를 개선하기 위해 1만 5,000명 이상의 임상의사를 교육하고 있습니다. 미국에서는 애보트 래버러토리즈가 후원하는 대학 대항 경연을 통해 일반 시민의 인식이 높아지고 있으며, 세라스 코퍼레이션의 병원체 제거 키트 ‘INTERCEPT’가 혈소판과 혈장 성분의 안전성을 보장하고 있습니다. 유럽에서는 수입 의존도를 낮추기 위해 200만 명의 헌혈자를 추가로 모집하고 있으며, 이는 전 세계적인 혈액 공급 문제를 여실히 드러내고 있습니다.
외상 및 외과 수술 발생 건수 증가
수혈 진단 시장은 외상 치료의 복잡화와 외과 수술 건수 증가의 혜택을 받고 있습니다. 2025년 메디케어 의사 보수 일정표에서는 병원 도착 전 수혈이 고도 응급처치로 인정되어, 혈액을 비축하는 구급차 사업자에 대한 보수가 인상되었습니다. 중서부의 한 대규모 학술 의료 센터에서는 2024년에 323건의 대량 수혈 대응이 이루어져 전년 대비 7% 증가했습니다. 현재, 현장 진단(POC) 응고 분석 장비가 수술 중 판단을 지원하고 있으며, 머신러닝을 활용한 대시보드가 재고 급증을 예측함으로써 낭비를 줄이고 있습니다.
고급 진단 기기의 높은 비용
고속 처리 분석 장치의 높은 가격은 자원이 제한된 환경에서의 도입을 방해하고 있으며, 수혈 진단 시장의 추가적인 확산을 저해하고 있습니다. 일상적인 검사의 보험 급여액은 계속 감소하고 있어, 검사실은 분자 검사에 대한 투자를 타 부서의 보전에 의존할 수밖에 없는 상황입니다. FDA의 추정에 따르면, 검사실 개발 검사(LDT)가 의료기기로서의 완전한 규제 대상로 전환됨에 따라 연간 규정 준수 비용은 최대 35억 6,000만 달러에 달할 것으로 예측됩니다. 병원의 외래 진료 부서는 독립 검사 기관에 비해 동일한 검사에 대해 여전히 3배의 요금을 청구하고 있어, 조달 측면에서의 불균형이 두드러지고 있습니다.
부문 분석
2025년 수혈 진단 시장에서 소모품은 시장의 53.62%를 차지했습니다. 시약, 교정제, 품질 관리용 재료에 대한 지속적인 수요는 특히 검사 항목에 말라리아, 바베시아, 지카 바이러스 선별 검사가 추가됨에 따라 안정적인 현금 흐름을 가져오고 있습니다. 통합형 카트리지 설계로 피펫팅 오류를 최소화하면서 작업 시간을 단축하고 있습니다.
기기 부문은 2031년까지 연평균 성장률(CAGR) 8.95%로 확대될 것으로 예측됩니다. 새로운 원심분리기 및 리더 플랫폼에 탑재된 AI 강화 비전 시스템 덕분에 시간당 400개 이상의 검체를 처리할 수 있게 되었습니다. Siemens Healthineers와 시스멕스 간공급 계약과 같은 제휴는 각 제조업체가 단일 미들웨어 생태계 내에서 지혈, 면역혈액학, NAT 모듈을 어떻게 통합하고 있는지를 보여줍니다. 리스 모델 및 시약 대여 계약을 통해 초기 투자 장벽이 낮아짐에 따라, 새로운 장비 도입에 따른 수혈 진단 시장 규모는 확대될 전망입니다.
2025년에는 기존 분석 장비에 적합한 비용 효율적인 효소면역법 및 화학발광법 분석을 활용하여, 혈청학 검사가 매출의 45.12%를 계속 차지했습니다. 시약의 개선을 통해 위양성이 감소하고, 헌혈 처리 능력이 유지되고 있습니다.
핵산 검사(NAT)는 연평균 성장률(CAGR) 8.63%로 가장 높은 성장률을 보이며, 진단 기간을 단축하고 혈액의 안전성을 향상시키고 있습니다. 로슈(Roche)의 cobas 시스템은 현재 연간 수천만 건의 헌혈에 대해 HIV, HBV, HCV, 말라리아 스크리닝을 수행하고 있습니다. 규제 당국이 추가 병원체에 대한 다중 선별 검사를 의무화하고, 풀 검사 프로토콜을 통해 헌혈자 1인당 비용이 절감됨에 따라, NAT 플랫폼과 관련된 수혈 진단 시장 점유율은 더욱 확대될 전망입니다.
지역별 분석
2025년, 북미는 전 세계 매출의 39.12%를 차지했습니다. 의료기기 규제에 관한 FDA의 지침과 메디케어의 병원 도착 전 수혈 중시 정책이 고감도 검사법에 대한 수요를 뒷받침하고 있습니다. 벡톤 디킨슨(Becton Dickinson)사의 1,000만 달러 규모의 국내 사업 확장은 공급망 단축을 위한 노력을 뒷받침하고 있습니다. 병원 외래 진료부가 독립 검사 기관보다 3배나 높은 요금을 청구하는 등 뿌리 깊은 가격 격차가 구매 전략을 좌우하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 8.31%를 나타낼 것으로 예측되며, 이는 전 세계에서 가장 높은 수준입니다. 중국의 ‘건강 중국 2030’ 계획은 현대적인 채혈 센터에 자금을 지원하며, 테르모 BCT의 1,500만 달러 규모 현지화 투자를 뒷받침하고 있습니다. 인도의 전국적인 혈액 모니터링 프로그램은 임상의의 역량 강화에 기여하고 있는 반면, 동남아시아 국가들에서는 클라우드 기반 헌혈자 등록 시스템의 시범 운영이 진행되고 있습니다. 불균형한 환급 제도와 단절된 공급망은 여전히 장벽으로 작용하고 있지만, 도시 지역의 병원에서는 NAT 및 자동화 플랫폼 도입이 진행되고 있습니다.
유럽은 고유한 공급 및 규제 측면의 과제에 직면하고 있음에도 불구하고 여전히 중요한 위치를 유지하고 있습니다. 이 지역에서는 수입 혈장에 대한 의존도를 낮추기 위해 추가로 200만 명의 헌혈자가 필요한 것으로 추정되며, 이러한 부족분이 헌혈자 모집 분석에 대한 수요를 부추기고 있습니다. ‘인체 유래 물질에 관한 규정’의 시행으로 2027년까지 감독 체계의 조화가 이루어지겠지만, 검사 기관은 ‘체외 진단용 의료기기 규정’에 따른 더 엄격한 증거 요건으로 인해 발생한 격차를 메워야 합니다. 수혈 진단 시장은 자급자족 달성을 목표로 하는 공공 부문의 자금 지원으로 인해 계속해서 혜택을 받고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, blood transfusion diagnostics market size in 2026 is estimated at USD 6.41 billion, growing from 2025 value of USD 5.97 billion with 2031 projections showing USD 9.14 billion, growing at 7.34% CAGR over 2026-2031.
This report is Segmented by Product Type (Instruments and Consumables), Technology (Serology, Nucleic Acid Tests, and More), Application (Disease Screening and Blood Group Typing), End-User (Hospitals, Diagnostic Laboratories, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Blood Transfusion Diagnostics Market Trends and Insights
Rising Global Blood Donations and Transfusion Demand
Voluntary donor drives and hemovigilance programs stimulate steady growth for the blood transfusion diagnostics market. China's National Health Commission partners with youth organizations to broaden group donations, while India's Hemovigilance Program trains more than 15,000 clinicians to improve adverse-event reporting. In the United States, college competitions supported by Abbott Laboratories raise public awareness, and Cerus Corporation's INTERCEPT pathogen-reduction kits safeguard platelet and plasma components. Europe continues to call for 2 million extra donors to lessen import dependence, underscoring global supply challenges.
Growing Incidence of Trauma and Surgical Procedures
The blood transfusion diagnostics market benefits from rising trauma care complexity and higher surgical case loads. The 2025 Medicare Physician Fee Schedule recognizes pre-hospital transfusion as advanced life support, increasing reimbursement for ambulance providers that stock blood. A large Midwest academic center reported 323 massive transfusion activations in 2024, a 7% increase year on year. Point-of-care coagulation analyzers now guide intraoperative decisions, and machine-learning dashboards predict inventory surges, cutting wastage.
High Cost of Advanced Diagnostic Instruments
Price tags on high-throughput analyzers restrain adoption in resource-constrained settings, challenging broader penetration of the blood transfusion diagnostics market. Routine assay reimbursements continue to drop, forcing laboratories to cross-subsidize molecular test investments. The FDA estimates annual compliance costs up to USD 3.56 billion as laboratory-developed tests transition to full device oversight. Hospital outpatient departments still bill three times more for identical tests than independent labs, underscoring procurement asymmetries.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advancements in Transfusion Diagnostics
- Integration of Point-of-Care Testing in Blood Banks
- Stringent Regulatory Approval Processes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables generated 53.62% of the 2025 blood transfusion diagnostics market. Continuous demand for reagents, calibrators, and quality-control materials provides steady cash flows, especially as test menus now include malaria, Babesia, and Zika screening. Integrated cartridge designs minimize pipetting errors while lowering hands-on time.
The instrument segment is expected to advance at a 8.95% CAGR through 2031. AI-enhanced vision systems within new centrifuge and reader platforms drive throughputs exceeding 400 samples per hour. Partnerships such as the Siemens Healthineers-Sysmex supply deal illustrate how manufacturers combine hemostasis, immunohematology, and NAT modules within single middleware ecosystems. The blood transfusion diagnostics market size attributable to new instrument placements is set to widen as leasing models and reagent-rent contracts lower upfront capital barriers.
Serology retained 45.12% of revenue in 2025, capitalizing on cost-efficient enzyme-linked and chemiluminescent assays that fit legacy analyzers. Reagent refinements cut false positives, preserving donation throughput.
Nucleic acid testing exhibits the highest growth at 8.63% CAGR, narrowing diagnostic windows and improving blood safety. Roche's cobas systems now screen tens of millions of donations annually for HIV, HBV, HCV, and malaria. The blood transfusion diagnostics market share associated with NAT platforms will expand further as regulators mandate multiplex screening for additional pathogens and as pooling protocols moderate per-donor costs.
Complete Report Scope:
- By Product Type
- Instruments
- Consumables (Reagents, Kits, Calibrators, Controls)
- By Technology
- Serology (ELISA, CLIA, Agglutination)
- Nucleic Acid Tests (PCR, TMA, NAT)
- Microarray & Next-Generation Sequencing
- Rapid / Lateral Flow Assays
- By Application
- Disease Screening (TTIs, Emerging Pathogens)
- Blood Group Typing (ABO/Rh, Extended Antigen)
- By End-User
- Hospitals
- Diagnostic Laboratories
- Blood Banks
- Plasma Fractionation Centers
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 39.12% of global revenue in 2025. FDA guidance on device regulation and Medicare's elevation of pre-hospital transfusion drive demand for high-sensitivity assays. Becton Dickinson's USD 10 million domestic expansion underscores efforts to shorten supply chains. Persistent price gaps-hospital outpatient departments bill three times what independent labs charge-shape purchasing strategies.
Asia-Pacific is forecast to rise at an 8.31% CAGR, the strongest worldwide. China's Healthy China 2030 plan funds modern blood-collection centers and supports Terumo BCT's USD 15 million localization investment. India's nationwide hemovigilance program lifts clinician competence, while Southeast Asian countries pilot cloud-based donor registries. Heterogeneous reimbursement and fragmented supply chains remain barriers, yet urban hospitals continue to adopt NAT and automation platforms.
Europe retains a substantial position amid unique supply and regulatory challenges. The region needs 2 million additional donors to cut reliance on imported plasma, a gap that primes demand for donor-recruitment analytics. Implementation of the Regulation on Substances of Human Origin will harmonize oversight by 2027, but labs must bridge gaps created by the In Vitro Diagnostic Regulation's stricter evidence requirements. The blood transfusion diagnostics market continues to benefit from public-sector funding aimed at achieving self-sufficiency.
- Grifols
- Roche
- Abbott Laboratories
- Bio-Rad Laboratories
- Immucor
- Danaher (Beckman Coulter & Cepheid)
- Siemens Healthineers
- DiaSorin
- Werfen (Instrumentation Laboratory)
- Merck KGaA (MilliporeSigma)
- Sysmex Corp.
- QuidelOrtho Corp.
- Fresenius
- Haemonetics Corp.
- Beckton Dickinson
- Thermo Fisher Scientific
- Terumo Corp.
- Trinity Biotech
- bioMerieux
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Blood Donations And Transfusion Demand
- 4.2.2 Growing Incidence of Trauma And Surgical Procedures
- 4.2.3 Technological Advancements in Transfusion Diagnostics
- 4.2.4 Integration of Point-of-Care Testing in Blood Banks
- 4.2.5 Expansion of Healthcare Infrastructure in Emerging Markets
- 4.2.6 Adoption of Cloud-Based Blood Bank Information Systems
- 4.3 Market Restraints
- 4.3.1 High Cost if Advanced Diagnostic Instruments
- 4.3.2 Stringent Regulatory Approval Processes
- 4.3.3 Limited Availability if Rare Blood Reagents
- 4.3.4 Fragmented Donor Traceability Systems
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitutes
- 4.5.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Instruments
- 5.1.2 Consumables (Reagents, Kits, Calibrators, Controls)
- 5.2 By Technology
- 5.2.1 Serology (ELISA, CLIA, Agglutination)
- 5.2.2 Nucleic Acid Tests (PCR, TMA, NAT)
- 5.2.3 Microarray & Next-Generation Sequencing
- 5.2.4 Rapid / Lateral Flow Assays
- 5.3 By Application
- 5.3.1 Disease Screening (TTIs, Emerging Pathogens)
- 5.3.2 Blood Group Typing (ABO/Rh, Extended Antigen)
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Diagnostic Laboratories
- 5.4.3 Blood Banks
- 5.4.4 Plasma Fractionation Centers
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Grifols S.A.
- 6.3.2 Roche Diagnostics
- 6.3.3 Abbott Laboratories
- 6.3.4 Bio-Rad Laboratories Inc.
- 6.3.5 Immucor Inc.
- 6.3.6 Danaher (Beckman Coulter & Cepheid)
- 6.3.7 Siemens Healthineers
- 6.3.8 DiaSorin S.p.A.
- 6.3.9 Werfen (Instrumentation Laboratory)
- 6.3.10 Merck KGaA (MilliporeSigma)
- 6.3.11 Sysmex Corp.
- 6.3.12 QuidelOrtho Corp.
- 6.3.13 Fresenius Kabi AG
- 6.3.14 Haemonetics Corp.
- 6.3.15 Becton, Dickinson & Co.
- 6.3.16 Thermo Fisher Scientific
- 6.3.17 Terumo Corp.
- 6.3.18 Trinity Biotech
- 6.3.19 BioMrieux SA
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


