

|
시장보고서
상품코드
2117487
합성 피혁 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Synthetic Leather - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 합성 피혁 시장 규모는 2025년 452억 2,000만 달러, 2026년 488억 4,000만 달러에서 2031년까지 718억 6,000만 달러로 확대된다고 예측되고 있어 2026년부터 2031년까지 CAGR 8.03%를 기록하는 전망입니다.
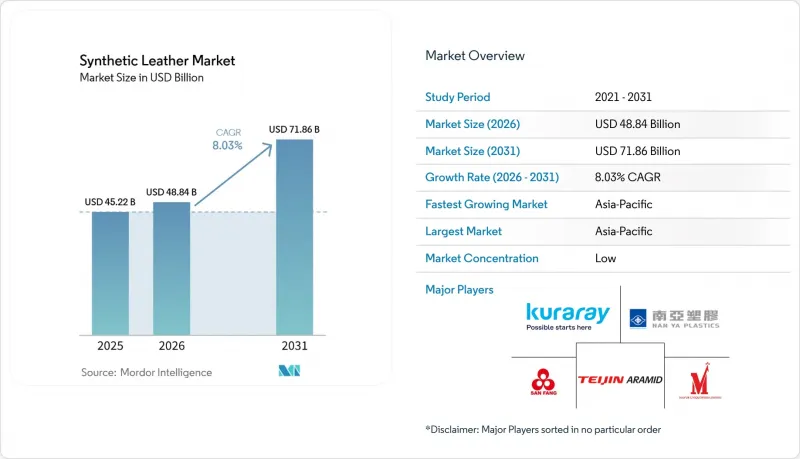
본 보고서는 가죽의 유형(PU 합성 피혁, PVC 합성 피혁 등), 제조 기술(수성 PU 코팅, 무용제 PU 시스템 등), 용도(신발, 자동차 내장재 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 합성 피혁 시장 동향 및 인사이트
PVC를 대체하는 PU: 배합의 경제성이 기재를 변화시킨다.
합성 피혁 시장에서는 PVC에 비해 규정 준수, 외관 품질, 그리고 고급 용도에 대한 적합성의 균형이 뛰어난 PU로의 꾸준한 전환이 나타나고 있습니다. 완제품에 포함된 잔류 디메틸포름아미드의 제한으로 인해, 기존의 용제를 많이 사용하는 생산 라인의 운영 부담이 증가하고 있습니다. 더 엄격한 기준을 충족하기 위해 여러 차례의 온수 세척이 필요할 수 있으며, 이로 인해 공정 비용과 에너지 소비가 모두 증가하기 때문입니다. 이러한 압박은 표면의 질감, 부드러움, 균일성을 희생하지 않으면서 용제 노출을 줄이고자 하는 구매자가 존재하는 대량 생산 공급망에서 특히 두드러집니다. 코팅 능력을 강화한 대규모 가공업체는 개조 비용을 흡수하고 구매자의 인증 요건에 더 신속하게 대응할 수 있으므로, 합성 피혁 시장에서 유리한 입지를 차지하고 있습니다. 그 결과, 기재의 구성 전환이 가속화되고 있으며, 외관, 규정 준수, 내구성이 종합적으로 평가되는 카테고리에서 PU의 입지가 강화되고 있습니다.
비건 소재에 대한 수요: 각 OEM 기업의 노력이 조달 사양으로 구체화되고 있습니다.
합성 피혁 시장은 패션 업계와 자동차 내장재 분야 모두에서 동물 유래 성분을 포함하지 않는 소재로의 광범위한 전환 흐름에 힘입고 있습니다. 메르세데스-벤츠는 주요 접촉 부위에 ARTICO 합성 피혁을 채택한 비건 인증 전기차(EV) 실내 장식을 발표하며, 동물 유래 성분 미사용이 더 이상 단순한 마케팅 용어가 아니라 제품 사양의 일부가 되었음을 보여주었습니다. 또한, 현대 CRADLE도 2025년 8월 UNCAGED Innovations와 제휴하여 자동차용 그레인(표면 무늬) 기반의 가죽 대체 소재를 개발 중이며, 이는 자동차 제조업체들이 표준적인 상업적 공급을 기다리기보다는 업스트림 공정인 소재 개발에 투자하고 있음을 시사합니다. 이러한 변화로 인해 합성 피혁 시장의 품질 요건은 높아지고 있습니다. 생산자는 더욱 엄격한 조달 요건을 충족하고, 추적 가능성이 보장되며, 기술적으로 안정적인 제품을 제공해야 하기 때문입니다. 또한 촉감의 질이나 시각적 일관성을 해치지 않으면서 환경 부하 감소를 목표로 하는 브랜드에게는 프리미엄 가격 책정의 여지도 넓어지고 있습니다.
PFAS, DMF 및 비닐계 화학물질에 관한 규제: 시장을 재편하는 규정 준수 비용
PFAS, DMF 및 비닐계 화합물에 대한 규제 강화는 합성 피혁 시장에 명백한 제약 요인으로 작용하고 있습니다. 이는 규정 준수가 화학 물질 선정과 수출 준비 양쪽 모두에 영향을 미치게 되었기 때문입니다. EU의 퍼플루오로헥산산(PFHxA) 규제는 의류, 액세서리 및 관련 코팅 소재를 포함한 대상 제품 범주에 추가적인 압박을 가하고 있으며, 유럽 시장에서 기존 처리 방법의 적용 범위를 좁히고 있습니다. 또한, 프랑스도 2026년 1월부터 PFAS가 함유된 섬유 제품 및 신발에 대한 규제를 도입함에 따라, 해당 제품 라인을 취급하는 공급업체들 사이에서는 배합 재검토 및 시험 실시가 시급한 과제가 되고 있습니다. 중견 수출업체의 경우, 과제는 화학 물질의 대체에 그치지 않고, 단일 생산 라인이 여러 최종 시장에 공급하는 경우 서류 작성, 로트별 시험, 리콜 방지에 드는 비용도 포함됩니다. 이로 인해 합성 피혁 시장의 일부는 침체되고 있습니다. 소규모 제조업체들은 설비 현대화를 미루거나, 고급 제품 시장에 대한 접근성을 상실하거나, 또는 규정 준수 요건이 비교적 완화된 저사양 용도로 전환할 가능성이 있기 때문입니다.
부문 분석
2025년, PU는 총 수요의 51.36%를 차지하며 합성 피혁 시장에서 다른 가죽 유형에 비해 뚜렷한 우위를 유지했습니다. 이러한 위상은 특히 고급 신발, 가구 커버링, 자동차 내장재 분야에서 PVC보다 더 폭넓은 성능 및 외관 요건을 충족시키는 능력을 반영합니다. 바이오 합성 피혁은 가장 빠르게 성장하는 가죽 유형으로, 2031년까지 연평균 성장률(CAGR) 9.80%로 확대될 것으로 예측됩니다. 이는 완전한 비용 평등이 달성되기 전부터 수요 변화가 일어나고 있음을 나타냅니다. PVC는 대규모 제조거점과 비용 면에서의 우위를 바탕으로, 보급형 신발이나 저가형 가구 등 가격에 민감한 용도에서 여전히 입지를 유지하고 있습니다. 실리콘 및 TPO/TPU 계열 제품은 합성 피혁 시장 내 점유율은 작지만, 가격보다 내열성, 내후성 또는 특수한 표면 성능이 우선시되는 용도에서 주목을 받고 있습니다.
가죽의 유형 구성은 합성 피혁 업계의 기술 개발 진행 상황도 반영하고 있습니다. 『ACS Sustainable Chemistry &Engineering』 저널의 2025년 연구에 따르면,1,4-부탄디올과 아디핀산을 원료로 하는 바이오 폴리(에스테르아미드) 코팅은 구성 성분인 호모폴리머에 비해 8배의 인장 강도를 달성했으며, 퇴비화 조건에서 1개월 이내에 셀룰로오스에 비해 60% 이상의 생분해성을 보였습니다. 이러한 진전은 지속가능성과 실용적인 성능 간의 격차를 좁힘으로써 고품질 바이오 소재의 채택을 촉진하고 있습니다. 따라서 예측 기간 동안 PU가 주도적인 위치를 유지할 것으로 보이지만, 브랜딩, 규정 준수, 공급업체와의 협력이 최저 비용 생산보다 더 중요하게 여겨지는 프로젝트에서는 바이오베이스 등급이 먼저 확대될 것으로 예측됩니다.
지역별 분석
아시아태평양은 2025년에 전 세계 수요의 45.71%를 차지하며, 2031년까지 연평균 성장률(CAGR) 8.81%로 성장하여 합성 피혁 시장에서 가장 크고 가장 빠르게 성장하는 지역이 될 것으로 전망됩니다. 이 지역은 중국의 거대한 가공 거점, 인도의 확대되는 신발 제조거점, 그리고 원자재, 코팅 능력, 수출 채널을 연결하는 긴밀한 공급망의 혜택을 받고 있습니다. 이러한 요인들이 결합되어 아시아태평양은 주류 카테고리에서 규모의 우위를 확보하는 동시에, 더 고품질의 PU 제품 생산으로의 단계적 전환을 뒷받침하고 있습니다. 일본도 프리미엄 부문에서 여전히 중요한 위치를 차지하고 있으며, 도레이, 쿠라레, 아사히카세이 등의 기업들이 자동차 및 패션 용도의 마이크로파이버와 고성능 소재 분야에서 확고한 입지를 다지고 있습니다. 이 지역의 탄탄한 산업 기반을 바탕으로, 합성 피혁 시장 전반에 걸친 수많은 기술 혁신과 비용 측면의 변화는 아시아태평양을 기점으로 시작되어 이후 다른 지역으로 계속해서 확산되고 있습니다.
북미와 유럽은 합성 피혁 시장에서 부가가치가 가장 높은 지역 쌍이며, 그 배경에는 다른 대부분의 지역보다 엄격한 규제 준수 요건과 내장재 품질에 대한 기대가 있습니다. 두 지역 수요는 저배출 및 고성능 제품 사양을 충족하는 프리미엄 수성 및 무용제 PU 등급에 의해 뒷받침되고 있습니다. Vulcaflex S.p.A.는 2026년 6월, 이러한 추세를 반영하여 앨라배마주 오번에 첫 북미 공장을 건설하기 위해 약 7,000만 달러를 투자할 계획을 발표했습니다. 이 공장은 미국, 캐나다, 멕시코 전역의 자동차 업계 고객들에게 제품을 공급하는 것을 목표로 하고 있습니다. 유럽에서는 화학 물질 규제의 강화와 구매자 측의 요구 사항이 엄격해짐에 따라 업그레이드된 PU 시스템에 대한 수요가 계속해서 뒷받침되고 있지만, 총 생산량 증가세는 아시아에 비해 여전히 완만합니다.
남미, 중동 및 아프리카는 합성 피혁 시장에 있어 보다 장기적인 성장 기회를 내포하고 있으며, 그 수요는 신발 생산량, 가구 소비, 그리고 자동차 조립의 단계적 현지화와 연동되어 있습니다. 브라질과 아르헨티나는 여전히 남미의 주요 수요 거점이며, 이 지역의 신발 제조는 경쟁력 있는 가격의 코팅 소재에 있어 중요한 시장을 형성하고 있습니다. 사우디아라비아와 아랍에미리트(UAE)는 호텔·리조트용 가구 및 패션 소매 업계 수요에 힘입어 중동의 주요 소비 거점으로 자리 잡고 있습니다. 이 지역들의 성장률은 가공업체의 인프라가 미비하고 품질 및 지속가능성 기준의 시행이 불균일하기 때문에 여전히 세계 평균보다 낮은 수준입니다. 그 결과, 저비용의 폴리염화비닐(PVC)을 많이 사용한 제품은 유럽이나 북미에 비해 이들 시장에서 더 오랫동안 주류를 유지할 가능성이 높습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.01According to Mordor Intelligence, the synthetic leather market size is projected to expand from USD 45.22 billion in 2025 and USD 48.84 billion in 2026 to USD 71.86 billion by 2031, registering a CAGR of 8.03% between 2026 to 2031.
This report is Segmented by Leather Type (PU Synthetic Leather, PVC Synthetic Leather, and More), Manufacturing Technology (Water-Based PU Coating, Solvent-Free PU Systems, and More), Application (Footwear, Automotive Interiors, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Synthetic Leather Market Trends and Insights
PU Replacing PVC: Formulation Economics Shift the Base Material
The synthetic leather market is seeing a steady shift toward PU, as it offers a more favorable balance of compliance readiness, visual quality, and suitability for premium applications than PVC. Residual dimethylformamide limits in finished articles increase the operating burden on conventional solvent-heavy lines, as multiple hot-water washes may be required to meet stricter thresholds, raising both process costs and energy use. This pressure is most significant in high-volume supply chains where buyers want lower solvent exposure without sacrificing grain finish, softness, or consistency. Larger converters with upgraded coating capacity are better positioned in the synthetic leather market, as they can absorb retrofit costs and respond more quickly to buyer qualification requirements. The result is a faster transition in the base material mix, with PU strengthening its position in categories where appearance, compliance, and durability are evaluated together.
Vegan-Material Demand: OEM Commitments are Hardening into Procurement Specs
The synthetic leather market is gaining support from a broader shift toward animal-free materials in both fashion and vehicle interiors. Mercedes-Benz introduced a vegan-certified electric vehicle interior featuring ARTICO synthetic leather across major touchpoints, demonstrating that animal-free content is now part of product specification rather than marketing language. Hyundai CRADLE also partnered with UNCAGED Innovations in August 2025 to develop grain-based leather alternatives for vehicles, indicating that automakers are investing upstream in material development rather than waiting for standard commercial supply. These changes raise quality requirements in the synthetic leather market, as producers now need to offer traceable, technically stable variants that can meet stricter procurement requirements. This also widens the path for premium pricing where brands want lower environmental impact without compromising tactile quality or visual consistency.
PFAS, DMF, and Vinyl-Based Chemical Regulations: Compliance Cost as a Market Reshaper
Tighter regulations on PFAS, DMF, and vinyl-linked formulations present a clear restraint for the synthetic leather market, as compliance now affects both chemical choices and export readiness. The EU perfluorohexanoic acid (PFHxA) regulation adds pressure on affected product categories, including clothing, accessories, and related coated materials, narrowing the scope for legacy treatments in European channels. France has also introduced restrictions on PFAS-containing textiles and footwear effective January 2026, increasing the urgency for reformulation and testing among suppliers that serve those product lines. For mid-tier exporters, the challenge extends beyond chemical substitution to include the costs of documentation, batch testing, and recall prevention when a single production line serves multiple end markets. This slows parts of the synthetic leather market, as smaller manufacturers may delay upgrades, lose access to premium channels, or shift toward lower-specification applications where compliance requirements are less stringent.
Other drivers and restraints analyzed in the detailed report include:
- Automotive Cabin Premiumization: EV Architecture Redefines the Substrate
- Waterborne and Solvent-Free Technology: The New Production Baseline
- Hydrolysis and Heat-Aging Durability: A Hidden Barrier to Market Expansion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PU accounted for 51.36% of total demand in 2025, maintaining a clear lead over other leather types in the synthetic leather market. This position reflects its ability to meet a wider range of performance and appearance requirements than PVC, particularly in premium footwear, upholstery, and vehicle interiors. Bio-based synthetic leather is the fastest-growing leather type, projected to expand at a 9.80% CAGR through 2031, indicating a demand shift even before full cost parity is achieved. PVC retains a presence in price-sensitive applications such as entry-level footwear and lower-end furnishings, supported by a large installed process base and cost advantages. Silicone and TPO/TPU variants hold smaller shares in the synthetic leather market but are gaining traction in applications where heat stability, weather resistance, or specialized surface performance take priority over price.
The leather type mix also reflects the pace of technical development in the synthetic leather industry. A 2025 study in ACS Sustainable Chemistry & Engineering found that bio-based poly(ester amide) coatings derived from 1,4-butanediol and adipic acid achieved tensile strength 8 times higher than constituent homopolymers and delivered more than 60% biodegradation relative to cellulose under composting conditions within one month. This progress supports the case for premium bio-based materials by narrowing the gap between sustainability and usable performance. PU is therefore likely to retain its lead through the forecast period, while bio-based grades expand first in programs where branding, compliance, and supplier collaboration carry more weight than lowest-cost output.
Complete Report Scope:
- By Leather Type
- PU Synthetic Leather
- PVC Synthetic Leather
- Bio-based Synthetic Leather
- Silicone Synthetic Leather
- TPO/TPU Synthetic Leather
- By Manufacturing Technology
- Solvent-based Coagulation and Coating
- Water-based PU Coating
- Solvent-free PU Systems
- By Application
- Footwear
- Furnishing
- Chairs
- Sofas
- Other Upholstery
- Automotive Interiors
- Seats
- Door Trims and Panels
- Dashboard and Instrument Panel Surfaces
- Steering Wheel and Console Surfaces
- Other Interior Surfaces
- Bags, Wallets and Luggage
- Wallets
- Bags
- Purses
- Clothing and Fashion Accessories
- Jackets
- Belts
- Other Apparel Accessories
- Sports and Leisure Goods
- Marine and Specialty Uses
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 45.71% of global demand in 2025 and is forecast to grow at a 8.81% CAGR through 2031, making it both the largest and fastest-growing region in the synthetic leather market. The region benefits from China's large converting base, India's expanding footwear manufacturing position, and a dense supply chain linking raw materials, coating capacity, and export channels. This combination gives Asia-Pacific a scale advantage in mainstream categories while supporting a gradual shift toward higher-grade PU output. Japan remains relevant in the premium tier, with companies such as Toray Industries, Kuraray, and Asahi Kasei holding established positions in microfiber and high-performance materials for automotive and fashion applications. Given the region's depth, many technology and cost transitions in the broader synthetic leather market continue to originate in Asia-Pacific before spreading to other regions.
North America and Europe represent the highest-value regional pair in the synthetic leather market, driven by regulatory compliance requirements and interior quality expectations that are more stringent than in most other regions. Demand in both regions is supported by premium waterborne and solvent-free PU grades that meet lower-emission and higher-performance product specifications. Vulcaflex S.p.A. reflected this trend in June 2026 with its plan to invest almost USD 70 million in its first North American plant in Auburn, Alabama, to supply automotive customers across the United States, Canada, and Mexico. In Europe, tighter chemical regulations and stricter buyer requirements continue to support demand for upgraded PU systems, even as total volume growth remains slower than in Asia.
South America, the Middle East, and Africa represent a longer-cycle opportunity for the synthetic leather market, with demand tied to footwear output, furnishing consumption, and the gradual localization of automotive assembly. Brazil and Argentina remain the primary South American demand centers, where regional footwear manufacturing creates a meaningful market for coated materials at competitive prices. Saudi Arabia and the UAE serve as the main consumption hubs in the Middle East, supported by demand for hospitality furnishings and fashion retail. Growth across these regions remains below the global average due to less developed converter infrastructure and inconsistent enforcement of quality and sustainability standards. As a result, lower-cost polyvinyl chloride (PVC)-heavy products are likely to remain prevalent in these markets for longer than in Europe or North America.
- Anhui Anli Material Technology Co., Ltd.
- Asahi Kasei Corporation
- Baiksan Co., Ltd.
- BASF SE
- Continental AG
- Covestro AG
- Dow Inc.
- FILWEL Co., Ltd.
- Fujian Polytech Technology Corp., Ltd.
- H.R. Polycoats Pvt. Ltd.
- Jasch Industries Limited
- Kolon Industries, Inc.
- KURARAY CO., LTD.
- Mayur Uniquoters Limited
- NAN YA PLASTICS CORPORATION
- Responsive Industries Limited
- San Fang Chemical Industry Co., Ltd.
- Seiren Co., Ltd.
- TEIJIN LIMITED
- Toray Industries, Inc.
- Wanhua Chemical Group Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 PU replacing PVC and genuine leather in mass-premium uses
- 4.2.2 Vegan-material demand from footwear and fashion brands
- 4.2.3 Automotive cabin premiumization and EV interior demand
- 4.2.4 Waterborne and solvent-free PU commercialization
- 4.2.5 Hidden-HMI and translucent interior surface adoption
- 4.3 Market Restraints
- 4.3.1 PFAS, DMF and vinyl-chloride compliance pressure
- 4.3.2 Hydrolysis and heat-aging limits in low-cost grades
- 4.3.3 Bio-based synthetic leather cost premium and scale constraints
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Supplier Power
- 4.5.2 Buyer Power
- 4.5.3 Threat of Substitutes
- 4.5.4 Threat of New Entrants
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value and Volume)
- 5.1 By Leather Type
- 5.1.1 PU Synthetic Leather
- 5.1.2 PVC Synthetic Leather
- 5.1.3 Bio-based Synthetic Leather
- 5.1.4 Silicone Synthetic Leather
- 5.1.5 TPO/TPU Synthetic Leather
- 5.2 By Manufacturing Technology
- 5.2.1 Solvent-based Coagulation and Coating
- 5.2.2 Water-based PU Coating
- 5.2.3 Solvent-free PU Systems
- 5.3 By Application
- 5.3.1 Footwear
- 5.3.2 Furnishing
- 5.3.2.1 Chairs
- 5.3.2.2 Sofas
- 5.3.2.3 Other Upholstery
- 5.3.3 Automotive Interiors
- 5.3.3.1 Seats
- 5.3.3.2 Door Trims and Panels
- 5.3.3.3 Dashboard and Instrument Panel Surfaces
- 5.3.3.4 Steering Wheel and Console Surfaces
- 5.3.3.5 Other Interior Surfaces
- 5.3.4 Bags, Wallets and Luggage
- 5.3.4.1 Wallets
- 5.3.4.2 Bags
- 5.3.4.3 Purses
- 5.3.5 Clothing and Fashion Accessories
- 5.3.5.1 Jackets
- 5.3.5.2 Belts
- 5.3.5.3 Other Apparel Accessories
- 5.3.6 Sports and Leisure Goods
- 5.3.7 Marine and Specialty Uses
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Anhui Anli Material Technology Co., Ltd.
- 6.4.2 Asahi Kasei Corporation
- 6.4.3 Baiksan Co., Ltd.
- 6.4.4 BASF SE
- 6.4.5 Continental AG
- 6.4.6 Covestro AG
- 6.4.7 Dow Inc.
- 6.4.8 FILWEL Co., Ltd.
- 6.4.9 Fujian Polytech Technology Corp., Ltd.
- 6.4.10 H.R. Polycoats Pvt. Ltd.
- 6.4.11 Jasch Industries Limited
- 6.4.12 Kolon Industries, Inc.
- 6.4.13 KURARAY CO., LTD.
- 6.4.14 Mayur Uniquoters Limited
- 6.4.15 NAN YA PLASTICS CORPORATION
- 6.4.16 Responsive Industries Limited
- 6.4.17 San Fang Chemical Industry Co., Ltd.
- 6.4.18 Seiren Co., Ltd.
- 6.4.19 TEIJIN LIMITED
- 6.4.20 Toray Industries, Inc.
- 6.4.21 Wanhua Chemical Group Co., Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space and Unmet-Need Assessment


