

|
시장보고서
상품코드
2117603
크리에이티브 자동화 소프트웨어 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Creative Automation Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
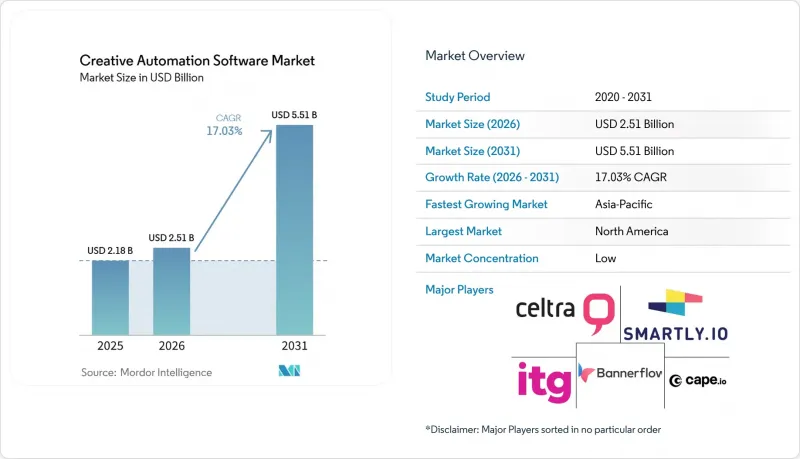
에 의하면, 크리에이티브 자동화 소프트웨어 시장 규모는 2025년 21억 8,000만 달러, 2026년 25억 1,000만 달러에서 2031년까지 55억 1,000만 달러로 확대된다고 예측되고 있어 2026년부터 2031년까지 연평균 성장률(CAGR)은 17.03%를 나타낼 전망입니다.
본 보고서는 구성 요소(소프트웨어 및 서비스), 도입 형태(클라우드, On-Premise, 하이브리드), 크리에이티브 기능(크리에이티브 생성 등), 기업 규모(대기업 및 중소기업), 최종 사용자 산업(BFSI 등), 구매자 유형(브랜드 및 광고주 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 크리에이티브 자동화 소프트웨어 시장 동향 및 인사이트
증가하는 옴니채널 크리에이티브 제작 수요
2026년, 브랜드 팀은 평균 6개의 리테일 미디어 네트워크를 관리하고 있으며, 그 수는 연말까지 8개에 달할 것으로 예측됩니다. 각 네트워크는 디스플레이, 동영상, 퍼포먼스 형식에 대해 서로 다른 요구 사항을 가지고 있습니다. 따라서 단일 캠페인이라도 소셜 플랫폼, 커넥티드 TV, 프로그래매틱 디스플레이, 리테일 미디어에 걸쳐 수백 개의 버전이 필요할 수 있습니다. 수작업에 의존하는 팀은 캠페인의 속도에 맞추어 이 방대한 양을 일관되게 제공할 수 없기 때문에 크리에이티브 자동화 소프트웨어 시장이 혜택을 보고 있습니다. '2025년 크리에이티브 운영 현황' 보고서에 따르면, 마케팅 및 크리에이티브 담당자의 53%가 AI 도구를 통해 워크플로우가 가속화되었다고 응답했습니다. 버전 관리 자동화가 이루어지지 않은 기업은 특히 주기가 짧고 형식이 다양한 FMCG, 소매, 미디어 캠페인에서 배포 지연이나 미디어 효율 저하를 겪을 가능성이 있습니다.
크리에이티브 워크플로우에 생성형 AI 통합
생성형 AI는 크리에이티브 자동화를 템플릿 채우기에서 프롬프트나 브리프를 기반으로 한 새로운 자산 제작으로 변화시키고 있습니다. 이를 통해 캠페인 브리프에서 실용적인 크리에이티브 결과물이 완성되기까지의 시간을 단축할 수 있습니다. 어도비는 2025년 10월, 브랜드 가이드라인에 부합하는 컨텐츠를 대규모로 제작할 수 있도록 지원하기 위해 ‘Firefly Design Intelligence’, 노코드 방식의 ‘Workflow Builder’, 그리고 ‘Content Production Agent’를 도입했습니다. 어도비에 따르면, 상위 50개 기업 고객의 90% 가까이가 어도비의 AI 우선 혁신을 채택하고 있으며, 포춘 100대 기업의 99%가 어도비 용도 내에서 AI를 활용하고 있다고 합니다. 독일 비트콤(Bitkom)의 조사에 따르면, 조사 대상 기업의 84%가 AI를 가장 영향력 있는 트렌드로 꼽았으며, 76%는 마케팅 자동화의 전략적 중요성이 높아질 것으로 예상했습니다. 따라서 크리에이티브 자동화 소프트웨어 시장은 과거 브리핑, 제작, 미디어 각 팀 간에 분담되던 업무를 흡수하고 있으며, 이를 통해 대행사나 브랜드가 캠페인을 전개하는 방식을 변화시키고 있습니다.
데이터 개인정보 보호 및 지적재산권에 대한 불확실성
AI 생성 컨텐츠에 대한 법적 규제는 주요 구매 시장에서 여전히 명확하지 않아, 이로 인해 소프트웨어 구매 주기가 길어질 가능성이 있습니다. 미국 저작권청의 저작권 및 AI 관련 보고서에 따르면, 저작권 보호를 위해서는 인간의 창작성이 요구된다고 명시되어 있어, 고도로 자동화된 워크플로우로 생성된 컨텐츠의 소유권에 대한 의문이 제기되고 있습니다. EU AI법 제53조에 규정된 저작권 준수 및 훈련 데이터 공개 요건 또한 브랜드 고객을 대상으로 범용 AI 모델을 사용하는 제공업체에 영향을 미칩니다. 이러한 규정은 법적 심사가 캠페인 승인에 밀접하게 연결되어 있는 BFSI(은행 및 금융 및 보험) 및 의료 분야의 광고주에게 특히 중요합니다. 조달 팀은 GDPR(EU 개인정보보호규정) 제22조, EU 디지털 단일 시장 지침, 그리고 영국의 ‘데이터(이용 및 접근)법 2025’도 고려해야 합니다. 크리에이티브 자동화 소프트웨어 시장은 이러한 마찰을 최소화하기 위해 훈련 데이터, 자산 권리, 인간에 의한 검토 및 데이터 취급에 관한 명확한 관리 체계를 입증해야 합니다.
부문 분석
2025년, 크리에이티브 자동화 소프트웨어 시장에서 소프트웨어의 점유율은 72.41%를 차지하며, 기업들이 중앙 집중식 SaaS(Software-as-a-Service) 플랫폼을 선호하는 경향을 반영하고 있습니다. 구매자는 공통 템플릿, 승인된 자산, 검토 단계, 배포 형식을 필요로 하기 때문에 플랫폼 선정 및 통합은 여전히 초기 투자의 주요 항목으로 남아 있습니다. 이러한 시스템은 브랜드, 캠페인 팀, 미디어 채널 및 거점을 초월하여 반복 가능한 작업을 지원하고 대량 생산의 일관성을 높입니다. 크리에이티브 자동화 소프트웨어 업계는 이러한 공유된 운영 계층에 의존하여 디자인, 마케팅, 규정 준수, 미디어 운영을 단편적인 업무 인계에 의존하지 않고 유기적으로 연계하고 있습니다. 또한 기업 고객은 누가 자산을 수정하거나 승인할 수 있는지를 관리하면서 광범위한 캠페인 포트폴리오 전반에 브랜드 규칙을 적용할 수 있다는 점을 중요하게 여깁니다.
서비스 시장은 2031년까지 연평균 성장률(CAGR) 18.82%로 확대될 것으로 예측되며, 가장 빠르게 성장하는 분야가 될 전망입니다. 여기에는 도입, API 통합, 맞춤형 모델 훈련, 관리형 크리에이티브 운영, 지속적인 최적화 등이 포함되지만, 많은 사내 팀에서는 이를 단독으로 지원하기 어렵습니다. Amazon, Walmart, General Mills, Colgate-Palmolive가 시각적 컨텐츠 제작에 채택하고 있는 Rocketium의 관리형 서비스 모델은 소프트웨어 구독을 넘어선 지원에 대한 수요가 높음을 보여줍니다. 벤더는 연간 계약에 전문 서비스를 추가할 수 있는 반면, 대행사는 확립된 소프트웨어 스택과 기존 고객 관계를 활용하여 관리형 서비스를 제공할 수 있습니다. 이로 인해 플랫폼 기능을 통해 고객 유지를 도모하는 소프트웨어 제공업체와, 워크플로우의 깊이, 전달 지원, 그리고 책임감 있는 크리에이티브 결과물로 경쟁하는 서비스 제공업체 간에 양극화가 발생하고 있습니다. 특히, 고객이 광범위한 캠페인 요구 사항을 미디어 팀이 추가 수정 작업 없이 활용할 수 있는 재현 가능한 제작 규칙, 승인 단계, 완성된 자산으로 전환할 수 있도록 지원이 필요한 상황에서 이러한 경향이 두드러집니다.
2025년에는 클라우드 도입이 시장의 74.18%를 차지했습니다. 이는 브랜드가 자체 인프라를 구매하지 않고도 제작 역량을 추가할 수 있기 때문입니다. 이는 소매 성수기, 신제품 출시, 그리고 신속한 버전 관리가 필요한 캠페인 이벤트 시 유용합니다. 또한 클라우드 시스템을 통해 분산된 팀이나 대행사가 동일한 승인된 자산, 관리 기능, 워크플로 이력을 공유하고 활용할 수 있게 됩니다. 클라우드 배포 분야의 크리에이티브 자동화 소프트웨어 시장 규모는 컨텐츠를 신속하게 생성, 적용, 배포할 수 있는 공유 제작 도구에 대한 업무적 요구와 밀접한 관련이 있습니다. 이러한 장점은 가격, 제품 또는 판촉 정보가 변경될 때 유연한 용량, 중앙 집중식 액세스 및 지속적인 업데이트가 제공하는 가치를 반영합니다.
하이브리드 배포는 2031년까지 연평균 성장률(CAGR) 17.69%로 확대될 것으로 예측되며, 가장 빠르게 성장하는 모델이 될 전망입니다. 금융 서비스, 의료, 정부 기관의 광고주는 특정 제작 워크로드에 클라우드 서비스를 활용하면서도 기밀 데이터를 관리된 환경 내에 보관할 수 있습니다. 이러한 구조를 통해 클라우드 규모의 크리에이티브 생성 및 워크플로우 기능에 대한 접근성을 희생하지 않고도 데이터 거버넌스 및 데이터 주권 요건을 충족할 수 있습니다. On-Premise 시스템은 독일 및 유럽연합(EU) 전역 등 엄격한 데이터 거주 규정이 적용되는 시장에서 여전히 중요한 역할을 수행하고 있습니다. GDPR(EU 개인정보보호규정), EU AI법의 투명성 요건, 그리고 각국의 데이터 현지화 규정에 따라 규제 대상 구매자에게 있어 도입 아키텍처는 실질적인 비즈니스 요건이 되고 있습니다. 이는 데이터 저장 위치, 생성된 컨텐츠의 검토, 그리고 대상 고객 정보와 완성된 크리에이티브의 분리가 조달 결정, 운영 프로세스, 플랫폼 구성 방식에 영향을 미칠 수 있기 때문입니다.
지역별 분석
북미는 광범위한 프로그래매틱 광고 활동과 벤더 및 주요 구매자가 밀집해 있는 것을 배경으로, 2025년에는 시장의 36.73%를 차지했습니다. 미국의 리테일 미디어 지출은 2025년에 1,076억 달러에 달하여 미국 디지털 광고 지출의 30%를 차지했습니다. 이 지역의 브랜드 팀은 2026년에 평균 6개의 리테일 미디어 네트워크를 관리하고 있으며, 그 수는 연말까지 8개에 달할 것으로 예측됩니다. 각 네트워크마다 서로 다른 크리에이티브 형식이 필요하기 때문에 자동화된 제작 및 자산 버전 관리에 대한 수요가 증가하고 있습니다. 캐나다와 멕시코는 국경을 초월한 캠페인, 디지털 소매 활동의 확대, 그리고 중소기업을 위한 플랫폼 네이티브 크리에이티브 툴에 대한 접근성 확대를 통해 지역 전체 수요를 견인하고 있습니다.
유럽은 두 번째로 큰 지역 시장이며, 영국, 독일, 프랑스가 기업들의 AI 도입을 주도하고 있습니다. Bitkom 보고서에 따르면, 조사 대상 독일 기업의 84%가 AI를 가장 영향력 있는 트렌드로 꼽았으며, 76%는 마케팅 자동화의 중요성이 높아질 것으로 예상하고 있습니다. 유럽의 데이터 보호 요건으로 인해, 프로덕션 환경에서는 클라우드 서비스를 이용하면서도 데이터 주권을 유지하는 하이브리드형 도입이 촉진되고 있습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 20.83%로 확대될 것으로 예측되며, 지역별로는 가장 높은 성장률을 보이고 있습니다. 인도, 중국, 일본, 한국 및 동남아시아에서는 디지털 광고 활동이 활발해지고 있으며, 다양한 언어와 현지 고객층에 대응할 수 있는 컨텐츠가 요구되고 있습니다.
중동 및 아프리카, 남미는 시장으로서 아직 초기 단계에 있지만, 모두 보다 광범위한 보급을 뒷받침할 조건을 갖추고 있습니다. 사우디아라비아와 아랍에미리트는 경제 다각화 프로그램의 일환으로 디지털 광고 인프라에 대한 투자를 추진하고 있습니다. 브라질은 성숙한 디지털 광고 환경과 소셜 커머스 이용 확대에 힘입어 남미 지역을 주도하고 있습니다. 한편, 아르헨티나를 비롯한 기타 남미 국가들에서는 기업의 도입률은 낮은 편이지만, 현지 기술 인프라가 갖춰지지 않았더라도 클라우드 플랫폼을 활용할 수 있습니다. 인도에서는 22개의 공용어와 다양한 소비자 행동이 현지화 수요를 창출하고 있습니다. 또한, 덴츠의 ‘AI For Growth Creative Lines’는 통합된 AI 인프라를 통해 브랜디드 컨텐츠, 퍼포먼스 광고 및 프로세스 혁신을 통합하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.01According to Mordor Intelligence, the creative automation software market size is projected to expand from USD 2.18 billion in 2025 and USD 2.51 billion in 2026 to USD 5.51 billion by 2031, registering a CAGR of 17.03% between 2026 and 2031.
This report is Segmented by Component (Software, and Services), Deployment Mode (Cloud, On-Premise, and Hybrid), Creative Capability (Creative Generation, and More), Enterprise Size (Large Enterprises, and Small and Medium Enterprises), End-User Industry (BFSI, and More), Buyer Type (Brands and Advertisers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Creative Automation Software Market Trends and Insights
Rising Omnichannel Creative Production Requirements
Brand teams manage an average of 6 retail media networks in 2026, and that number is projected to reach 8 by year-end. Each network uses different requirements for display, video, and performance formats. A single campaign can therefore require hundreds of versions across social platforms, connected TV, programmatic display, and retail media. The creative automation software market benefits because manual teams cannot consistently deliver this volume at campaign speed. The 2025 State of Creative Ops report found that 53% of marketing and creative professionals said AI tools had accelerated their workflows. Companies without automated versioning can face delayed launches and lower media efficiency, particularly in FMCG, retail, and media campaigns with short cycles and varied formats.
Generative AI Integration Into Creative Workflows
Generative AI is changing creative automation from template population to the production of new assets from prompts and briefs. This can reduce the time between a campaign brief and usable creative output. Adobe introduced Firefly Design Intelligence, a no-code Workflow Builder, and a Content Production Agent in October 2025 to support brand-compliant content production at scale. Adobe stated that nearly 90% of its top 50 enterprise accounts had adopted its AI-first innovations, while 99% of Fortune 100 companies had used AI within an Adobe application. Germany's Bitkom found that 84% of surveyed enterprises ranked AI as the most influential trend, and 76% expected marketing automation to gain strategic importance. The creative automation software market is therefore absorbing work that once sat between the briefing, production, and media teams, thereby changing how agencies and brands organize campaign delivery.
Data Privacy and Intellectual Property Uncertainty
Legal rules for AI-generated content remain unsettled across major purchasing markets, which can extend software buying cycles. The U.S. Copyright Office's reports on copyright and AI state that copyright protection requires human authorship, creating ownership questions for content created with heavily automated workflows. The EU AI Act's Article 53 requirements on copyright compliance and training-data disclosures also affect providers using general-purpose AI models for brand customers. These rules are particularly relevant to BFSI and healthcare advertisers, where legal review is closely tied to campaign approvals. Procurement teams must also consider GDPR Article 22, the EU Digital Single Market Directive, and the UK Data (Use and Access) Act 2025. The creative automation software market must demonstrate clear controls over training data, asset rights, human review, and data handling to limit this friction.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Personalized Advertising Content
- Cloud-Based Adoption by Small and Medium Enterprises
- Commoditization of Basic Creative Generation Features
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 72.41% of the creative automation software market share in 2025, reflecting enterprise preference for centralized software-as-a-service platforms. Platform selection and integration remained the main early investment because buyers need common templates, approved assets, review stages, and delivery formats. These systems support repeatable work across brands, campaign teams, media channels, and locations, which makes high-volume production more consistent. The creative automation software industry depends on this shared operating layer to connect design, marketing, compliance, and media operations without relying on disconnected handoffs. Enterprise customers also value the ability to apply brand rules across a broad portfolio of campaigns while retaining oversight of who can change or approve an asset.
Services are projected to expand at an 18.82% CAGR through 2031, making them the fastest-growing component. They include implementation, API integration, custom model training, managed creative operations, and ongoing optimization, which many internal teams cannot support alone. Rocketium's managed service model, used by Amazon, Walmart, General Mills, and Colgate-Palmolive for visual content production, demonstrates the demand for support that extends beyond a software subscription. Vendors can add professional services to annual contracts, while agencies can provide managed delivery using established software stacks and their existing client relationships. This creates a split between software providers defending retention through platform capabilities and service providers competing on workflow depth, delivery support, and accountable creative outcomes, especially where customers need help translating broad campaign requirements into repeatable production rules, approval stages, and finished assets that media teams can use without further rework.
Cloud deployment held 74.18% of the market in 2025 because it lets brands add production capacity without purchasing their own infrastructure. It is useful during retail periods, new product launches, and campaign events that require rapid versioning. Cloud systems also enable dispersed teams and agencies to use the same approved assets, controls, and workflow history. The creative automation software market size for cloud delivery is tied to the operational need for shared production tools that can generate, adapt, and distribute content quickly. Its lead reflects the value of flexible capacity, centralized access, and recurring updates when pricing, products, or promotional information changes.
Hybrid deployment is projected to expand at a 17.69% CAGR through 2031, making it the fastest-growing model. Financial services, healthcare, and government advertisers can keep sensitive data in controlled environments while using cloud services for selected production workloads. This arrangement addresses data governance and sovereignty requirements without giving up access to cloud-scale creative generation and workflow capabilities. On-premises systems remain relevant in markets with strict data-residency rules, including Germany and the wider European Union. GDPR, EU AI Act transparency requirements, and national data localization rules are making deployment architecture a practical business requirement for regulated buyers, since the location of data, the review of generated content, and the separation of audience information from finished creative can affect procurement decisions, operating processes, and the way a platform is configured.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud
- On-Premise
- Hybrid
- By Creative Capability
- Creative Generation
- Creative Adaptation and Asset Versioning
- Creative Localization and Personalization
- Dynamic Creative Optimization
- Creative Analytics and Testing
- Creative Workflow and Approval Automation
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By End-User Industry
- IT and Telecommunication
- BFSI
- Healthcare and Life Sciences
- Retail and E-Commerce
- Industrial Manufacturing
- Education and Research Institutions
- Media and Entertainment
- Government and Administration
- Travel and Hospitality
- By Buyer Type
- Brands and Advertisers
- Advertising Agencies
- Publishers and Media Owners
- E-Commerce Merchants
- In-House Creative Teams
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 36.73% of the market in 2025, supported by extensive programmatic advertising activity and a dense base of vendors and large buyers. U.S. retail media spending reached USD 107.6 billion in 2025, accounting for 30% of U.S. digital advertising spend. Brand teams in the region manage an average of 6 retail media networks in 2026, and that count is projected to reach 8 by year-end. Each network requires distinct creative formats, which increases demand for automated production and asset versioning. Canada and Mexico add to regional demand through cross-border campaigns, expanding digital retail activity, and growing access to platform-native creative tools for smaller businesses.
Europe is the second-largest regional market, with the United Kingdom, Germany, and France supporting enterprise adoption. Bitkom reported that 84% of surveyed German companies ranked AI as the most influential trend, and 76% expected marketing automation to become more important. European data protection requirements encourage hybrid deployments that preserve data sovereignty while using cloud services for production. Asia-Pacific is projected to expand at a 20.83% CAGR through 2031, the fastest regional rate. India, China, Japan, South Korea, and Southeast Asia are increasing digital advertising activity and need content that can serve varied languages and local audiences.
The Middle East, Africa, and South America are earlier-stage markets, but both show conditions that can support wider adoption. Saudi Arabia and the United Arab Emirates are investing in digital advertising infrastructure as part of economic diversification programs. Brazil leads South American activity through a mature digital advertising environment and rising social commerce use, while Argentina and other South American countries have lower enterprise adoption but can use cloud platforms without local technology infrastructure. India's 22 official languages and varied consumer behavior create demand for localization, while Dentsu Japan's AI For Growth Creative Lines combines branded content, performance advertising, and process transformation through a unified AI infrastructure.
- Celtra, Inc.
- Smartly.io Solutions Oy
- Bannerflow AB
- Inspired Thinking Group (ITG) Limited
- Cape.io Limited
- The Brief AI, Inc.
- Rocketium Technologies Private Limited
- Marpipe, Inc.
- Hunch Insights Private Limited
- Ziflow, Inc.
- Mediawide Systems Limited
- Jivox Corporation
- RevJet, Inc.
- Pencil Technologies, Inc.
- Typeface, Inc.
- Omneky, Inc.
- VidMob, Inc.
- Shuttlerock Limited
- AdCreative.ai
- Madgicx Ltd.
- Inmagine Group Pte. Ltd.
- Lumen5 Technologies Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Omnichannel Creative Production Requirements
- 4.2.2 Generative AI Integration Into Creative Workflows
- 4.2.3 Growing Demand for Personalized Advertising Content
- 4.2.4 Cloud-Based Creative Automation Adoption by Small and Medium Enterprises
- 4.2.5 Creative-Media Feedback Loops Becoming Core Performance Infrastructure
- 4.2.6 Retail Media Catalog Volatility Increasing Automated Creative Demand
- 4.3 Market Restraints
- 4.3.1 Data Privacy and Intellectual Property Uncertainty
- 4.3.2 Commoditization of Basic Creative Generation Features
- 4.3.3 Structural Disconnect Between Creative and Media Teams
- 4.3.4 Platform Rejection, Brand Authenticity, and Quality-Control Risk
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.2.3 Hybrid
- 5.3 By Creative Capability
- 5.3.1 Creative Generation
- 5.3.2 Creative Adaptation and Asset Versioning
- 5.3.3 Creative Localization and Personalization
- 5.3.4 Dynamic Creative Optimization
- 5.3.5 Creative Analytics and Testing
- 5.3.6 Creative Workflow and Approval Automation
- 5.4 By Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By End-User Industry
- 5.5.1 IT and Telecommunication
- 5.5.2 BFSI
- 5.5.3 Healthcare and Life Sciences
- 5.5.4 Retail and E-Commerce
- 5.5.5 Industrial Manufacturing
- 5.5.6 Education and Research Institutions
- 5.5.7 Media and Entertainment
- 5.5.8 Government and Administration
- 5.5.9 Travel and Hospitality
- 5.6 By Buyer Type
- 5.6.1 Brands and Advertisers
- 5.6.2 Advertising Agencies
- 5.6.3 Publishers and Media Owners
- 5.6.4 E-Commerce Merchants
- 5.6.5 In-House Creative Teams
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Russia
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Southeast Asia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 Saudi Arabia
- 5.7.5.1.2 United Arab Emirates
- 5.7.5.1.3 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Celtra, Inc.
- 6.4.2 Smartly.io Solutions Oy
- 6.4.3 Bannerflow AB
- 6.4.4 Inspired Thinking Group (ITG) Limited
- 6.4.5 Cape.io Limited
- 6.4.6 The Brief AI, Inc.
- 6.4.7 Rocketium Technologies Private Limited
- 6.4.8 Marpipe, Inc.
- 6.4.9 Hunch Insights Private Limited
- 6.4.10 Ziflow, Inc.
- 6.4.11 Mediawide Systems Limited
- 6.4.12 Jivox Corporation
- 6.4.13 RevJet, Inc.
- 6.4.14 Pencil Technologies, Inc.
- 6.4.15 Typeface, Inc.
- 6.4.16 Omneky, Inc.
- 6.4.17 VidMob, Inc.
- 6.4.18 Shuttlerock Limited
- 6.4.19 AdCreative.ai
- 6.4.20 Madgicx Ltd.
- 6.4.21 Inmagine Group Pte. Ltd.
- 6.4.22 Lumen5 Technologies Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


