

|
시장보고서
상품코드
2118084
로커스트빈검 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Locust Bean Gum - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 로커스트빈검 시장은 2025년에 3억 2,635만 달러 규모로 평가되었고, 2026년에는 3억 3,523만 달러로 추정되고, 2031년까지 4억 27만 달러에 이를 것으로 예측되며, 예측 기간 중 CAGR 3.61%로 성장할 전망입니다.
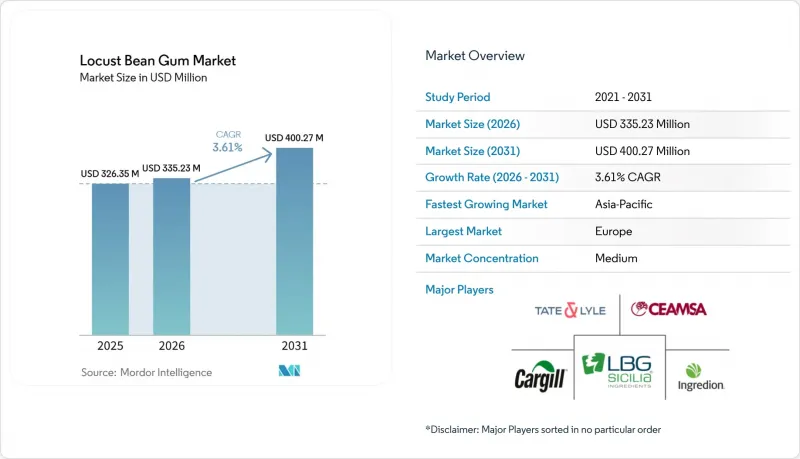
본 보고서는 형태별(분말, 과립, 기타), 용도별(식품 및 음료, 의약품·기능성 식품, 화장품 및 퍼스널케어, 산업용, 기타), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러)과 수량(톤) 모두로 제시되어 있습니다.
세계의 로커스트빈검 시장 동향 및 인사이트
식물성 식품 배합에서의 채택 확대
각 제조업체가 클린 라벨 제형을 지원하면서도 식감, 안정성, 일관성을 향상시키는 천연 원료를 점점 더 많이 요구함에 따라, 식물성 식품 제형에서 로커스트빈검의 채택이 증가하고 있습니다. 로커스트빈검은 효과적인 점도 조절, 수분 유지력, 가공 안정성을 제공하기 때문에 식품 배합에서 선호되는 식물성 하이드로콜로이드입니다. 다른 천연 검과의 호환성으로 인해 배합 성능과 제품 품질이 더욱 향상됩니다. 플랜트베이스 식품 협회(PBFA)의 보고서에 따르면, 2025년에는 미국 가구의 60%가 식물 유래 제품을 구매할 것으로 예상되며, 이는 식물성 식품에 대한 소비자의 수용도가 높아지고 있음을 반영함과 동시에, 로커스트빈검과 같은 기능성 원료에 대한 수요 증가를 뒷받침하고 있습니다.
편의식품 및 즉석식품의 확대
편의식품 및 즉석식품 시장의 확대가 로커스트빈검 시장을 견인하고 있습니다. 이는 제조업체들이 가공, 포장, 보관, 유통의 전 과정을 통해 일관된 식감, 점도, 제품 안정성을 확보할 수 있는 기능성 원료를 점점 더 많이 찾고 있기 때문입니다. 로커스트빈검은 다양한 가공 조건에서도 제품의 품질을 유지하면서 보습성을 향상시키고 배합의 안정성을 높이기 때문에 대규모 식품 제조에 최적입니다. 또한, 이 원료는 동결·해동 안정성을 높이고 침출액의 발생을 억제합니다. 이는 냉장·냉동 식품 용도에서 매우 중요한 성능 요건입니다. 간편하고 조리 과정이 적은 식품에 대한 수요가 계속 증가하는 가운데, 각 제조업체는 가공 효율 향상, 합성 첨가물 의존도 감소, 장기 보존 기간 동안 일관된 제품 품질 유지를 도모하기 위해 로커스트빈검과 같은 다기능 천연 하이드로콜로이드를 배합하고 있습니다.
캐롭 씨앗 공급량 제한
캐롭 씨앗 공급이 제한적이라는 점은 로커스트빈검 시장의 주요 제약 요인으로 작용하고 있습니다. 로커스트빈검은 캐러브 나무 열매에서만 추출되기 때문에 원료는 제한된 농업 생산 지역으로 한정되어 있습니다. 캐러브 재배는 지중해 지역의 특정 지역에 집중되어 있어, 수요가 증가하더라도 생산을 신속하게 확대하기 어렵습니다. 또한 캐롭 나무의 성숙 기간이 긴 것도 공급 증가를 제약하고 있어, 생산자가 시장 수요에 신속하게 대응하기 어렵게 만듭니다. 이러한 재배 지역의 계절적 수확량 변동과 기후에 대한 민감성은 공급망에 추가적인 불확실성을 더하고 있습니다. 제한된 원료에 대한 이러한 의존은 공급의 불확실성을 야기하여 생산 계획에 영향을 미칠 뿐만 아니라, 특히 수요가 급증하는 시기나 주요 생산 지역에서 악천후가 발생할 경우, 산업 제조업체에 대한 로커스트빈검의 안정적인 공급을 제한할 가능성이 있습니다.
부문 분석
2025년, 로커스트빈검 시장에서 분말은 63.42%의 점유율을 차지했습니다. 이는 가공 효율성, 저장 안정성, 현대적인 제조 공정과의 적합성 덕분입니다. 분말 형태는 균일한 입자 크기와 일관된 물리적 특성을 갖추고 있어 정확한 계량, 가공 시 분산성 향상, 로트 간 성능 안정성을 가능하게 합니다. 적절한 보관 조건에서는 물리적 손상을 입기 어렵고 보존 안정성도 길기 때문에 다른 형태에 비해 운송, 보관, 취급이 용이합니다. 제조업체들은 자동 계량, 이송, 혼합 및 혼합 장비와의 통합성이 뛰어나 수작업을 줄이면서 생산 효율과 공정 관리를 향상시킬 수 있기 때문에 분말 형태를 선호합니다. 또한, 분말 형태는 배합 조정의 유연성을 높이고 재고 관리를 간소화하며, 여러 제조 시설에 걸친 표준화된 생산을 지원합니다.
과립은 뛰어난 유동성, 분진 발생 감소, 산업용 가공 환경에서의 취급 효율 향상 등에 힘입어 2026-2031년 연평균 성장률(CAGR) 5.49%를 나타낼 것으로 예측됩니다. 입자 크기가 크기 때문에 운송, 보관, 생산 시 공기 중으로의 재료 손실을 최소화하여, 더 청결한 제조 환경과 작업장 안전성 향상에 기여합니다. 또한, 과립 형태의 로커스트빈검은 자동 공급, 이송, 계량 시스템과의 호환성이 향상되어 보다 정확한 원료 공급을 가능하게 하고, 가공 공정의 중단을 줄여줍니다. 게다가, 과립은 보관 중 고결이 잘 일어나지 않고 다양한 환경 조건에서도 높은 물리적 안정성을 나타내므로 재고 관리가 간소화되고 장기간에 걸쳐 일관된 제품 품질을 유지할 수 있습니다.
지역별 분석
2025년, 유럽은 전 세계 로커스트빈검 시장 매출의 32.31%를 차지했으며, 확립된 하이드로콜로이드 가공 산업, 엄격한 식품 원료 규제 체계, 제품 품질 및 추적성에 대한 강한 중시 덕분에 주도적인 위치를 유지했습니다. 이 지역은 높은 가공 능력, 천연 식품 첨가물의 높은 보급률, 원료 기술 분야의 지속적인 혁신에 힘입어 성숙한 밸류체인의 혜택을 누리고 있습니다. 또한, 규정(EC) 제1333/2008호에 따른 E 410(로커스트빈검)의 승인으로, 식품 전반에 걸친 사용에 관한 통일된 규제 체계가 마련되어 제조업체의 신뢰가 높아졌으며, 시판 제품에의 장기적인 배합이 촉진되고 있습니다. 유럽의 강력한 기술 전문 지식, 확립된 품질 기준, 통합된 공급망은 세계 시장에서 이 지역의 지배적 지위를 지속적으로 강화하고 있습니다.
아시아태평양은 해당 지역의 하이드로콜로이드 가공 능력의 급속한 확대, 원료 생산에 대한 투자 증가, 국내 부가가치 창출 강화에 힘입어 2026-2031년 5.53%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 이 지역은 가공 기술, 혼합 능력, 원료 표준화의 향상을 통해 주로 로커스트빈검의 순수입국이었던 상태에서 세계 하이드로콜로이드 밸류체인에서 보다 적극적인 역할을 수행하는 존재로 착실하게 전환하고 있습니다. 현대적인 제조 인프라에 대한 투자 확대, 기술적 전문성 향상, 산업용 가공 능력 확충을 통해 지역 제조업체들은 수입 의존도를 낮추면서 국내 및 국제 시장에서 경쟁력을 높일 수 있게 되었습니다. 이러한 구조적 변화로 인해 예측 기간 동안 해당 지역은 평균 이상의 성장을 지속할 것으로 전망됩니다.
북미, 남미, 중동 및 아프리카는 세계 로커스트빈검 시장에서 규모는 작지만 전략적으로 중요한 점유율을 차지하고 있습니다. 북미는 고성능 천연 하이드로콜로이드에 대한 강력한 수요, 첨단 배합 기술, 프리미엄 등급 원료 채택을 뒷받침하는 엄격한 품질 요건이 특징입니다. 남미는 식품 원료의 가공 능력 확대와 국제적인 공급망과의 통합 심화를 통해 그 위상을 점차 강화하고 있습니다. 한편, 중동 및 아프리카는 지중해 연안의 캐롭 생산 지역과 인접해 있다는 이점을 활용하여 원료 조달의 용이성과 지역 간 무역을 촉진하고 있습니다. 이 지역들은 유럽이나 아시아태평양에 비해 생산량은 비교적 적지만, 가공 인프라와 밸류체인의 현대화, 고부가가치 원료 제조에 대한 지속적인 투자를 통해 세계 로커스트빈검 시장에서 전략적 중요성이 계속해서 높아지고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the locust bean gum market was valued at USD 326.35 million in 2025 and is estimated at USD 335.23 million in 2026, projected to reach USD 400.27 million by 2031, expanding at a CAGR of 3.61% during the forecast period.
This report is Segmented by Form (Powders, Granules, and Others), Application (Food and Beverages, Pharmaceutical and Nutraceutical, Cosmetics and Personal Care, Industrial Applications, and Others), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Forecasts are Provided in Both Value (USD) and Volume (Tons).
Global Locust Bean Gum Market Trends and Insights
Rising adoption in plant-based food formulations
Adoption of locust bean gum in plant-based food formulations is rising as manufacturers increasingly require natural ingredients that improve texture, stability, and consistency while supporting clean-label formulations. Locust bean gum provides effective viscosity control, water-binding capacity, and processing stability, making it a preferred plant-derived hydrocolloid for food formulations. Its compatibility with other natural gums further improves formulation performance and product quality. The Plant Based Foods Association (PBFA) reported that 60% of United States households purchased plant-based products in 2025, reflecting growing consumer acceptance of plant-based foods and supporting increased demand for functional ingredients such as locust bean gum .
Expansion of convenience and ready-to-eat food products
The expansion of convenience and ready-to-eat food products is driving the locust bean gum market, as manufacturers increasingly seek functional ingredients that ensure consistent texture, viscosity, and product stability throughout processing, packaging, storage, and distribution. Locust bean gum helps maintain product integrity under varying processing conditions while improving moisture retention and extending formulation stability, making it well suited for large-scale food manufacturing. The ingredient also supports freeze-thaw stability and reduces syneresis, which are critical performance requirements in chilled and frozen food applications. As demand for convenient, minimally prepared food products continues to rise, manufacturers are incorporating multifunctional natural hydrocolloids such as locust bean gum to enhance processing efficiency, reduce reliance on synthetic additives, and maintain consistent product quality across extended shelf lives.
Limited availability of carob seeds
The limited availability of carob seeds is a key restraint on the locust bean gum market. Locust bean gum is extracted exclusively from the seeds of the carob tree, restricting the raw material base to a narrow agricultural source. Carob cultivation is concentrated in specific Mediterranean regions, limiting the ability to rapidly expand production when demand increases. The long maturation period of carob trees further constrains supply growth, making it difficult for producers to respond quickly to market requirements. Seasonal yield variations and climate sensitivity in these growing regions add another layer of unpredictability to the supply chain. This dependence on a limited raw material source creates supply uncertainty, affects production planning, and can restrict the consistent availability of locust bean gum for industrial manufacturers, particularly during periods of heightened demand or adverse weather conditions in key producing areas.
Other drivers and restraints analyzed in the detailed report include:
- Growing demand for natural and clean-label ingredients
- Advancements in hydrocolloid blending technologies
- Competition from alternative hydrocolloids
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Powder held a 63.42% share of the locust bean gum market in 2025, driven by its processing efficiency, storage stability, and compatibility with modern manufacturing operations. The powdered form offers uniform particle size and consistent physical properties, enabling precise dosing, improved dispersion during processing, and reliable batch-to-batch performance. It is easier to transport, store, and handle than other forms due to its lower susceptibility to physical damage and longer shelf stability under appropriate storage conditions. Manufacturers prefer powder as it integrates well with automated weighing, conveying, blending, and mixing equipment, reducing manual intervention while improving production efficiency and process control. The powdered format also allows greater flexibility in formulation adjustments, simplifies inventory management, and supports standardized production across multiple manufacturing facilities.
Granules are forecast to grow at a CAGR of 5.49% from 2026 to 2031, driven by their superior flowability, reduced dust generation, and improved handling efficiency in industrial processing environments. Their larger particle size minimizes airborne material loss during transportation, storage, and production, contributing to cleaner manufacturing conditions and improved workplace safety. Granular locust bean gum also offers improved compatibility with automated feeding, conveying, and metering systems, enabling more precise ingredient delivery and reducing processing interruptions. In addition, granules are less prone to caking during storage and exhibit greater physical stability under varying environmental conditions, simplifying inventory management and maintaining consistent product quality over extended periods.
Complete Report Scope:
- By Form
- Powders
- Granules
- Others
- By Application
- Food and Beverages
- Pharmaceutical and Nutraceutical
- Cosmetics and Personal Care
- Industrial Applications
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- South America
- Middle East and Africa
- North America
Geography Analysis
Europe accounted for 32.31% of the global locust bean gum market revenue in 2025, maintaining its leadership due to its well-established hydrocolloid processing industry, stringent food ingredient regulatory framework, and strong emphasis on product quality and traceability. The region benefits from a mature value chain supported by advanced processing capabilities, high adoption of natural food additives, and continuous innovation in ingredient technologies. Furthermore, the authorization of E 410 (Locust Bean Gum) under Regulation (EC) No. 1333/2008 has provided a harmonized regulatory framework for its use across food products, strengthening manufacturer confidence and encouraging long-term incorporation into commercial formulations. Europe's strong technical expertise, established quality standards, and integrated supply network continue to reinforce its dominant position in the global market.
Asia-Pacific is projected to register the fastest CAGR of 5.53% during 2026-2031, supported by the rapid expansion of regional hydrocolloid processing capabilities, increasing investments in ingredient manufacturing, and strengthening domestic value addition. The region is steadily transitioning from being primarily a net importer of locust bean gum to becoming a more active participant in the global hydrocolloid value chain through improvements in processing technologies, blending capabilities, and ingredient standardization. Growing investments in modern manufacturing infrastructure, enhanced technical expertise, and expanding industrial processing capacity are enabling regional manufacturers to reduce import dependence while improving competitiveness in both domestic and international markets. This structural transformation is expected to sustain the region's above-average growth over the forecast period.
North America, South America, and the Middle East and Africa (MEA) collectively account for a smaller yet strategically important share of the global locust bean gum market. North America is characterized by strong demand for high-performance natural hydrocolloids, advanced formulation technologies, and stringent quality requirements that support the adoption of premium-grade ingredients. South America is gradually strengthening its position through expanding food ingredient processing capabilities and increasing integration into international supply chains. Meanwhile, the Middle East & Africa benefits from its proximity to Mediterranean carob-producing regions, supporting raw material accessibility and regional trade. Although these regions contribute comparatively lower volumes than Europe and Asia-Pacific, ongoing investments in processing infrastructure, supply chain modernization, and value-added ingredient manufacturing continue to enhance their strategic importance in the global locust bean gum market...
- LBG Sicilia Ingredients S.R.L.
- Tate & Lyle PLC
- Compania Espanola de Algas Marinas (CEAMSA)
- Cargill, Incorporated
- Ingredion Inc.
- CAROB S.A.
- CP Kelco
- Nexira
- Polygal AG
- KERAGUM SA
- INCOM A.S.
- Gumix International, Inc.
- AEP Colloids
- Gum Technology Corporation
- Brenntag SE
- DuPont de Nemours, Inc.
- FMC Corporation
- Fiberstar, Inc.
- Kerry Group plc
- E. A. Calvo S.L.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising adoption in plant-based food formulations
- 4.2.2 Expansion of convenience and ready-to-eat food products
- 4.2.3 Growing demand for natural and clean-label ingredients
- 4.2.4 Advancements in hydrocolloid blending technologies
- 4.2.5 Increasing demand for natural thickening and stabilizing agents
- 4.2.6 Increasing use in pharmaceutical formulations
- 4.3 Market Restraints
- 4.3.1 Limited availability of carob seeds
- 4.3.2 Competition from alternative hydrocolloids
- 4.3.3 Risk of supply chain disruptions and logistics bottlenecks
- 4.3.4 Regulatory scrutiny and documentation requirements
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Form
- 5.1.1 Powders
- 5.1.2 Granules
- 5.1.3 Others
- 5.2 By Application
- 5.2.1 Food and Beverages
- 5.2.2 Pharmaceutical and Nutraceutical
- 5.2.3 Cosmetics and Personal Care
- 5.2.4 Industrial Applications
- 5.2.5 Others
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.1.4 Rest of North America
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 Italy
- 5.3.2.4 France
- 5.3.2.5 Spain
- 5.3.2.6 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.5 Middle East and Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials (if available), Strategic Information, Products, Recent Developments)
- 6.4.1 LBG Sicilia Ingredients S.R.L.
- 6.4.2 Tate & Lyle PLC
- 6.4.3 Compania Espanola de Algas Marinas (CEAMSA)
- 6.4.4 Cargill, Incorporated
- 6.4.5 Ingredion Inc.
- 6.4.6 CAROB S.A.
- 6.4.7 CP Kelco
- 6.4.8 Nexira
- 6.4.9 Polygal AG
- 6.4.10 KERAGUM SA
- 6.4.11 INCOM A.S.
- 6.4.12 Gumix International, Inc.
- 6.4.13 AEP Colloids
- 6.4.14 Gum Technology Corporation
- 6.4.15 Brenntag SE
- 6.4.16 DuPont de Nemours, Inc.
- 6.4.17 FMC Corporation
- 6.4.18 Fiberstar, Inc.
- 6.4.19 Kerry Group plc
- 6.4.20 E. A. Calvo S.L.


