

|
시장보고서
상품코드
2118249
단백질 시약 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Protein Reagents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 단백질 시약 시장 규모는 2025년에 104억 2,000만 달러로 평가되었고, 2026년 110억 2,000만 달러에서 2031년까지 142억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.32%를 나타낼 전망입니다.
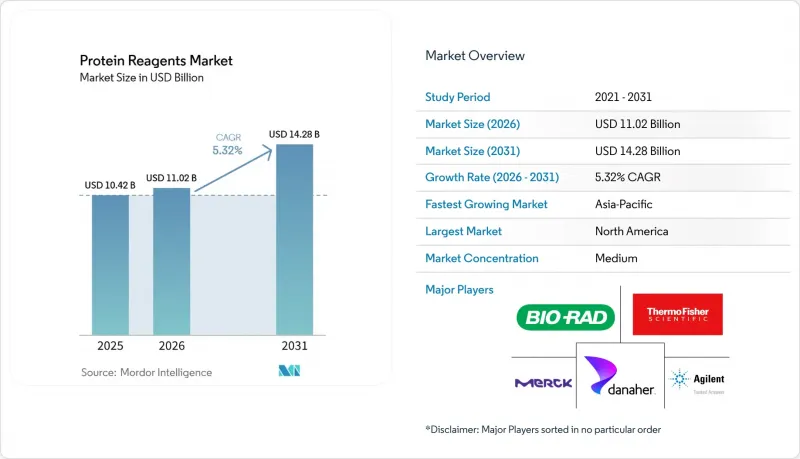
본 보고서는 제품 유형별(단백질 표지 시약, 단백질 정제 시약 등), 기술별(크로마토그래피용 시약, 전기영동용 시약 등), 용도별(단백질체학 연구, 신약·의약품 개발 등) 및 지역별(아시아태평양, 북미, 유럽, 기타 지역)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 단백질 시약 시장 동향 및 인사이트
바이오의약품 연구 개발에 대한 투자 증가
대형 제약사 및 바이오기술 기업의 꾸준한 연구개발비 지출은 신약 개발, 특성 평가, 공정 개발 등 각 활동에서 단백질 시약 시장에 안정적인 수요 기반을 지속적으로 제공합니다. 시약 소비는 초기 스크리닝에 그치지 않고, 프로그램이 진행됨에 따라 단백질 발현 작업, 분석법 개발, 비교 시험, 분석을 통한 확인에 이르기까지 계속됩니다. 또한, 바이오의약품 파이프라인이 복잡해지면 단백질 시약 시장도 혜택을 받게 됩니다. 이러한 프로그램에서는 더 긴 개발 주기에 걸쳐 반복적인 단백질 취급, 보다 상세한 특성 평가, 그리고 더 엄격한 문서화가 필요하기 때문입니다. 이러한 추세로 인해 진행 중인 프로그램 1건당 시약 사용량이 증가하여, 단기적인 자금 조달 변동이 총 수요에 미치는 영향을 완화하는 데 도움이 됩니다. 또한, 워크플로가 확립되면 연구팀은 분석 조건의 일관성을 선호하기 때문에 검증된 카탈로그를 보유한 공급업체에게도 호재가 됩니다. 단백질 시약 시장은 개발 중인 프로그램의 수뿐만 아니라 각 프로그램의 기술적 난이도가 높아지고 있다는 점에서도 강점을 얻고 있습니다.
확대되는 바이오의약품 파이프라인과 제조 능력
임상 연구에서 상업적 규모의 바이오의약품 생산으로의 전환에 따라, 정제, 안정화, 제형화 및 출하 지원의 각 워크플로우에서 단백질 시료 시장의 업무적 역할은 계속해서 확대되고 있습니다. FUJIFILM Wako Pure Chemical은 2024년 5월, 오사카 공장에서 우수 제조 기준(GMP)을 준수하는 원료 생산 능력을 3배로 확대했으며, 이 증산 능력을 항체 및 유전자 치료제 생산 수요의 확대와 직접 연계했습니다. 단백질 시약 시장은 이러한 생산 능력 확대의 혜택을 받고 있습니다. 상업적 생산에는 초기 연구 환경에서 일반적으로 요구되는 것보다 정기적인 로트 공급, 검증된 성능, 그리고 더 높은 공정 재현성이 요구되기 때문입니다. 바이오의약품 공장이 파일럿 배치에서 지속적 생산으로 전환됨에 따라, 납기 기간이 긴 소규모 주문 생산보다 카탈로그 등급 및 제조 등급 시약의 가치가 높아지고 있습니다. 이에 따라 적절한 문서, 확립된 로트 이력, 그리고 여러 생산 거점에 걸친 신뢰할 수 있는 유통 체계를 제공할 수 있는 공급업체가 유리해집니다. 이러한 상황으로 인해, 시간이 지남에 따라 단백질 시약 시장은 업스트림 연구 예산뿐만 아니라 산업용 바이오의약품의 제조 활동과도 더욱 밀접하게 연계될 것입니다.
특수 단백질 시약의 높은 비용
단백질 시약 시장은 특수 시약 및 제조용 등급 재료의 높은 비용으로 인해 제약을 받고 있으며, 소규모 연구소나 가격에 민감한 지역에서의 도입이 제한되고 있습니다. 2025년에 개최된 생물학적 시험 시약에 관한 국제 워크숍에서는 특히 물류상의 압박과 자금 면의 제약에 직면해 있는 저소득 국가에서 높은 비용, 수입의 복잡성, 그리고 적격 공급업체의 수가 제한적이라는 점이 주요 장벽으로 지적되었습니다. 연구실이 고정된 보조금 예산이나 벤처 캐피탈의 자금 계획 범위 내에서 운영되는 경우, 시약 가격의 급등으로 인해 시약의 품질, 분석 범위의 폭, 또는 실험 총량 중 하나를 희생할 수밖에 없게 됩니다. 이로 인해 단백질 시약 시장에 대한 수요가 사라지는 것은 아니지만, 인프라가 아직 발전 중인 지역에서는 고품질 제품의 도입이 더뎌집니다. 이러한 영향은 구매자가 수입 제품에 의존하고 있으며, 온도에 민감한 자재의 재고 관리에 유연성이 제한적인 경우에 가장 두드러집니다. 비용 측면의 압박은 고사양 제품을 표준화할 수 있는 재력을 갖춘 기관과, 사용을 엄격히 선별할 수밖에 없는 소규모 구매자 간의 격차를 확대할 가능성이 있습니다.
부문 분석
2025년 시점에서 단백질 정제 시약은 27.44%라는 가장 큰 점유율을 차지했으며, 이는 바이오의약품 제조 및 단백질 분리 워크플로우에서 해당 제품이 수행하는 핵심적인 역할을 반영합니다. 이러한 대규모 도입 실적은 초기 수확 단계부터 크로마토그래피 처리, 최종 제제에 이르기까지의 일상적인 사용을 반영하고 있으며, 이 카테고리가 단기간에 대체되기는 어려울 것입니다. 많은 연구실과 제조 팀이 일관된 수지 성능, 완충액 시스템 및 검증된 공정 화학에 의존하는 확립된 프로토콜로 운영되고 있기 때문에 시장에서는 계속해서 정제 제품이 선호되고 있습니다. 이는 사소한 공정 변경이라도 다운스트림 공정의 여러 단계에 걸친 반복적인 최적화가 필요할 수 있기 때문에 전환의 장벽이 되고 있습니다. 추출, 정량, 변형 제품은 여전히 중요한 보조 카테고리이지만, 이들은 일반적으로 워크플로우를 정의하기보다는 기존 워크플로우를 따르는 형태를 띱니다. 그 결과, 정제 시약의 위상은 워크플로우 내에서의 중심성, 반복 사용, 그리고 프로토콜 변경에 따른 비용과 밀접하게 연결되어 있습니다.
단백질 표지 시약은 2031년까지 연평균 성장률(CAGR) 6.44%를 나타낼 것으로 예측되며, 단백질 상호작용 연구, 활용 워크플로우 및 다중 검출 도구가 더욱 보편화됨에 따라 시장에서 가장 빠르게 성장하는 제품군이 될 전망입니다. 고급 분석법에서 구매자들이 더 엄격한 신호 품질과 배경 변동 감소를 요구함에 따라, 수요는 부위 특이적이고 용도 검증이 완료된 표지 형식으로 이동하고 있습니다. 이는 범용 염색 결합법으로는 충분한 제어를 얻기 어려운 경우가 많은 항체-약물 복합체(ADC) 연구, 근접 기반 분석법 및 생세포 연구에서 실질적인 중요성을 지닙니다. 또한, 단백질 가교 시약은 구조 단백질체학 및 상호작용체 매핑에서도 중요성이 커지고 있으며, 이러한 분야에서는 질량 분석을 수행하기 전에 단백질 간의 관계를 파악하기 위한 안정적인 기법이 연구자들에 의해 요구되고 있습니다. 단백질 정량 시약은 자동 스크리닝 환경에서 계속해서 빈번하게 사용되고 있으며, 플레이트 리더의 워크플로우와의 일관된 호환성과 간섭 내성이 여전히 중요하게 여겨지고 있습니다. 단백질 안정화 시약은 치료제 제형 및 콜드체인 관리 분야에서 급성장하는 틈새 시장을 차지하고 있으며, 고부가가치 및 용도 특화형 제품 수요를 향한 새로운 길을 제시하고 있습니다.
지역별 분석
2025년, 북미는 단백질 시약 시장의 44.73%를 차지하며 최대 지역이 되었습니다. 이 지역에는 탄탄한 제약 연구 역량과 학술 기관 및 병원의 광범위한 단백질체학 인프라가 구축되어 있습니다. 미국은 주요 수요 거점이며, 중개 의학, 암, 노화 및 운동 관련 단백질체학 프로그램의 시약 조달을 뒷받침하는 다년간의 연방 정부 보조금에 힘입고 있습니다. 또한, 이 지역은 광범위한 상업용 바이오의약품 및 첨단 치료 활동의 혜택을 받고 있으며, 이는 우수 제조 기준(GMP)을 준수하는 단백질 제품 및 분석용 단백질 제품에 대한 지속적인 수요를 견인하고 있습니다. 캐나다는 유전체학 및 치료 관련 연구 분야에서 전 세계에 분산된 카탈로그를 활용하는 생명공학 클러스터를 통해 지역 시장 기반의 심화에 기여하고 있습니다. 북미는 단백질 시약 시장에서 가장 확고하게 자리 잡은 지역이며, 그 강점은 신약 개발 활동과 산업 역량 모두에서 비롯됩니다.
아시아태평양은 단백질 시약 시장에서 가장 빠르게 성장하고 있는 지역으로, 2031년까지 연평균 성장률(CAGR) 6.35%로 확대될 것으로 예측됩니다. 이러한 성장은 각국의 국내 연구 시스템 제도화, 수탁 개발 능력 확충, 그리고 치료제 제조 프로그램의 진전에 의해 주도되고 있습니다. 세포 및 유전자 치료(CGT) 프로그램의 확대도 시장을 더욱 뒷받침하고 있으며, 임상 및 제조 규모의 확대에 따라 배양 보조제, 사이토카인, 정제용 시약 및 단백질 분석 시약에 대한 수요가 증가하고 있습니다. 한국에서는 바이오시밀러 및 항체-약물 복합체(ADC) 제조거점의 확대를 배경으로 고순도 시약에 대한 수요가 증가하고 있습니다. 중국과 인도는 광범위한 생명공학 정책 지원과 탄탄한 연구 기반을 통해 시장에 기여하고 있으며, 몇년전과 비교해 최종 사용자층이 더욱 다양해지고 있습니다. 검증된 공급 체계와 지역별 서비스망의 충실도는 국가별로 여전히 차이가 있어, 현지 공급 체계를 더욱 정비할 여지가 남아 있습니다.
유럽은 단백질 시약 시장에서 3위 지역 부문이며, 독일, 영국, 프랑스가 주요 수요 거점입니다. 이 지역은 멀티오믹스 및 단백질체학 연구 프로그램의 혜택을 받고 있으며, 규제가 잘 정립된 임상·제조 환경이 검증 완료되고 로트 관리가 이루어진 제품의 사용을 뒷받침하고 있습니다. 진단약 및 생물학적 제제에 대한 더욱 엄격한 규정 준수 요건은 대규모 품질 문서 관리를 유지하는 공급업체의 우월한 입지를 뒷받침하고 있습니다. 세계 기타 지역 시장은 수입 비용, 콜드체인 요건 및 제한된 현지 공급업체 기반으로 인해 여전히 규모가 작으며, 특히 온도에 민감한 재료나 규제 대상 재료의 경우 보급이 제한되고 있습니다. 국제 워크숍 조사 결과에 따르면, 접근성이 제한된 환경에서의 생물학적 시험 시약에 대해 지역별 유통 및 공급 조정의 중요성이 강조되고 있습니다. 주요 지역 이외의 성장세는 지속될 것으로 예상되지만, 그 기반은 북미, 아시아태평양 또는 유럽에 비해 낮은 수준에 머물 것으로 보입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the protein reagents market size was valued at USD 10.42 billion in 2025 and is estimated to grow from USD 11.02 billion in 2026 to reach USD 14.28 billion by 2031, at a CAGR of 5.32% during the forecast period (2026-2031).
This report is Segmented by Product Type (Protein Labeling Reagents, Protein Purification Reagents, and More), Technology (Chromatography-Based Reagents, Electrophoresis Reagents, and More), Application (Proteomics Research, Drug Discovery and Development, and More), and Geography (Asia-Pacific, North America, Europe, and Rest of the World). The Market Forecasts are Provided in Terms of Value (USD).
Global Protein Reagents Market Trends and Insights
Rising Investments in Biopharmaceutical R&D
Steady research spending by large pharmaceutical and biotechnology companies continues to provide the protein reagents market with a dependable demand base across discovery, characterization, and process development activities. Reagent consumption does not stop at early screening; it continues through protein expression work, assay development, comparability studies, and analytical confirmation as programs advance. The protein reagents market also benefits when biologics pipelines become more complex, as those programs require repeated protein handling, deeper characterization, and stricter documentation across longer development cycles. This pattern extends reagent use per active program and helps reduce the effect of short-term funding changes on total demand. It also supports suppliers with validated catalogs, as research teams prefer continuity in assay conditions once a workflow is established. The protein reagents market draws strength not only from the number of programs in development but also from the rising technical intensity of each program.
Growing Biopharmaceutical Pipeline and Manufacturing Capacity
The shift from clinical research to commercial-scale biologics production continues to expand the operational role of the protein reagents market across purification, stabilization, formulation, and release-support workflows. FUJIFILM Wako Pure Chemical tripled Good Manufacturing Practice (GMP)-compliant raw material production capacity at its Osaka facility in May 2024, directly linking added capacity to growth in antibody and gene therapeutic production needs. The protein reagents market benefits from this kind of capacity expansion because commercial manufacturing requires recurring lots, validated performance, and stronger process reproducibility than early research settings typically demand. As more biologics plants move from pilot batches to sustained output, catalog-grade and manufacturing-grade reagents gain greater value over small custom runs with longer delivery schedules. This favors suppliers that can provide ready documentation, established lot history, and dependable distribution across multiple production sites. Over time, this makes the protein reagents market more closely tied to industrial biologics execution, rather than only to upstream research budgets.
High Cost of Specialty Protein Reagents
The protein reagents market is constrained by the high cost of specialty and manufacturing-grade materials, limiting adoption in smaller laboratories and price-sensitive geographies. A 2025 international workshop on biological testing reagents identified high costs, import complexity, and a limited pool of qualified suppliers as core barriers, particularly for lower-income settings that face logistical pressures and funding constraints. When laboratories operate within fixed grant budgets or venture-backed spending plans, higher reagent prices force tradeoffs between reagent quality, assay breadth, and total experiment volume. This does not remove demand from the protein reagents market, but it slows the adoption of premium formats in regions where infrastructure is still developing. The effect is most pronounced where buyers depend on imported products and have limited flexibility in stocking temperature-sensitive materials. Cost pressure may widen the gap between well-funded institutions that can standardize high-specification products and smaller buyers that remain selective in their usage.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Demand for Proteomics-Driven Research Tools
- Expansion of Cell and Gene Therapy Clinical Programs
- Stringent Quality and Regulatory Compliance Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Protein Purification Reagents held the largest share at 27.44% in 2025, reflecting their central role in biologics production and protein isolation workflows. Their large installed base reflects routine use from early harvest steps through chromatographic processing and final preparation, making the category difficult to displace quickly. The market continues to favor purification products because many laboratories and manufacturing teams operate with established protocols that depend on consistent resin performance, buffer systems, and validated process chemistry. This creates switching friction, since even a modest process change can require repeat optimization across several downstream steps. Extraction, quantification, and modification products remain important supporting categories, yet they typically follow the broader installed workflow rather than defining it. As a result, the position of purification reagents remains linked to workflow centrality, repeat use, and the cost of protocol disruption.
Protein Labeling Reagents are forecast to grow at a 6.44% CAGR through 2031, making them the fastest-growing product group in the market as protein interaction studies, conjugation workflows, and multiplex discovery tools become more common. Demand is shifting toward site-specific and application-validated labeling formats, as buyers increasingly require tighter signal quality and lower background variation in advanced assays. This has practical importance for antibody-drug conjugate work, proximity-based assays, and live-cell studies where generic dye attachment methods often do not provide sufficient control. Protein Crosslinking Reagents are also gaining relevance in structural proteomics and interactome mapping, where researchers need stable methods to capture protein relationships before mass spectrometric analysis. Protein Quantification Reagents continue to see recurring use in automated screening environments, where consistent compatibility with plate-reader workflows and interference tolerance remain important. Protein Stabilization Reagents serve a growing niche in therapy formulation and cold-chain handling, representing another path toward higher-value, application-specific product demand.
Complete Report Scope:
- By Product Type
- Protein Labeling Reagents
- Protein Purification Reagents
- Protein Crosslinking Reagents
- Protein Stabilization Reagents
- Protein Extraction and Lysis Reagents
- Protein Quantification Reagents
- Protein Modification Reagents
- Other Protein Reagents
- By Technology
- Chromatography-Based Reagents
- Electrophoresis Reagents
- Immunoassay Reagents
- Mass Spectrometry Reagents
- Fluorescence-Based Reagents
- Other Technologies
- By Application
- Proteomics Research
- Drug Discovery and Development
- Biopharmaceutical Manufacturing
- Clinical Diagnostics
- Academic and Research
- Cell and Gene Therapy Research
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Rest of the World
- South America
- Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America held 44.73% of the protein reagents market in 2025, making it the largest region. The region has dense pharmaceutical research capacity and extensive academic and hospital proteomics infrastructure. The United States is the primary demand center, supported by multi-year federal awards that sustain reagent procurement across translational, cancer, aging, and exercise proteomics programs. The region also benefits from a broad base of commercial biologics and advanced therapy activity, which drives regular demand for Good Manufacturing Practice (GMP)-oriented and analytical protein products. Canada contributes to regional depth through biotechnology clusters that use distributed global catalogs for genomics and therapy-related work. North America is the most established geography in the protein reagents market, with strength derived from both discovery activity and industrial execution.
Asia-Pacific is the fastest-growing region in the protein reagents market and is projected to expand at a CAGR of 6.35% through 2031. Growth is driven by the institutionalization of domestic research systems, the development of contract development capacity, and therapy manufacturing programs across several countries. The Cell and Gene Therapy (CGT) program expansion further supports the market, as a larger clinical and manufacturing footprint increases demand for culture supplements, cytokines, purification inputs, and protein analytics. South Korea contributes to high-purity reagent demand, driven by its expanding biosimilar and antibody-drug conjugate manufacturing base. China and India contribute through broader biotechnology policy support and a larger installed research base, creating a more diversified set of end users compared to several years earlier. Validated availability and regional service depth remain uneven across countries, leaving room for further local supply development.
Europe is the third-largest regional segment in the protein reagents market, with Germany, the United Kingdom, and France as the primary demand centers. The region benefits from multi-omics and proteomics research programs, while regulated clinical and manufacturing environments support the use of validated and lot-controlled products. Stricter compliance requirements in diagnostics and biologics support premium positioning for suppliers that maintain quality documentation at scale. Rest of the World markets remain smaller due to import costs, cold-chain requirements, and a limited local supplier base, which restricts broader adoption, particularly for temperature-sensitive or regulated materials. International workshop findings have highlighted the importance of regional distribution and supply coordination for biological testing reagents in lower-access settings. Growth outside the major regions is expected to continue, but from a lower base than in North America, Asia-Pacific, or Europe.
- Abcam Limited
- Agilent Technologies, Inc.
- Bio-Rad Laboratories, Inc.
- Bio-Techne Corporation
- Danaher Corporation
- FUJIFILM Wako Pure Chemical Corporation
- LGC Biosearch Technologies
- Merck KGaA
- PerkinElmer
- Promega Corporation
- Proteintech Group
- Rockland Immunochemicals
- Takara Bio Inc.
- Thermo Fisher Scientific Inc.
- Vector Laboratories
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Investments in Proteomics and Protein Research
- 4.2.2 Growing Biopharmaceutical and Biosimilar Development
- 4.2.3 Increasing Demand for Protein Characterization and Analysis
- 4.2.4 Expansion of Cell and Gene Therapy Research
- 4.2.5 Growing Use of Protein-Based Diagnostics and Biomarker Discovery
- 4.3 Market Restraints
- 4.3.1 High Cost of Specialty Protein Reagents
- 4.3.2 Stringent Quality and Regulatory Requirements
- 4.3.3 Limited Stability and Shelf Life of Certain Protein Reagents
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Protein Labeling Reagents
- 5.1.2 Protein Purification Reagents
- 5.1.3 Protein Crosslinking Reagents
- 5.1.4 Protein Stabilization Reagents
- 5.1.5 Protein Extraction and Lysis Reagents
- 5.1.6 Protein Quantification Reagents
- 5.1.7 Protein Modification Reagents
- 5.1.8 Other Protein Reagents
- 5.2 By Technology
- 5.2.1 Chromatography-Based Reagents
- 5.2.2 Electrophoresis Reagents
- 5.2.3 Immunoassay Reagents
- 5.2.4 Mass Spectrometry Reagents
- 5.2.5 Fluorescence-Based Reagents
- 5.2.6 Other Technologies
- 5.3 By Application
- 5.3.1 Proteomics Research
- 5.3.2 Drug Discovery and Development
- 5.3.3 Biopharmaceutical Manufacturing
- 5.3.4 Clinical Diagnostics
- 5.3.5 Academic and Research
- 5.3.6 Cell and Gene Therapy Research
- 5.3.7 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 Rest of the World
- 5.4.4.1 South America
- 5.4.4.2 Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Abcam Limited
- 6.4.2 Agilent Technologies, Inc.
- 6.4.3 Bio-Rad Laboratories, Inc.
- 6.4.4 Bio-Techne Corporation
- 6.4.5 Danaher Corporation
- 6.4.6 FUJIFILM Wako Pure Chemical Corporation
- 6.4.7 LGC Biosearch Technologies
- 6.4.8 Merck KGaA
- 6.4.9 PerkinElmer
- 6.4.10 Promega Corporation
- 6.4.11 Proteintech Group
- 6.4.12 Rockland Immunochemicals
- 6.4.13 Takara Bio Inc.
- 6.4.14 Thermo Fisher Scientific Inc.
- 6.4.15 Vector Laboratories
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


