

|
시장보고서
상품코드
2118889
크리에이티브 디자인 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Creative Design Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
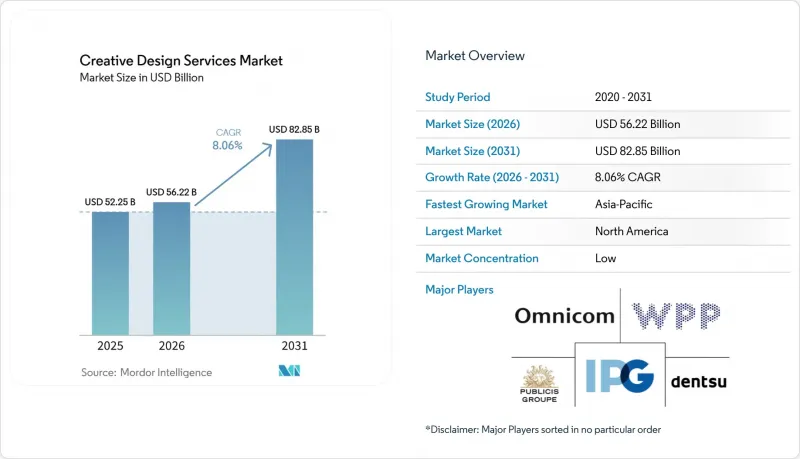
에 의하면, 크리에이티브 디자인 서비스 시장 규모는 2025년 522억 5,000만 달러로 평가되었고, 2026년 562억 2,000만 달러에서 2031년까지 828억 5,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 성장률(CAGR)은 8.06%를 나타낼 전망입니다.
본 보고서는 서비스 유형별(브랜드 아이덴티티 및 자산, 소셜 및 퍼포먼스용 크리에이티브, 패키지 및 인쇄 디자인, 디지털 디자인 지원, 캠페인 디자인 등), 플랫폼별(크리에이티브 에이전시 네트워크 등), 고객 규모별(대기업 등), 서비스 모델별(프로젝트 기반 계약 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 크리에이티브 디자인 서비스 시장 동향 및 인사이트
‘상시 가동형’ 옴니채널 크리에이티브 혁신에 대한 수요 증가
현재 브랜드들은 매장, 소셜 채널, 커넥티드 TV, 소매 미디어 광고 게재, 그리고 매장 내 디지털 스크린을 동시에 관리하고 있습니다. 각 채널마다 고유한 형식, 카피 길이, 시각적 계층 구조가 요구되기 때문에 크리에이티브 디자인 서비스 시장은 그 혜택을 누리고 있습니다. 과거에는 연간 12회의 캠페인 주기를 계획하던 마케팅 팀도 현재는 분기마다 다수의 소규모 업데이트를 관리하게 되었습니다. 따라서 단일 캠페인에서도 클라이언트와의 전반적인 관계에 있어 더 많은 제작 작업이 발생하게 됩니다. 옴니콤은 대규모 제작을 지원하기 위해 2026년 1월 차세대 ‘Omni’ 플랫폼을 도입할 예정이며, 이 시스템을 통해 크리에이티브 처리 능력을 25-55% 향상시킬 수 있다고 발표했습니다. 이러한 변화로 인해 개별 캠페인 실행보다 지속적인 크리에이티브 제작 능력이 더욱 중요해지고 있습니다.
AI를 활용한 디자인 제작으로 납기 단축
옴니콤이 자사 플랫폼의 실적으로 제시한 바에 따르면, 생성형 AI를 통해 템플릿 기반이나 변형이 많은 자산의 제작 시간이 30-50% 단축되었습니다. 그 결과, 일상적인 제작 업무는 AI를 활용한 워크플로로 점차 전환되고 있습니다. 한편, 새로운 콘셉트나 문화적 배경, 규제 대상 컨텐츠가 포함된 복잡한 프로젝트의 경우 여전히 인간의 충분한 판단이 요구됩니다. WPP는 2025년 연간 평균 환율을 기준으로 WPP Open에 매년 3억 파운드(3억 8,300만 달러)를 투자했습니다. WPP와 어도비는 2026년 2월, 브랜드 고유의 지적 재산을 기반으로 훈련된 컨텐츠를 지원하기 위해 Adobe Firefly Foundry를 WPP Open에 통합하기 위해 파트너십을 확대했습니다. 클라이언트의 워크플로우에 AI 기반 조정 기능을 통합하는 제공업체는 인력을 늘리지 않고도 더 많은 과금 가능한 성과를 창출할 수 있습니다.
인하우징과 셀프 서비스 도구가 가격에 압박을 가하고 있다.
브랜드들은 사내 크리에이티브 팀을 단순한 비용 절감 수단이 아닌 전략적 기능으로 인식하는 경향이 강해지고 있습니다. ANA의 ‘인하우스 에이전시 포럼 보고서’에 따르면, 조사 대상 브랜드의 53% 이상이 자사의 인하우스 크리에이티브 팀을 전략적 파트너로 간주하고 있었습니다. 또한 생성형 AI의 등장으로 사내 팀도 일상적인 소셜 미디어용 그래픽이나 이메일 템플릿, 사소한 수정 작업을 훨씬 수월하게 처리할 수 있게 되었습니다. 이러한 압박은 업무량이 방대하고 표준화된 형식이 요구되는 제공업체에게 가장 크게 가중되고 있습니다. 반면, 전략적인 콘셉트나 전문적인 기술, 복잡한 조정이 필요한 프로젝트의 경우 그 영향은 비교적 미미합니다. 따라서 크리에이티브 디자인 서비스 시장에서는 업무가 셀프 서비스 도구나 사내 팀으로 이동함에 따라 일상적인 결과물에 대한 가격 경쟁이 격화되고 있습니다.
부문 분석
2025년, 소셜 및 퍼포먼스 크리에이티브는 크리에이티브 디자인 서비스 시장 점유율의 27.83%를 차지했습니다. 이러한 위상은 유료 소셜 광고 및 퍼포먼스 광고에 대한 지속적인 지출을 반영합니다. 캠페인 최적화에는 빈번한 테스트가 필요하며, 각 테스트에서는 플랫폼 사양을 충족하는 고유한 비주얼 및 카피의 변형이 요구됩니다. 브랜드 아이덴티티, 자산, 캠페인 디자인은 퍼포먼스 작업이 전개되는 기반으로서 계속해서 중요한 역할을 하고 있습니다. 이러한 요소들은 브랜드가 리브랜딩을 진행하거나, 제품을 출시하거나, 새로운 지역에 진출할 때도 꾸준히 수요가 유지되고 있습니다. 패키지 및 인쇄 디자인은 성장 속도가 완만하지만, 소비재, 명품, 제약 업계의 클라이언트에게는 여전히 복잡하고 고액의 보수가 요구되는 업무입니다. 이러한 프로젝트에서는 물리적 소재, 규제 정보, 매장 진열에 대한 치밀한 관리가 필요합니다. 이 업무는 단순한 템플릿으로는 쉽게 대체할 수 없습니다. 또한 브랜드, 제품, 생산 각 팀 간의 협업에도 의존하고 있습니다. 디지털 디자인 지원은 웹, 용도, 인터랙티브 자산을 관리함으로써 이러한 서비스 유형들을 연결해 줍니다.
모션 및 멀티미디어 디자인 시장은 2026-2031년 연평균 성장률(CAGR) 9.54%로 확대될 것으로 예측됩니다. 숏폼 동영상은 현재 소셜 플랫폼과 스트리밍 서비스 전반에서 주요 참여 유도 형식으로 자리 잡고 있습니다. 커넥티드 TV 광고, 쇼핑 기능이 포함된 동영상, 증강현실(AR)에 사용되는 모션 오버레이 등은 기존의 방송 광고를 넘어 서비스 기반을 확대되고 있습니다. 이 분야의 크리에이티브 디자인 서비스 시장 규모는 다양한 형식을 지원할 수 있는 동영상을 요구하는 클라이언트에 의해 뒷받침되고 있습니다. 실시간 렌더링을 통해 팀이 컨텐츠를 프레임 단위로 재제작할 필요가 없어지므로, 현지화 및 적응에 드는 비용을 절감할 수 있습니다. 또한, 브랜드가 웹, 앱, 인터랙티브 자산을 더 많이 관리하게 됨에 따라 디지털 디자인 지원도 더욱 광범위한 제작 스택을 지속적으로 뒷받침하고 있습니다.
2025년, 크리에이티브 에이전시 네트워크는 크리에이티브 디자인 서비스 시장 점유율의 42.63%를 차지했습니다. 이러한 대규모 네트워크 덕분에 단일 클라이언트와의 관계 내에서 전략, 제작, 미디어 기획 및 측정을 통합할 수 있게 되었습니다. 대기업의 구매 담당자들은 벤더 관리를 간소화하고 브랜드 거버넌스를 지원할 수 있기 때문에 통합된 책임 체계를 중요시하는 경우가 많습니다. 또한 대규모 네트워크는 소규모 스튜디오에서는 쉽게 재현할 수 없는 독자적인 데이터와 기술 플랫폼도 제공합니다. 클라이언트가 편집 작업, 패키징 또는 공간 디자인 분야에서 고도의 역량을 필요로 하는 상황에서는 전문 디자인 스튜디오가 여전히 중요한 역할을 수행하고 있습니다. 프리랜서 마켓플레이스는 전 세계 디자인 인력에 대한 온디맨드 접근을 제공함으로써, 비용과 시간을 중시하는 구매자의 요구를 충족시키고 있습니다.
온라인 디자인 플랫폼은 2026-2031년 연평균 성장률(CAGR) 9.63%를 나타낼 것으로 예측됩니다. 중견 기업 구매자들의 구독 서비스 도입과 AI를 활용한 제작 도구가 이러한 성장을 뒷받침하고 있습니다. 플랫폼은 기존에는 스튜디오나 구독 서비스 제공업체에 위탁되던 정기적인 업무를 수행할 수 있습니다. Figma는 2025년 4분기에 전년 동기 대비 40%의 매출 성장을 보고했는데, 이는 협업형 디자인 인프라에 대한 기업의 관심을 반영합니다. 크리에이티브 디자인 서비스 시장에는 플랫폼과 에이전시 모두에게 활약할 여지가 있습니다. 이는 대규모 클라이언트가 여전히 거버넌스, 전략 및 조율된 실행을 필요로 하기 때문입니다. 주요 경쟁적 영향은 차별화된 전략적 또는 전문적 역량 없이 표준화된 제작만 제공하는 제공업체에 가해지는 압박입니다. 플랫폼의 워크플로는 제품 개발 팀이나 마케팅 팀이 일상적인 협업을 더 쉽게 수행할 수 있도록 돕습니다. 또한 클라이언트가 공통 파일이나 재사용 가능한 구성 요소를 관리하는 데에도 도움이 됩니다. 전문 스튜디오는 장인 정신과 같은 전문 지식이나 보다 고도의 프로젝트에 중점을 둠으로써 이에 대응할 수 있습니다. 에이전시 네트워크는 크리에이티브 제작과 미디어, 데이터, 거버넌스 서비스를 결합함으로써 대응할 수 있습니다.
지역별 분석
북미는 2025년에 크리에이티브 디자인 서비스 시장의 36.73% 점유율을 차지했으며, 예측 기간 동안 계속해서 주요 지역 거점으로 자리매김할 것입니다. 이 지역에는 탄탄한 에이전시 생태계, 다수의 포춘 500대 기업 본사, 그리고 크리에이티브 워크플로우를 혁신하는 기술 플랫폼이 고도로 집중되어 있습니다. 미국은 업계 재편과 플랫폼 투자의 주요 거점이 되고 있습니다. 옴니콤은 2025년 11월 IPG 인수를 완료했습니다. WPP의 ‘WPP Open’에 대한 연간 3억 8,300만 달러 투자와 퍼블리시스의 21억 6,700만 달러 규모 LiveRamp 인수는 이 지역의 투자 규모를 반영하고 있습니다. 캐나다와 멕시코도 수요를 끌어올리고 있으며, 멕시코는 스페인어 컨텐츠 현지화를 위한 니어쇼어 거점으로서 그 역할을 점점 더 강화하고 있습니다.
유럽은 독일, 영국, 프랑스를 필두로 크리에이티브 디자인 서비스 시장에서 여전히 중요한 위치를 차지하고 있습니다. 광고비와 프리미엄 브랜드 카테고리가 브랜드 아이덴티티, 패키징, 캠페인 업무에 대한 수요를 뒷받침하고 있습니다. 영국에는 전문 스튜디오와 독립 대행사가 밀집해 있습니다. 독일의 제조업 경제는 프리미엄 패키징 및 제품 디자인에 대한 수요를 뒷받침하고 있습니다. 유럽 접근성법에 따라 2025년 6월부터 관련 디지털 제품에 대해 법적 구속력이 있는 접근성 요건이 도입되었습니다. 이에 따라 접근성을 고려한 디자인이 요구되면서 디지털 크리에이티브의 요건 범위가 확대되고 있습니다. 브라질과 아르헨티나를 필두로 한 남미에서도 현지 전자상거래 및 소셜 커머스 활동을 통해 수요가 확대되고 있습니다.
아시아태평양은 2026-2031년 연평균 성장률(CAGR) 10.11%를 나타낼 것으로 예측됩니다. 인도는 브랜드 구축 서비스에 대한 수요가 확대되고 있는 한편, 전 세계 아웃소싱 업무공급원 역할도 하고 있습니다. 중국에서는 Douyin, Tmall Live, WeChat에 맞춤화된 컨텐츠에 대한 국내 수요가 활발합니다. 한국은 디지털 인프라와 확립된 디자인 기준을 바탕으로 고품질 크리에이티브 서비스의 수출국으로서 역할을 수행하고 있습니다. 아시아태평양 전체의 크리에이티브 디자인 서비스 시장 규모는 이처럼 다양하면서도 상호 보완적인 수요원의 혜택을 받고 있습니다. 중동 및 아프리카는 여전히 초기 단계의 기회이지만, 사우디아라비아의 ‘비전 2030’이 브랜딩 및 커뮤니케이션 활동을 뒷받침하고 있습니다. 남아프리카공화국, 이집트, 나이지리아는 아프리카 대륙에서 확대되고 있는 브랜드 경제의 중요한 거점으로 자리 잡고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the creative design services market size is projected to expand from USD 52.25 billion in 2025 and USD 56.22 billion in 2026 to USD 82.85 billion by 2031, registering a CAGR of 8.06% between 2026 to 2031.
This report is Segmented by Service Type (Brand Identity and Assets, Social and Performance Creative, Packaging and Print Design, Digital Design Support, Campaign Design, and More), Platform (Creative Agency Networks, and More), Client Size (Large Enterprises, and More), Service Model (Project-Based Engagements, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Creative Design Services Market Trends and Insights
Rising Demand for Always-On Omnichannel Creative Refresh
Brands now manage storefronts, social channels, connected TV, retail media placements, and in-store digital screens simultaneously. The Creative Design Services Market benefits because each channel requires its own format, copy length, and visual hierarchy. Marketing teams that once planned 12 campaign cycles a year now manage many smaller refreshes within each quarter. A single campaign, therefore, creates more production work across the client relationship. Omnicom introduced its next-generation Omni platform in January 2026 to support production at scale and stated that the system can improve creative throughput by 25-55%. The shift makes continuous creative capacity more important than isolated campaign execution.
AI-Augmented Design Production Shortening Turnaround Times
Generative AI has reduced production time for template-based and variant-heavy assets by 30-50% in Omnicom's stated experience with its platform. Routine production is therefore moving toward AI-assisted workflows. Complex assignments involving new concepts, cultural context, or regulated content still require substantial human judgment. WPP invested GBP 300 million (USD 383 million) at the 2025 annual average exchange rate, each year in WPP Open. WPP and Adobe expanded their partnership in February 2026 to integrate Adobe Firefly Foundry into WPP Open for content trained on brands' own intellectual property. Providers that embed AI coordination into client workflows can generate more billable output without matching the growth in headcount.
In-Housing and Self-Serve Tools Pressuring Pricing
Brands increasingly treat internal creative teams as a strategic capability rather than merely a cost-cutting measure. More than 53% of the surveyed brands viewed their in-house creative teams as strategic partners in the ANA In-House Agency Forum Report. Generative AI also makes routine social graphics, email templates, and minor adaptations easier for internal teams to complete. This pressure is strongest for providers whose work is defined by volume and standard formats. It is less acute where a brief requires strategic concepts, specialized craft, or complex coordination. The Creative Design Services Market, therefore, faces tighter pricing for routine output as more work shifts to self-serve tools and internal teams.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce and Social Commerce Expanding Visual Asset Demand
- Brand Consistency Investment Across Distributed Digital Touchpoints
- Shortage of Motion, 3D, and AI Workflow Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Social and Performance Creative held 27.83% of the Creative Design Services Market share in 2025. Its position reflects sustained spending on paid social and performance advertising. Campaign optimization requires frequent testing, and each test calls for distinct visuals and copy variants that meet platform specifications. Brand Identity, Assets, and Campaign Design remain the foundations from which performance work is developed. They retain demand when brands rebrand, launch products, or enter new geographic areas. Packaging and Print Design is slower-growing, but it remains a complex, premium-fee activity for fast-moving consumer goods, luxury, and pharmaceutical clients. These assignments require close control of physical materials, regulatory information, and shelf presentation. That work cannot be easily replaced by a simple template. It also depends on coordination between brand, product, and production teams. Digital Design Support connects these service types by managing web, application, and interactive assets.
Motion and Multimedia Design is projected to expand at a 9.54% CAGR from 2026 to 2031. Short-form video is now a major engagement format across social platforms and streaming services. Connected TV advertising, shoppable video, and motion overlays used in augmented reality are widening the service base beyond conventional broadcast advertising. The Creative Design Services Market size for this activity is supported by clients that need adaptable video across formats. Real-time rendering can make localization and adaptation less expensive because teams do not need to reproduce content frame by frame. Digital Design Support also continues to support the broader production stack as brands manage more web, app, and interactive assets.
Creative Agency Networks held 42.63% of the Creative Design Services Market share in 2025. Their scale enables them to combine strategy, production, media planning, and measurement within a single client relationship. Enterprise buyers often value centralized accountability because it simplifies vendor management and supports brand governance. Large networks also provide proprietary data and technology platforms that smaller studios cannot easily replicate. Specialist Design Studios remain important where clients need deep capability in editorial work, packaging, or spatial design. Freelancer Marketplaces serve cost- and time-sensitive buyers by providing on-demand access to global design talent.
Online Design Platforms are projected to grow at a 9.63% CAGR from 2026 to 2031. Subscription adoption among mid-market buyers and AI-assisted production tools support this expansion. Platforms can absorb recurring work that was previously assigned to studios or subscription service providers. Figma reported 40% year-over-year revenue growth in the fourth quarter of 2025, reflecting enterprise interest in collaborative design infrastructure. The Creative Design Services Market has room for both platforms and agencies because larger clients still need governance, strategy, and coordinated execution. The main competitive effect is pressure on providers that offer standardized production without differentiated strategic or specialist capabilities. Platform workflows make routine collaboration easier for product and marketing teams. They can also help clients maintain common files and reusable components. Specialist studios can respond by emphasizing craft expertise and more demanding assignments. Agency networks can respond by combining creative delivery with media, data, and governance services.
Complete Report Scope:
- By Service Type
- Brand Identity and Assets
- Campaign Design
- Social and Performance Creative
- Packaging and Print Design
- Digital Design Support
- Motion and Multimedia Design
- By Platform
- Creative Agency Networks
- Specialist Design Studios
- Online Design Platforms
- Freelancer Marketplaces
- By Client Size
- Micro Businesses and Startups
- Small and Medium Enterprises
- Mid-market Enterprises
- Large Enterprises
- By Service Model
- Project-Based Engagements
- Retainer-Based Engagements
- Subscription Design Services
- DIY SaaS and Self-Serve Tools
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 36.73% of the Creative Design Services Market share in 2025 and remains the leading regional base through the forecast period. The region has a deep agency ecosystem, many Fortune 500 headquarters, and a high concentration of technology platforms changing creative workflows. The United States is the main hub for consolidation and platform investment. Omnicom completed its acquisition of IPG in November 2025. WPP's USD 383 million annual WPP Open investment, and Publicis's USD 2.167 billion LiveRamp acquisition also reflect the scale of investment in the region. Canada and Mexico add demand, with Mexico increasingly serving as a nearshore source for Spanish-language content adaptation.
Europe remains a significant part of the Creative Design Services Market, led by Germany, the United Kingdom, and France. Advertising spending and premium brand categories support demand for brand identity, packaging, and campaign work. The United Kingdom has a dense base of specialist studios and independent agencies. Germany's manufacturing economy supports demand for premium packaging and product design. The European Accessibility Act introduced enforceable accessibility requirements for relevant digital products from June 2025. This broadens the scope of digital creative briefs by requiring accessibility-ready design. South America, led by Brazil and Argentina, is also building demand through local e-commerce and social commerce activity.
Asia-Pacific is projected to expand at a 10.11% CAGR from 2026 to 2031. India is both a growing buyer of brand-building services and a source of supply for global outsourcing work. China has strong domestic demand for content tailored to Douyin, Tmall Live, and WeChat. South Korea's digital infrastructure and established design standards support its role as a premium creative services exporter. The Creative Design Services Market size across Asia-Pacific benefits from these different but reinforcing sources of demand. The Middle East and Africa remain earlier-stage opportunities, with Saudi Arabia's Vision 2030 supporting branding and communications work. South Africa, Egypt, and Nigeria serve as important hubs for the continent's expanding brand economy.
- WPP plc
- Omnicom Group Inc.
- Publicis Groupe S.A.
- Dentsu Group Inc.
- The Interpublic Group of Companies, Inc.
- Accenture plc
- Deloitte Touche Tohmatsu Limited
- Adobe Inc.
- Canva Pty Ltd
- Fiverr International Ltd.
- Upwork Inc.
- Cimpress plc
- IDEO LP
- Pentagram Design Limited
- Design Pickle LLC
- Wieden+Kennedy, Inc.
- VaynerMedia LLC
- crowdspring, LLC.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Always-On Omnichannel Creative Refresh
- 4.2.2 AI-Augmented Design Production Shortening Turnaround Times
- 4.2.3 E-commerce and Social Commerce Expanding Visual Asset Demand
- 4.2.4 Brand Consistency Investment Across Distributed Digital Touchpoints
- 4.2.5 Retail Media Asset Proliferation Raising Need for Modular Creative Systems
- 4.2.6 Accessibility and Localization Requirements Increasing Design Scope
- 4.3 Market Restraints
- 4.3.1 In-Housing and Self-Serve Tools Pressuring Pricing
- 4.3.2 Shortage of Motion, 3D, and AI Workflow Talent
- 4.3.3 Generative AI Copyright and Provenance Risk Delaying Approvals
- 4.3.4 Platform Format Volatility Increasing Rework and Asset Obsolescence
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Brand Identity and Assets
- 5.1.2 Campaign Design
- 5.1.3 Social and Performance Creative
- 5.1.4 Packaging and Print Design
- 5.1.5 Digital Design Support
- 5.1.6 Motion and Multimedia Design
- 5.2 By Platform
- 5.2.1 Creative Agency Networks
- 5.2.2 Specialist Design Studios
- 5.2.3 Online Design Platforms
- 5.2.4 Freelancer Marketplaces
- 5.3 By Client Size
- 5.3.1 Micro Businesses and Startups
- 5.3.2 Small and Medium Enterprises
- 5.3.3 Mid-market Enterprises
- 5.3.4 Large Enterprises
- 5.4 By Service Model
- 5.4.1 Project-Based Engagements
- 5.4.2 Retainer-Based Engagements
- 5.4.3 Subscription Design Services
- 5.4.4 DIY SaaS and Self-Serve Tools
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Qatar
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 WPP plc
- 6.4.2 Omnicom Group Inc.
- 6.4.3 Publicis Groupe S.A.
- 6.4.4 Dentsu Group Inc.
- 6.4.5 The Interpublic Group of Companies, Inc.
- 6.4.6 Accenture plc
- 6.4.7 Deloitte Touche Tohmatsu Limited
- 6.4.8 Adobe Inc.
- 6.4.9 Canva Pty Ltd
- 6.4.10 Fiverr International Ltd.
- 6.4.11 Upwork Inc.
- 6.4.12 Cimpress plc
- 6.4.13 IDEO LP
- 6.4.14 Pentagram Design Limited
- 6.4.15 Design Pickle LLC
- 6.4.16 Wieden+Kennedy, Inc.
- 6.4.17 VaynerMedia LLC
- 6.4.18 crowdspring, LLC.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and unmet-need assessment


