

|
시장보고서
상품코드
2118891
산업용 테이프 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Industrial Tapes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
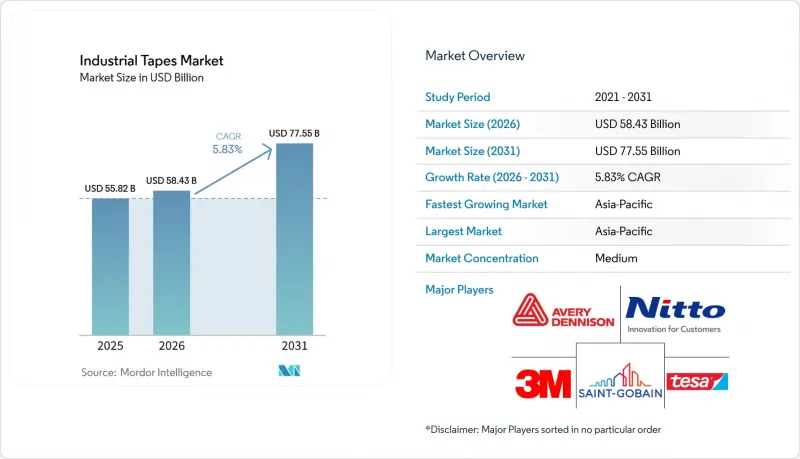
에 의하면, 산업용 테이프 시장은 2025년에 558억 2,000만 달러로 평가되었고, 2026년 584억 3,000만 달러에서 2031년까지 775억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.83%를 나타낼 전망입니다.
본 보고서는 접착제 유형별(아크릴, 고무, 실리콘 등), 제품별(덕트 테이프, 알루미늄 테이프, 필라멘트 테이프 등), 접착 기술별(감압 접착제, 용제계 접착제 등), 최종 이용 산업별(산업 제조, 자동차 등) 및 지역별(아시아태평양, 북미 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 산업용 테이프 시장 동향 및 인사이트
전기차 배터리 조립 및 열 관리 분야에서 산업용 테이프의 채택 확대
전기차 배터리 조립에서는 접착, 절연, 열 관리, 방화, 전자기 차폐, 압축 밀봉과 같은 분야에서 기능성 테이프에 대한 수요가 발생하고 있습니다. 이러한 용도에서는 제한된 배터리 팩 공간 내에서 여러 기능을 수행할 수 있는 소재가 요구됩니다. 헨켈은 2026년 5월, 열전도율 1.7 W/(m·K)의 실온 경화형 실리콘 프리 열 갭 필러 ‘Bergquist TGF 2030APS’를 출시했습니다. 또한 이 회사는 셀-투-팩 설계를 위해 열전도율 2 W/(m·K)의 폴리우레탄계 열전도성 접착제 ‘Loctite TLB 9270APS’도 발표했습니다. 셀-투-팩 설계에서는 개별 부품 수가 감소하기 때문에 테이프 선정에 있어 구조적 및 안전 측면에서의 책임이 더욱 무겁게 다가옵니다.
기계식 체결 부재의 대안으로서 경량 접착 솔루션에 대한 수요가 증가하고 있습니다.
각 제조업체는 특정 자동차 및 항공우주용 조립체에서 리벳, 나사, 용접 대신 테이프를 채택하고 있습니다. 테이프는 기계식 체결 부품에 수반되는 국부적인 응력 집중을 일으키지 않으면서 이종 재료를 접착할 수 있습니다. 2026년 ‘Automotive Engineering Expo’에서 테사(Tesa)는 기존의 수지 플러그를 대체하는 자동 구멍 메우기 시스템 ‘ProSeal’을 발표했습니다. 이 시스템을 통해 최대 80%의 경량화를 실현하여, 차량 1대당 평균 280g의 무게를 줄일 수 있습니다. 또한, 헨켈(Henkel)사는 2026년 5월, 차체(Body-in-White) 생산에서 아스팔트 시트를 대체할 수 있는 진동 감쇠 기능도 갖춘 ‘Teroson EP 52 시리즈’를 출시했습니다. 구조용 테이프 용도에 대한 공급업체 승인은 차량 개발 프로그램의 초기 단계에서 설계 사양을 확보한 제조업체의 입지를 강화하는 데 기여합니다.
원자재 가격 변동이 접착제 및 기판 비용에 영향을 미침
접착 테이프의 생산은 아크릴, 실리콘, 합성 고무, 용제, 필름 및 기타 원자재에 의존하고 있으며, 이러한 가격은 급격하게 변동할 가능성이 있습니다. 원료 공급 제약으로 인해 아크릴계 접착제, 실리콘 테이프, 합성고무 컴파운드 및 용제계 시스템의 비용이 상승할 가능성이 있습니다. 이러한 변동으로 인해 견적 기간이 단축되거나 컨버터의 자재 계획이 복잡해질 우려가 있습니다. 지역에 기반을 둔 중소규모 기업은 장기 공급 계약을 통해 원자재를 확보하는 능력이 제한적일 수 있습니다. 자재 가격이 급등하는 시기에는 운전 자금에 압박이 가해질 가능성이 있습니다. 이로 인해, 특히 표준 테이프 카테고리의 경우, 고객이 추가 공급을 요청하더라도 생산 능력 확대가 제한될 우려가 있습니다.
부문 분석
2025년, 아크릴계는 산업용 테이프 시장의 44.52%를 차지했습니다. 이러한 위상은 자외선 저항성, 기판과의 폭넓은 호환성, 그리고 수성 접착제 시스템에서의 사용을 반영합니다. 수성 아크릴계 소재는 유럽, 북미 및 일본에서 고용제 배합에서 벗어나려는 추세와 부합합니다. Lohmann사는 ASTM D 5470에 따라 시험된, 최대 2 W/(m*K)의 열전도율을 가진 열전도성 아크릴 전사 테이프 “DuploCOLL TC”를 제공합니다. 이러한 제품들은 과거 실리콘 배합과 밀접하게 연관되어 있던 용도에서도 아크릴계 시스템을 활용할 수 있음을 보여줍니다. 고무계 접착제는 그 정평이 난 성능과 비용 면에서의 우위가 여전히 중요하게 여겨지는 포장, 덕트 테이프 및 일반적인 유지보수 용도에서 계속해서 중요한 역할을 하고 있습니다.
실리콘 시장은 2031년까지 연평균 성장률(CAGR) 6.93%를 나타낼 것으로 예측됩니다. 실리콘은 전기차(EV) 배터리 모듈, 반도체 마스킹, 항공우주 용도 등 극한 온도 환경 하의 용도에 활용되고 있습니다. 실리콘계 제품은 성능 요구 사항이 아크릴계나 고무계 제품의 작동 범위를 초과하는 상황에서 사용됩니다. 폴더블 디스플레이, 웨어러블 기기, 센서 용도에서의 수요도 최종 용도 기반을 확대되고 있습니다. 폴리우레탄 및 핫멜트의 하이브리드 배합은 소규모 구조용 접착 및 자동차용 실링 용도를 뒷받침하고 있습니다. 산업용 테이프 업계에서는 단일 배합으로 모든 온도, 기판, 박리성, 내구성 요건을 충족시킬 수 없기 때문에 계속해서 여러 가지 접착제 화학 조성물이 요구되고 있습니다.
2025년, 덕트 테이프는 산업용 테이프 시장의 29.85% 점유율을 차지했습니다. 덕트 테이프는 건설, 난방·환기·공조(HVAC), 유지보수·수리 및 일반 산업 작업에서 여전히 널리 사용되고 있습니다. 그 유용성은 다양한 사용 조건 하에서의 인열 저항성, 밀착성 및 손으로 찢을 수 있는 특성에서 비롯됩니다. 이러한 특성 덕분에 많은 특수 테이프보다 더 광범위한 제품군에 대한 수요를 뒷받침하고 있습니다. 알루미늄 테이프는 HVAC, 단열, 항공우주용 덕트 등에서 계속해서 사용되고 있습니다. 필라멘트 테이프 또한 접착력뿐만 아니라 인장 보강이 요구되는 운송, 물류, 팔레타이징 분야에서 활용되고 있습니다.
접착제 전사 테이프 시장은 2031년까지 연평균 성장률(CAGR) 6.87%로 확대될 것으로 예측됩니다. 이 테이프의 접착제 필름 구조는 로봇을 통한 정밀한 도포를 가능하게 하여 기판 폐기물을 줄일 수 있습니다. 이는 전자기기, 화이트 바디 조립 및 의료기기 생산에 적합합니다. 3M의 접착제 전사 테이프 966NP는 ASTM E 595에 기반한 NASA의 저아웃가스 사양을 충족하며, 엄격한 환경 조건이 요구되는 항공우주 및 반도체 분야에 적합합니다. 또한, 3M은 전기적으로 박리 가능한 테이프 1100-050도 제공하고 있으며, 이 테이프는 전기적 자극을 통해 전도성 표면에서 박리되어 용제에 노출시키지 않고도 재작업이 가능합니다. 순환형 경제의 요구 사항이 중요성을 더해가는 가운데, 박리 가능한 형태는 수리를 전제로 한 제품 설계를 지원할 수 있습니다.
지역별 분석
아시아태평양은 2025년에 산업용 테이프 시장 점유율의 42.94%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 6.45%로 성장할 것으로 전망됩니다. 이 지역에는 배터리 제조, 소비자 가전제품 조립, 반도체 제조 및 자동차 생산 역량이 집중되어 있습니다. 중국은 자동차 및 전자기기 생산 규모가 크기 때문에 수요를 주도하고 있습니다. 중국에서는 2024년에 702만 대의 신에너지차가 생산되어 전년 대비 35.8% 증가했습니다. 일본과 한국은 특수 테이프 생산 및 고성능 소재 분야에서 중요한 위치를 차지하고 있습니다. 또한, 지역 내 공급망이 다양화됨에 따라 베트남, 태국, 인도네시아에서도 전자기기 조립 생산 능력이 확대되고 있습니다.
북미에서는 항공우주, 자동차, 방위, 생명과학 제조 분야에서 고부가가치 수요가 뒷받침되고 있습니다. 오대호 산업 지대에는 자동차 OEM 제조업체, 공급업체 및 배터리 조립 사업이 집중되어 있습니다. 환경 및 산업 안전 관련 규제로 인해 제조 거점에서는 수성 및 무용제 테이프의 도입이 촉진되고 있습니다. 멕시코에서는 미국 및 캐나다와 연계된 자동차 및 전자기기 생산을 통해 수요가 확대되고 있습니다. 자동화에 대한 투자도 감압 접착제 및 전사 테이프의 활용을 뒷받침하고 있습니다. 제조업체들이 자동화 기술을 활용하여 생산 안정성을 높이고 수작업 조립 공정을 줄이는 분야에서 산업용 테이프 시장은 성장 여지가 있습니다.
유럽은 지속가능성 요건과 프리미엄 OEM의 사양에 따라 형성된 고부가가치 제품 구성이 특징입니다. 독일, 프랑스, 영국은 자동차, 산업, 전자 분야 용도에서 여전히 중요한 수요 거점으로 자리 잡고 있습니다. 독일 접착제 산업협회(IVK) 보고서에 따르면, 순환 경제를 지향하는 제품 개발에서 박리 가능, 재활용 가능, 그리고 바이오 접착제 형태에 대한 수요가 증가하고 있습니다. 남미 시장은 규모가 비교적 작으며, 브라질과 아르헨티나에서는 자동차, 포장, 건설 분야 수요가 시장을 지탱하고 있습니다. 중동 및 아프리카에서는 인프라 구축 사업이 건설, HVAC(냉난방·환기·공조), 그리고 유지보수용 테이프에 대한 장기적인 수요를 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the industrial tapes market was valued at USD 55.82 billion in 2025 and is estimated to grow from USD 58.43 billion in 2026 to reach USD 77.55 billion by 2031, at a CAGR of 5.83% during the forecast period (2026-2031).
This report is Segmented by Adhesive Type (Acrylic, Rubber, Silicone, and More), Product (Duct Tapes, Aluminum Tapes, Filament Tapes, and More), Adhesive Technology (Pressure-Sensitive Adhesives, Solvent-Based Adhesives, and More), End-Use Industry (Industrial Manufacturing, Automotive, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Tapes Market Trends and Insights
Increasing Adoption of Industrial Tapes in Electric Vehicle Battery Assembly and Thermal Management
Electric vehicle battery assembly is creating demand for functional tapes across bonding, insulation, thermal management, fire protection, electromagnetic shielding, and compressive sealing. These applications require materials that can perform several functions within a limited battery-pack space. Henkel introduced Bergquist TGF 2030APS in May 2026 as a silicone-free thermal gap filler with 1.7 W/(m*K) conductivity and room-temperature cure. The company also introduced Loctite TLB 9270APS, a polyurethane-based thermally conductive adhesive with 2 W/(m*K) conductivity for cell-to-pack designs. As cell-to-pack designs reduce the number of discrete components, tape selection carries more structural and safety responsibility.
Growing Demand for Lightweight Bonding Solutions as Alternatives to Mechanical Fasteners
Manufacturers are using tapes in place of rivets, screws, and welds in selected automotive and aerospace assemblies. Tapes can bond dissimilar materials without the localized stress concentrations associated with mechanical fasteners. At Automotive Engineering Expo 2026, tesa presented its ProSeal automated hole-cover system, which replaces conventional resin plugs. The system can save an average of 280 g per vehicle through weight reduction of up to 80%. Henkel also launched the Teroson EP 52 Series in May 2026 to replace bitumen sheets in body-in-white production while providing vibration damping. Supplier approvals for structural tape applications can strengthen the position of manufacturers that secure design specifications early in a vehicle program.
Volatility in Raw Material Prices Affecting Adhesive and Backing Material Costs
Adhesive tape production depends on acrylic, silicone, synthetic rubber, solvents, films, and other inputs whose prices can change quickly. Feedstock constraints can raise costs for acrylic adhesives, silicone tapes, synthetic-rubber compounds, and solvent-based systems. These changes can shorten quotation periods and complicate material planning for converters. Smaller regional companies may have less ability to secure feedstock through longer supply contracts. Their working capital can come under pressure during periods of higher material prices. This can limit capacity expansion even when customers are seeking additional supply, especially in standard tape categories.
Other drivers and restraints analyzed in the detailed report include:
- Rising Miniaturization of Electronic Devices Driving Demand for High-Precision Tapes
- Growing Preference for Low-VOC and Environmentally Sustainable Adhesive Tape Solutions
- Stringent Environmental and Regulatory Compliance Requirements, Including REACH and RoHS
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acrylic accounted for 44.52% of the industrial tapes market share in 2025. Their position reflects UV resistance, broad compatibility with substrates, and use in water-based adhesive systems. Water-based acrylic materials align with the shift away from higher-solvent formulations in Europe, North America, and Japan. Lohmann offers DuploCOLL TC thermally conductive acrylic transfer tapes with thermal conductivity of up to 2 W/(m*K), tested under ASTM D 5470. These products show that acrylic systems can serve applications once more closely associated with silicone formulations. Rubber adhesives continue to support packaging, duct tape, and general maintenance applications, where their familiar performance and cost position remain relevant.
Silicone is forecast to grow at a 6.93% CAGR through 2031. It serves extreme-temperature settings such as EV battery modules, semiconductor masking, and aerospace applications. Silicone systems are used where performance requirements exceed the operating range of many acrylic or rubber products. Demand from foldable screens, wearables, and sensor applications also broadens their end-use base. Polyurethane and hot-melt hybrid formulations support smaller structural-bonding and automotive-sealing uses. The industrial tapes industry continues to require several adhesive chemistries because no single formulation meets every temperature, substrate, release, and durability requirement.
Duct tapes held 29.85% of the industrial tapes market share in 2025. They remain common in construction, heating, ventilation, and air conditioning (HVAC), maintenance, repair, and general industrial work. Their utility comes from tear resistance, conformability, and hand-tearability across varied operating conditions. These characteristics support demand across a wider product range than many specialized tapes. Aluminum tapes retain use in HVAC, thermal insulation, and aerospace ducting. Filament tapes also support transportation, logistics, and palletizing, where tensile reinforcement is required with adhesion.
Adhesive transfer tapes are forecast to expand at a 6.87% CAGR through 2031. Their adhesive-film construction supports accurate robotic application and can reduce backing material waste. This suits electronics, body-in-white assembly, and medical-device production. 3M Adhesive Transfer Tape 966NP meets NASA low-outgassing specifications under ASTM E 595 for demanding aerospace and semiconductor environments. 3M also offers Electrically Debondable Tape 1100-050, which releases from conductive surfaces under electrical stimulus and supports rework without solvent exposure. Debondable formats can support repair-oriented product designs as circularity requirements become more important.
Complete Report Scope:
- By Adhesive Type
- Acrylic
- Rubber
- Silicone
- Other Adhesive Types
- By Product
- Duct Tapes
- Aluminum Tapes
- Filament Tapes
- Adhesive Transfer Tapes
- Other Products
- By Adhesive Technology
- Pressure-Sensitive Adhesives
- Solvent-Based Adhesives
- Water-Based Adhesives
- Hot Melt Adhesives
- By End-Use Industry
- Industrial Manufacturing
- Automotive
- Electrical and Electronics
- Building and Construction
- Healthcare
- Food and Beverage
- Aerospace and Defense
- Transportation and Logistics
- Other End-use Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 42.94% of the industrial tapes market share in 2025 and is forecast to grow at a 6.45% CAGR through 2031. The region combines battery manufacturing, consumer-electronics assembly, semiconductor fabrication, and automotive capacity. China is driving demand because of its scale in vehicle and electronics production. China produced 7.02 million new energy vehicles in 2024, up 35.8% from the prior year. Japan and South Korea have important positions in specialty tape production and high-performance materials. Vietnam, Thailand, and Indonesia are also adding electronics assembly capacity as supply chains diversify within the region.
North America supports high-value demand from aerospace, automotive, defense, and life sciences manufacturing. The Great Lakes industrial belt concentrates automotive original equipment manufacturers, suppliers, and battery assembly operations. Environmental and worker-safety frameworks encourage water-based and solvent-free tape adoption in manufacturing corridors. Mexico adds demand through automotive and electronics production integrated with the United States and Canada. Automation investment also supports pressure-sensitive and adhesive-transfer tape use. The industrial tapes market has scope to grow where manufacturers use automated applications to improve production consistency and reduce manual assembly steps.
Europe is characterized by a high-value product mix shaped by sustainability requirements and premium OEM specifications. Germany, France, and the United Kingdom remain important demand centers for automotive, industrial, and electronics applications. Industrieverband Klebstoffe (IVK) reported that demand for debondable, recyclable, and bio-based adhesive formats is rising within circular-economy-oriented product development. South America is smaller, with Brazil and Argentina supported by automotive, packaging, and construction demand. In the Middle-East and Africa, infrastructure programs support longer-term demand for construction, HVAC, and maintenance tapes.
- 3M
- Advance Tapes International
- American Biltrite Inc.
- Avery Dennison Corporation
- CCT Coating and Converting Technologies, LLC
- Henkel AG and Co. KGaA
- IPG
- LINTEC Corporation
- Lohmann
- Nitto Denko Corporation
- ORAFOL Europe GmbH
- Saint-Gobain
- Scapa
- Shurtape Technologies, LLC
- tesa SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for Lightweight Bonding Solutions as Alternatives to Mechanical Fasteners
- 4.2.2 Increasing Adoption of Industrial Tapes in Electric Vehicle Battery Assembly and Thermal Management
- 4.2.3 Rising Miniaturization of Electronic Devices Driving Demand for High-Precision Tapes
- 4.2.4 Growing Preference for Low-VOC and Environmentally Sustainable Adhesive Tape Solutions
- 4.2.5 Increasing Automation in Manufacturing and Robotic Tape Application Processes
- 4.3 Market Restraints
- 4.3.1 Volatility in Raw Material Prices Affecting Adhesive and Backing Material Costs
- 4.3.2 Stringent Environmental and Regulatory Compliance Requirements, Including REACH and RoHS
- 4.3.3 Competition from Mechanical Fastening and Alternative Bonding Technologies in Heavy-Duty Applications
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Adhesive Type
- 5.1.1 Acrylic
- 5.1.2 Rubber
- 5.1.3 Silicone
- 5.1.4 Other Adhesive Types
- 5.2 By Product
- 5.2.1 Duct Tapes
- 5.2.2 Aluminum Tapes
- 5.2.3 Filament Tapes
- 5.2.4 Adhesive Transfer Tapes
- 5.2.5 Other Products
- 5.3 By Adhesive Technology
- 5.3.1 Pressure-Sensitive Adhesives
- 5.3.2 Solvent-Based Adhesives
- 5.3.3 Water-Based Adhesives
- 5.3.4 Hot Melt Adhesives
- 5.4 By End-Use Industry
- 5.4.1 Industrial Manufacturing
- 5.4.2 Automotive
- 5.4.3 Electrical and Electronics
- 5.4.4 Building and Construction
- 5.4.5 Healthcare
- 5.4.6 Food and Beverage
- 5.4.7 Aerospace and Defense
- 5.4.8 Transportation and Logistics
- 5.4.9 Other End-use Industries
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Advance Tapes International
- 6.4.3 American Biltrite Inc.
- 6.4.4 Avery Dennison Corporation
- 6.4.5 CCT Coating and Converting Technologies, LLC
- 6.4.6 Henkel AG and Co. KGaA
- 6.4.7 IPG
- 6.4.8 LINTEC Corporation
- 6.4.9 Lohmann
- 6.4.10 Nitto Denko Corporation
- 6.4.11 ORAFOL Europe GmbH
- 6.4.12 Saint-Gobain
- 6.4.13 Scapa
- 6.4.14 Shurtape Technologies, LLC
- 6.4.15 tesa SE
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


