|
시장보고서
상품코드
2118922
천연두 치료 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Smallpox Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
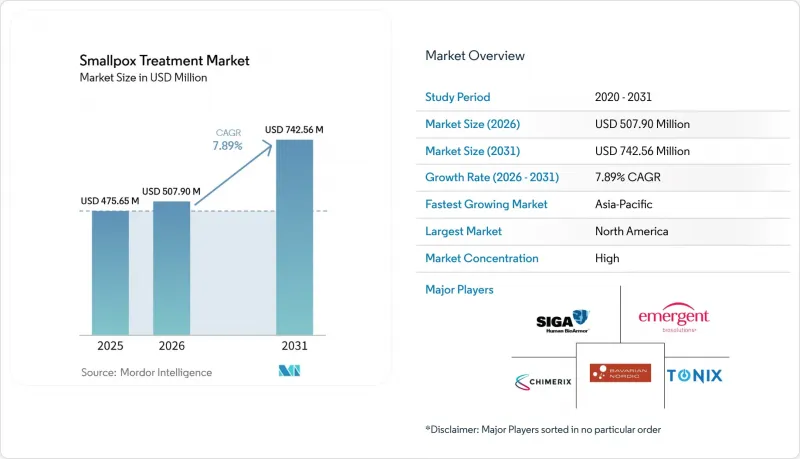
천연두 치료 시장 규모는 2025년에 4억 7,565만 달러로 평가되었고, 2026년 5억 790만 달러에서 2031년까지 7억 4,256만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 7.89%를 나타낼 전망입니다.
본 보고서는 제품별(항바이러스제, 백신), 질환 유형별(대천연두, 소천연두, 기타), 투여 경로별(경구, 비경구), 최종 사용자별(공중보건 기관, 병원, 군, 기타), 유통 채널별(정부 비축, 약국), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 천연두 치료 시장 동향 및 인사이트
정부의 비축 및 의료 대책용 조달
비축 갱신 계약은 천연두 치료 시장에서 계속해서 가장 큰 수익원으로 자리 잡고 있습니다. 2025년 3월, SIGA Technologies는 2024년 7월 경구용 TPOXX와 관련하여 1억 1,300만 달러 규모의 수주에 이어, BARDA 19C 계약에 따라 정맥 주사용 TPOXX에 대해 2,600만 달러 규모의 수주를 확보했습니다. 2026년 6월, 에머전트 바이오솔루션즈(Emergent BioSolutions)는 ACAM2000 백신, 부속품 및 희석제의 보충 로트에 대해 5,270만 달러 규모의 계약 변경을 수주했습니다. 미국 국립과학아카데미는 2022 회계연도부터 2026 회계연도에 걸쳐 전략적 국가 비축(SNS) 조달 지출의 3분의 2 가까이가 탄저균 및 천연두 대책 능력 유지에 할당될 것으로 전망했습니다. 이러한 요건으로 인해 이미 ‘동물 규정’, 품질 기준 및 비축 적격 기준을 충족하는 공급업체가 우대받았습니다.
Mpox 유행 이후의 오르토포크스바이러스 대책
2022년에 발생한 다국적 Mpox 유행은 많은 정부가 오르토포크스 바이러스에 대비하는 방식을 재평가하는 계기가 되었습니다. 각국 정부는 천연두에 대한 의료 대책(MCM)을, 좁은 범위의 생물테러 시나리오에 국한되지 않는 광범위한 용도로 활용 가능한 자산으로 인식하는 경향을 강화하고 있습니다. 바바리안 노르딕(Bavarian Nordic)은 2025년 ‘공공 대비’ 부문 매출이 31억 500만 덴마크 크로네(약 4억 5,000만 달러)에 달했다고 보고했으며, 여기에는 해당 회사의 MVA-BN 백신 플랫폼에 대한 정부 수요도 포함되어 있습니다. 2024년 4월에 체결된 MVA-BN에 관한 EU 전략 비축 계약은 6,500만 유로(약 7,000만 달러) 규모로, 회원국 간의 조율된 조달 경로 확립에 기여했습니다. 백신 개발 및 비축에 관한 조사에서도 유럽 내에서 보다 협력적인 대비 체계로의 전환이 부각되었습니다. 한국의 ‘2024년부터 2028년까지의 국가 백신 비축 중장기 계획’에서는 대비가 장기적인 국가 계획의 일부가 되고 있음이 나타났습니다. 이처럼 구매자층이 확대됨에 따라, 천연두 발생이 실제로 없는 상황에서도 천연두 치료제 시장은 지지를 받았습니다.
근절된 질병과 최소한의 일상적 임상 수요
천연두 바이러스는 어떤 인간 집단에서도 유행하고 있지 않기 때문에 모든 구매는 예방적인 성격입니다. 각국 정부는 심각하지만 불확실한 사태에 대비해 자금을?出하고 있지만, 다른 공중보건상의 우선순위와 자금 경쟁을 벌이게 되어 예산에 부담이 될 가능성이 있습니다. WHO의 천연두 백신 비상 비축은 자체 비축분을 유지하지 않는 국가들을 지원하기 위한 것이며, 전 세계 비축 현황의 불균형도 반영하고 있습니다. 일상적인 임상 수요가 없기 때문에 천연두 치료제 시장은 지속적인 정책적 의지와 재고를 유지하려는 정부의 의지에 의존하고 있습니다.
부문 분석
2025년에는 항바이러스제가 60.34%의 점유율을 차지했으며, 미국, 캐나다, 유럽 및 일본의 국가 비축분에서 테코빌리마트가 주도적인 위치를 차지했습니다. 이 부문은 노출 후 치료에 대한 수요의 혜택을 받고 있습니다. FDA는 2018년에 경구용 천연두 치료제 ‘TPOXX’를 승인했으며, 2022년에는 캡슐을 복용할 수 없는 환자를 위한 정맥 주사제를 승인했습니다. 공중보건 당국은 ‘애니멀 룰(Animal Rule)’에 따라 2차 선택 약물로 브린시도포빌을 비축하고 있습니다. 한편, 시도포빌의 경우 정맥 주사 투여나 신독성에 대한 우려가 있음에도 불구하고, 의료 기관의 프로토콜에서 여전히 중요한 위치를 차지하고 있습니다.
백신은 가장 빠르게 성장하는 제품군이 될 것으로 예측되며, 2031년까지 연평균 성장률(CAGR)은 8.82%를 나타낼 것으로 전망됩니다. 2025년 3월, FDA는 동결건조 제제인 JYNNEOS를 승인하여 장기 보존 적합성이 향상되었습니다. BARDA는 Bavarian Nordic사와의 기존 10년 공급 계약에 따라 1억 4,360만 달러 규모의 옵션을 행사했으며, 2026년에 납품될 예정입니다. ACAM2000은 계속해서 미국의 전략적 국가 비축 물자의 일부이며, 2024년에 mpox에 대한 FDA의 승인 범위가 확대되었습니다. 한편, 일본의 LC16m8 및 Moderna사의 mRNA-1769 후보 물질은 향후 공급 다각화를 뒷받침할 것입니다.
2025년 시점에서 Variola Major는 천연두 치료제 시장 규모의 68.36%를 차지했으며, 2031년까지의 연평균 성장률(CAGR)도 8.23%로 가장 높은 성장세를 보일 것으로 예측됩니다. 이 유형은 역사적으로 가장 높은 질병 부담을 야기하고 생물학적 방어에 대한 우려가 가장 명확하기 때문에 대비 계획에서 중점을 두고 있습니다. 과거 치사율은 15%에서 35% 사이였으나, 이에 비해 Variola Minor의 치사율은 1% 미만이었습니다. 동물 모델 연구에서는 관련 오르토포크스 바이러스를 대체 모델로 사용하고 있으며, 개발 및 조달은 더 심각한 위협 시나리오에 초점을 맞추었습니다.
이 세분화의 나머지 부분은 소천연두, 출혈성 천연두, 악성 천연두 및 변형 천연두가 차지하고 있습니다. 출혈성 및 악성 천연두는 역사적으로 매우 높은 치사율을 보였지만, 발생 빈도가 극히 낮기 때문에 수요량 모델링에서 그 역할은 제한적이었습니다. 변형 천연두는 백신 접종을 받은 군인이나 의료 종사자 등 부분적인 면역력을 가진 사람들에게서 비전형적인 임상 증상을 보일 가능성이 있습니다. 면역률이 낮은 집단에서 대규모 감염이 발생할 경우, 정맥 주사용 항바이러스제, 지지 요법용 제품 및 다양한 치료 형태에 대한 수요가 증가할 가능성이 있습니다.
지역별 분석
2025년, 북미는 43.21%의 점유율을 차지했습니다. 미국은 전략적 국가 비축(Strategic National Stockpile), BARDA(생물 의학 연구·개발국)의 개발 자금, 그리고 프로젝트 바이오쉴드(Project BioShield)의 조달 권한을 통해 지역적 수요를 뒷받침했습니다. 백신 및 항바이러스제에 대한 다년 구매 계약은 기존 공급업체들에게 예측 가능한 수요 기반을 마련해 주었습니다. 캐나다는 다년간의 의료 대책 협정을 공식적으로 체결한 반면, 멕시코는 범미보건기구(PAHO)의 지침에 따라 비교적 소규모 시장에 머물렀습니다.
아시아태평양은 2026-2031년 연평균 성장률(CAGR) 8.76%를 나타낼 것으로 예측됩니다. 일본은 TEPOXX를 승인하고, 생물 테러 대응 체계의 일환으로 LC16m8을 사용했습니다. SIGA사는 2026년 1월, 다년간 계약에 따라 아시아태평양 고객으로부터 1,300만 달러 상당의 경구용 TPOXX 주문을 받았습니다. 한국의 2024년부터 2028년까지의 백신 비축 계획에서는 사태에 따른 구매에서 보다 장기적인 대비로 전환하는 방향이 제시되었습니다.
유럽에서는 rescEU 및 HERA를 통해 조정된 비축 모델을 구축하는 한편, 독일, 프랑스, 영국에서는 각국의 프로그램을 유지했습니다. Bavarian Nordic사는 EU의 전략적 비축용 MVA-BN 주문을 확보하여 지역의 백신 공급 능력을 뒷받침했습니다. 프랑스는 2026년 5월, mpox 적응증이 철회된 후에도 테코비리마트(tecovirimat)가 천연두, 우두 및 왁시니아의 합병증에 대해 계속 승인되어 있음을 확인했습니다. 중동 및 아프리카에서는 공식적인 비축 체계 구축이 여전히 초기 단계에 머물러 있었으나, 브라질과 아르헨티나는 범미보건기구(PAHO)의 틀에 따라 비축 능력을 정비했습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the smallpox treatment market size was valued at USD 475.65 million in 2025 and is estimated to grow from USD 507.90 million in 2026 to reach USD 742.56 million by 2031, at a CAGR of 7.89% during the forecast period (2026-2031).
This report is Segmented by Product (Antiviral Drugs, Vaccines), Disease Type (Variola Major, Variola Minor, Other), Route of Administration (Oral, Parenteral), End User (Public Health Agencies, Hospitals, Military, Other), Distribution Channel (Government Stockpiles, Pharmacies), and Geography (North America, Europe, Asia-Pacific, MEA, S. America). The Market Forecasts are Provided in Terms of Value (USD).
Global Smallpox Treatment Market Trends and Insights
Government Stockpiling and Medical-Countermeasure Procurement
Stockpile refresh contracts remained the largest revenue driver for the smallpox treatment market. In March 2025, SIGA Technologies received a USD 26 million order for IV TPOXX under its BARDA 19C contract, following a USD 113 million oral TPOXX order in July 2024. In June 2026, Emergent BioSolutions received a USD 52.7 million contract modification for ACAM2000 vaccine, ancillaries, and diluent replacement lots. The National Academies stated that anthrax and smallpox capacity sustainment was expected to account for nearly two-thirds of Strategic National Stockpile procurement spending during FY2022 through FY2026. These requirements favored suppliers that already met Animal Rule, quality, and stockpile qualification standards.
Orthopoxvirus Preparedness After Mpox Outbreaks
The 2022 multi-country mpox outbreak changed how many governments assessed orthopoxvirus preparedness. Governments increasingly positioned smallpox medical countermeasures as assets with applications beyond a narrow bioterrorism scenario. Bavarian Nordic reported DKK 3,105 million (approximately USD 450 million) in Public Preparedness revenue in 2025, including government demand for its MVA-BN vaccine platform. Bavarian Nordic's April 2024 EU strategic reserve contract for MVA-BN was valued at EUR 65 million (approximately USD 70 million) and helped establish a coordinated procurement route for member states. Research on vaccine development and stockpiling also highlighted the shift toward more coordinated preparedness arrangements in Europe. South Korea's National Vaccine Stockpiling Mid- to Long-Term Plan for 2024 to 2028 indicated that preparedness was becoming part of longer-term national planning. This broader buyer base supported the smallpox treatment market even without an active smallpox event.
Eradicated Disease and Minimal Routine Clinical Demand
The variola virus does not circulate in any human population, making all purchases precautionary. Governments fund preparedness for a severe but uncertain event, which can strain budgets as other public health priorities compete for funding. The WHO Smallpox Vaccine Emergency Stockpile supports countries that do not maintain independent reserves and also reflects uneven global coverage. With no routine clinical demand, the smallpox treatment market depends on sustained policy commitment and government willingness to maintain inventory.
Other drivers and restraints analyzed in the detailed report include:
- Reduced Population Immunity After Routine Smallpox Vaccination Ended
- Animal Rule Pathway for Approval Without Human Efficacy Trials
- Limited Human Efficacy Evidence for Approved Therapeutics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Antiviral drugs held a 60.34% share in 2025, led by tecovirimat in national stockpiles across the United States, Canada, Europe, and Japan. The segment benefits from demand for treatment after exposure. The FDA approved TPOXX for oral smallpox treatment in 2018 and approved an intravenous formulation in 2022 for patients unable to take capsules. Public health authorities also hold brincidofovir as a second-line option under the Animal Rule, while cidofovir remains relevant in institutional protocols despite intravenous administration and renal toxicity concerns.
Vaccines are projected to be the fastest-growing product group, registering an 8.82% CAGR through 2031. In March 2025, the FDA approved a freeze-dried JYNNEOS formulation, improving its suitability for long-term storage. BARDA exercised USD 143.6 million in options under Bavarian Nordic's existing 10-year supply contract, with deliveries planned for 2026. ACAM2000 remains part of the United States Strategic National Stockpile and received expanded FDA approval for mpox in 2024, while Japan's LC16m8 and Moderna's mRNA-1769 candidate support future supply diversity.
Variola Major held 68.36% of the smallpox treatment market size in 2025 and is also forecast to register the fastest 8.23% CAGR through 2031. Preparedness plans focus on this form because it historically caused the highest disease burden and presents the clearest biodefense concern. Its historical case fatality rate ranged from 15% to 35%, compared with below 1% for Variola Minor. Animal model studies use related orthopoxvirus surrogates, keeping development and procurement focused on the more severe threat scenario.
Variola Minor, hemorrhagic smallpox, malignant smallpox, and modified smallpox make up the remainder of this segmentation. Hemorrhagic and malignant forms historically had very high fatality rates, but their rarity limited their role in volume modeling. Modified smallpox may present atypical clinical features in partially immune people, including vaccinated military personnel and healthcare workers. A large event in a low-immunity population could increase demand for intravenous antivirals, supportive care products, and multiple therapeutic formats.
Complete Report Scope:
- By Product
- Antiviral Drugs
- Tecovirimat
- Brincidofovir
- Cidofovir
- Others
- Vaccines
- ACAM2000
- JYNNEOS (MVA-BN)
- LC16m8
- Antiviral Drugs
- By Disease Type
- Variola Major
- Variola Minor
- Hemorrhagic Smallpox
- Malignant (Flat) Smallpox
- Modified Smallpox
- By Route of Administration
- Oral
- Parenteral
- By End User
- Hospitals & Clinics
- Ambulatory Care Centers
- Public Health Agencies
- Military & Defense Agencies
- Homecare
- By Distribution Channel
- Government & Strategic Stockpiles
- Hospital Pharmacies
- Specialty Pharmacies
- Retail Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held a 43.21% share in 2025. The United States supported regional demand through the Strategic National Stockpile, BARDA development funding, and Project BioShield procurement authority. Multi-year purchase agreements for vaccines and antivirals created a predictable demand base for established suppliers. Canada formalized multi-year medical countermeasure arrangements, while Mexico remained a smaller market aligned with Pan American Health Organization guidance.
Asia-Pacific is forecast to grow at a CAGR of 8.76% from 2026 to 2031. Japan approved TEPOXX and used LC16m8 within its bioterrorism response framework. SIGA received a USD 13 million oral TPOXX order from an Asia-Pacific customer in January 2026 under a multi-year agreement. South Korea's 2024 to 2028 vaccine stockpiling plan indicated a shift from event-based purchasing to longer-term preparedness.
Europe developed a coordinated reserve model through rescEU and HERA while retaining national programs in Germany, France, and the United Kingdom. Bavarian Nordic secured MVA-BN orders for the EU strategic reserve, supporting regional vaccine capacity. France confirmed in May 2026 that tecovirimat remained authorized for smallpox, cowpox, and vaccinia complications after the mpox indication was withdrawn. The Middle East and Africa remained at an earlier stage in formal stockpile development, while Brazil and Argentina built capacity in line with Pan American Health Organization frameworks.
- Bavarian Nordic
- Bharat Biotech International Limited
- BioFactura, Inc.
- BioNTech
- Cangene Corporation
- Chimerix, Inc.
- Dynavax Technologies
- Elusys Therapeutics, Inc.
- Emergent Bio Solutions
- General Dynamics Information Technology, Inc.
- GlaxoSmithKline
- Inovio Pharmaceuticals, Inc.
- KM Biologics Co., Ltd.
- Merck
- Moderna
- Pfizer
- Sanofi
- SIGA Technologies, Inc.
- Tonix Pharmaceuticals
- Vaxart, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Stockpiling and Medical-Countermeasure Procurement
- 4.2.2 Expansion of Orthopoxvirus Preparedness After Mpox Outbreaks
- 4.2.3 Reduced Population Immunity After Routine Smallpox Vaccination Ended
- 4.2.4 Animal-Rule Pathway Enabling Approval Without Human Efficacy Trials
- 4.2.5 Dual-Mechanism Need to Manage Tecovirimat Resistance
- 4.2.6 National Diversification of Strategic Stockpiles Beyond the United States
- 4.3 Market Restraints
- 4.3.1 Eradicated Disease and Minimal Routine Clinical Demand
- 4.3.2 Limited Human Efficacy Evidence for Approved Therapeutics
- 4.3.3 High Cost and Long Lead Times for Stockpile Rotation
- 4.3.4 Low Resistance Barrier and Sparse Variola-Specific Surveillance
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Antiviral Drugs
- 5.1.1.1 Tecovirimat
- 5.1.1.2 Brincidofovir
- 5.1.1.3 Cidofovir
- 5.1.1.4 Others
- 5.1.2 Vaccines
- 5.1.2.1 ACAM2000
- 5.1.2.2 JYNNEOS (MVA-BN)
- 5.1.2.3 LC16m8
- 5.1.1 Antiviral Drugs
- 5.2 By Disease Type
- 5.2.1 Variola Major
- 5.2.2 Variola Minor
- 5.2.3 Hemorrhagic Smallpox
- 5.2.4 Malignant (Flat) Smallpox
- 5.2.5 Modified Smallpox
- 5.3 By Route of Administration
- 5.3.1 Oral
- 5.3.2 Parenteral
- 5.4 By End User
- 5.4.1 Hospitals & Clinics
- 5.4.2 Ambulatory Care Centers
- 5.4.3 Public Health Agencies
- 5.4.4 Military & Defense Agencies
- 5.4.5 Homecare
- 5.5 By Distribution Channel
- 5.5.1 Government & Strategic Stockpiles
- 5.5.2 Hospital Pharmacies
- 5.5.3 Specialty Pharmacies
- 5.5.4 Retail Pharmacies
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 Bavarian Nordic A/S
- 6.3.2 Bharat Biotech International Limited
- 6.3.3 BioFactura, Inc.
- 6.3.4 BioNTech SE
- 6.3.5 Cangene Corporation
- 6.3.6 Chimerix, Inc.
- 6.3.7 Dynavax Technologies Corporation
- 6.3.8 Elusys Therapeutics, Inc.
- 6.3.9 Emergent BioSolutions Inc.
- 6.3.10 General Dynamics Information Technology, Inc.
- 6.3.11 GlaxoSmithKline plc
- 6.3.12 Inovio Pharmaceuticals, Inc.
- 6.3.13 KM Biologics Co., Ltd.
- 6.3.14 Merck & Co., Inc.
- 6.3.15 Moderna, Inc.
- 6.3.16 Pfizer Inc.
- 6.3.17 Sanofi
- 6.3.18 SIGA Technologies, Inc.
- 6.3.19 Tonix Pharmaceuticals Holding Corp.
- 6.3.20 Vaxart, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment