

|
시장보고서
상품코드
2118969
습진 치료제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Eczema Therapeutics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
습진 치료제 시장 규모는 2025년에 235억 6,000만 달러로 평가되었습니다. 2026년에 251억 6,000만 달러에 달하고, 2031년까지 375억 8,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년에 걸쳐 CAGR 8.36%로 성장할 전망입니다.
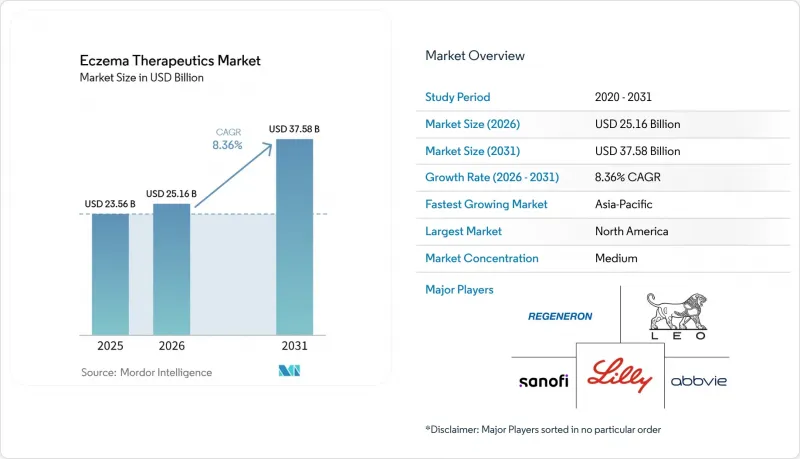
본 보고서는 습진의 유형(아토피 피부염, 접촉성 피부염, 지루성 피부염 등), 약물 분류(코르티코스테로이드, 칼시뉴린 억제제 등), 투여 경로(외용, 경구, 비경구),연령대(소아, 성인, 고령자), 유통 채널(병원, 소매, 온라인 약국), 지역(북미 등)별로 분류되어 있습니다. 예측치는 금액(달러)으로 표시되어 있습니다.
세계의 습진 치료제 시장 동향 및 인사이트
진단 및 약물 치료를 받는 습진 환자 수 증가
진단을 받고 약물 치료를 받고 있는 환자층은 유병률 데이터가 시사하는 것보다 빠른 속도로 확대되고 있습니다. 피부과 전문의에 대한 접근성 개선, 디지털 선별 검사, 그리고 1차 진료 기관을 통한 지도로 인해 더 많은 환자가 처방 치료를 받고 있습니다. 많은 국가에서는 여전히 아토피 피부염에 관한 체계적인 역학 데이터가 부족하여, 아시아태평양(APAC) 및 사하라 이남 아프리카의 대상 환자 수가 과소평가되었을 가능성이 있습니다. 2025년 ‘세계 질병 부담(GBD)’ 데이터 분석에 따르면, 연령 조정된 아토피 피부염의 유병률 및 장애 부담은 아시아태평양의 고소득 국가에서 가장 높은 것으로 나타났습니다. 따라서 도시화의 진전과 의료 서비스에 대한 투자로 인해, 더 높은 부가가치의 의료 서비스를 지원할 수 있는 시장에서 수요가 증가하고 있습니다. 이에 따라 습진 및 아토피 피부염 치료 시장은 처방용 외용제 및 전신용 약물 수요 기반을 더욱 확대하게 될 것입니다.
표적형 바이오의약품 및 저분자 치료제의 확대
습진 및 아토피 피부염 치료제의 승인 속도는 2024년부터 2026년에 걸쳐 가속화되었습니다. FDA는 2024년 9월, 12세 이상 환자의 중등도에서 중증 아토피 피부염에 대해 일라이 릴리(Eli Lilly)사의 레브리키즈맙을 승인했습니다. 이어 2024년 12월에는 갈데르마사의 네모리주맙이 아토피 피부염에 대한 FDA 최초의 IL-31 수용체 길항제로 승인되었습니다. 이러한 제품들을 통해 처방 의사는 증상이나 질환의 경과에 맞추어 치료법을 유연하게 선택할 수 있게 되었습니다. 사노피는 COAST 1, COAST 2 및 SHORE 임상시험에서 암리테리맙의 3상 임상시험에서 양호한 결과가 나왔다고 보고했으며, 2026년 하반기에 전 세계 각국에서 승인을 신청할 예정입니다. IL-13, IL-31, OX40L 및 관련 염증 경로에 작용하는 제품이 등장함에 따라, 습진 치료제 시장은 단일 치료 접근법에 대한 의존도가 점차 낮아지고 있습니다.
높은 연간 치료비와 보험사 측의 이용 제한
듀필마브의 미국 내 연간 정가는 3만 5,000달러를 초과합니다. 2024년 동료 심사를 거친 연구에 따르면, 아토피 피부염 처방에 대한 보험 적용 지연의 가장 빈번하게 보고된 이유는 사전 승인(prior authorization)이었습니다. 동 연구에서는 생물학적 제제와 관련된 지연이 3주 이상 지속될 가능성이 있다는 사실도 밝혀졌습니다. 미국의 주요 보험사는 생물학적 제제나 JAK 억제제의 급여를 승인하기 전에 환자에게 국소 코르티코스테로이드나 칼시뉴린 억제제의 사용을 의무화하는 것이 일반적입니다. 유럽에서도 보험 급여 결정에는 입찰, 가격 협상, 비용 대비 효과 요건 등이 관여하고 있습니다. 이러한 규제 때문에 임상적 필요성이 명백한 경우에도 습진 및 아토피 피부염 치료 시장에서의 신제품 도입이 지연될 가능성이 있습니다.
부문별 분석
2025년, 아토피 피부염은 습진 및 아토피 피부염 치료 시장의 82.32% 점유율을 차지했으며, 2031년까지 연평균 성장률(CAGR) 10.28%로 확대될 것으로 예측됩니다. 이러한 규모는 높은 유병률과 다른 습진 아형에 비해 비용이 높은 표적 치료법을 이용하기 쉬운 상황을 반영하고 있습니다. 소아용 승인, 생물학적 제제의 추가, 그리고 아시아태평양(APAC) 및 동유럽에서의 진단 능력 향상 등이 이러한 성장을 뒷받침하고 있습니다.
접촉성 피부염은 일반적으로 제네릭 외용제로 치료되므로, 브랜드 의약품에 의한 혁신은 비교적 적은 상황입니다. 지루성 피부염 및 한포성 습진의 경우, 외용 코르티코스테로이드 및 항진균제의 병용 요법에 대한 처방 수요가 계속해서 예상됩니다. ‘기타 습진’으로 분류되는 만성 수부 습진의 경우, 2025년 9월 델고시티닙 크림이 출시되어 미국에서 전용 치료 옵션이 제공되게 되었습니다.
2025년 습진 치료제 시장 규모에서 약제 분류별로는 코르티코스테로이드가 29.76%를 차지했습니다. 이 약제들은 친숙하고 널리 구할 수 있으며, 다른 치료법과 병용되기 때문에 경증부터 중증에 이르기까지 여전히 표준적인 외용제 선택지로 자리 잡고 있습니다. 이러한 높은 매출액은 주로 판매량이 많음을 반영한 것이며, 장기적인 치료 성과에서의 우월성을 나타내는 것은 아닙니다. 네모리주맙은 외용 코르티코스테로이드 및/또는 칼시뉴린 억제제와의 병용이 승인되어 있어, 기존 외용 제품이 여전히 종합적인 치료의 일부임을 보여줍니다. 칼시뉴린 억제제는 2031년까지 연평균 성장률(CAGR) 14.21%를 나타낼 것으로 예측됩니다. 이러한 성장은 제네릭 의약품의 가격 하락, 아시아태평양(APAC)에서의 접근성 확대, 그리고 눈꺼풀 및 안면 습진에 대한 스테로이드 절약 요법으로의 사용을 반영한 것입니다.
지역별 분석
2025년, 북미는 습진 및 아토피 피부염 치료 시장 규모의 41.23%를 차지했습니다. 이 지역은 전문 피부과 제품에 대한 높은 지출, 민간 보험에 의한 급여, 그리고 확립된 전문 약국 서비스의 혜택을 받고 있습니다. 캐나다와 멕시코도 수요를 견인하고 있으나, 캐나다의 공적 보험 환급 제도는 미국에 비해 생물학적 제제의 사용을 제한할 가능성이 있습니다. 따라서 북미는 계속해서 습진 및 아토피 피부염 치료 시장의 주요 상업적 기반으로 자리 잡고 있습니다.
유럽은 독일, 프랑스, 영국의 환급 제도에 힘입어 시장 규모 측면에서 2위를 차지하고 있습니다. NICE, Haute Autorite de Sante, Gemeinsamer Bundesausschuss는 새로운 피부과용 의약품에 대해 체계적인 심사 절차를 제공합니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 12.36%로 확대될 것으로 예측됩니다. 일본에서는 규제 당국의 승인 후 듀필루맙과 JAK 억제제가 건강보험 제도를 통해 환급되므로, 생물학적 제제의 매출이 두드러지게 증가하고 있습니다. 중국에서는 생물학적 제제의 사용이 아직 초기 단계에 있지만, 승인 및 보험 적용을 통해 접근성이 확대되고 있어 큰 기회가 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the eczema therapeutics market size is projected to be USD 23.56 billion in 2025, USD 25.16 billion in 2026, and reach USD 37.58 billion by 2031, growing at a CAGR of 8.36% from 2026 to 2031.
This report is Segmented by Type of Eczema (Atopic Dermatitis, Contact Dermatitis, Seborrheic Dermatitis, and More), Drug Class (Corticosteroids, Calcineurin Inhibitors, and More), Route of Administration (Topical, Oral, Parenteral), Age Group (Pediatric, Adults, Geriatric), Distribution Channel (Hospital, Retail, Online Pharmacies), and Geography (North America and More). Forecasts are in Value (USD).
Global Eczema Therapeutics Market Trends and Insights
Rising Diagnosed and Drug-Treated Eczema Population
The diagnosed and drug-treated patient pool is expanding faster than prevalence data alone suggests. Better access to dermatologists, digital screening, and primary-care guidance is bringing more patients into prescription treatment. Many countries still lack systematic atopic dermatitis epidemiology, which means the addressable population in APAC and sub-Saharan Africa may be undercounted. A 2025 analysis of Global Burden of Disease data found that age-standardized atopic dermatitis prevalence and disability burden were highest in high-income Asia-Pacific settings. Urban growth and healthcare investment are therefore increasing demand in markets that can support higher-value care. This gives the eczema therapeutics market a broader base for prescription topicals and systemic medicines.
Expansion of Targeted Biologics and Small-Molecule Therapies
The approval pace for eczema treatments accelerated from 2024 through 2026. The FDA approved Eli Lilly's lebrikizumab in September 2024 for moderate-to-severe atopic dermatitis in patients aged 12 years and older. Galderma's nemolizumab followed in December 2024 as the first FDA-approved IL-31 receptor antagonist for atopic dermatitis. These products give prescribers more ways to match treatment to symptoms and disease patterns. Sanofi reported positive Phase 3 results for amlitelimab across the COAST 1, COAST 2, and SHORE studies and plans global submissions in the second half of 2026. The eczema therapeutics market is becoming less dependent on one treatment approach as products act on IL-13, IL-31, OX40L, and related inflammatory pathways.
High Annual Cost and Payer Utilization Controls
The annual U.S. list price of dupilumab exceeds USD 35,000. Prior authorization was the most frequently reported reason for insurance coverage delays for atopic dermatitis prescriptions in a 2024 peer-reviewed study. The same study found that biologic-related delays could extend beyond 3 weeks. Major U.S. payers commonly require patients to use topical corticosteroids or calcineurin inhibitors before covering biologics or JAK inhibitors. In Europe, reimbursement decisions also involve tendering, pricing negotiations, and cost-effectiveness requirements. These controls can delay new products in the eczema therapeutics market, even where clinical need is clear.
Other drivers and restraints analyzed in the detailed report include:
- Broader Pediatric and Adolescent Label Coverage
- Increasing Specialist and Specialty-Pharmacy Treatment Intensity
- Long-Term Safety, Persistence, and Delivery Barriers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Atopic dermatitis held 82.32% of the eczema therapeutics market share in 2025 and is forecast to expand at a 10.28% CAGR through 2031. Its scale reflects high prevalence and a greater ability to use higher-cost targeted therapies than other eczema subtypes. Pediatric approvals, added biologics, and stronger diagnosis in APAC and Eastern Europe support its growth.
Contact dermatitis is usually treated with generic topical medicines and has drawn less branded innovation. Seborrheic dermatitis and dyshidrotic eczema continue to produce prescribing demand for topical corticosteroids and antifungal combinations. Chronic hand eczema, included within other eczema types, received a dedicated U.S. option with the launch of delgocitinib cream in September 2025.
Corticosteroids accounted for 29.76% of the eczema therapeutics market size by drug class in 2025. They remain the standard topical option across mild and severe disease because they are familiar, broadly available, and used with other treatments. Their large revenue position is mainly a volume measure rather than proof of superior long-term outcomes. Nemolizumab is approved for use with topical corticosteroids and or calcineurin inhibitors, showing that established topical products remain part of systemic care. Calcineurin inhibitors are projected to grow at a 14.21% CAGR through 2031. Their growth reflects lower generic prices, wider access in APAC, and use as steroid-sparing options for eyelid and facial eczema.
Complete Report Scope:
- By Type of Eczema
- Atopic Dermatitis
- Contact Dermatitis
- Seborrheic Dermatitis
- Dyshidrotic Eczema
- Others (Nummular Eczema, Chronic Hand Eczema)
- By Drug Class
- Corticosteroids
- Calcineurin Inhibitors
- PDE4 Inhibitors
- JAK Inhibitors
- IL-4 and IL-13 Inhibitors
- IL-31 Inhibitors
- Antibiotics and Antiseptics
- Systemic Immunosuppressants
- Others (Antihistamines and Other Eczema Therapies)
- By Route of Administration
- Topical
- Oral
- Parenteral
- By Age Group
- Pediatric
- Adults
- Geriatric
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies and Drug Stores
- Online Pharmacies
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 41.23% of the eczema therapeutics market size in 2025. The region benefits from high spending on specialty dermatology products, private-payer coverage, and established specialty-pharmacy services. Canada and Mexico add demand, although public reimbursement in Canada can limit biologic use relative to the United States. North America, therefore, remains the leading commercial base for the eczema therapeutics market.
Europe is the second-largest regional contributor, supported by reimbursement systems in Germany, France, and the United Kingdom. NICE, Haute Autorite de Sante, and Gemeinsamer Bundesausschuss provide structured review paths for newer dermatology medicines. Asia-Pacific is expected to expand at a 12.36% CAGR through 2031. Japan has meaningful biologic revenue because its health insurance system reimburses dupilumab and JAK inhibitors after regulatory approval. China has a large opportunity because biologic use is still at an early stage, and access is widening through approvals and insurance coverage.
- Abbvie
- Almirall
- Amgen
- Arcutis Biotherapeutics, Inc.
- Astellas Pharma
- Bayer
- Bristol-Myers Squibb
- Dermavant Sciences Ltd.
- Eli Lilly and Company
- Galderma
- Incyte
- Kyowa Kirin
- Leo Pharma
- Novartis
- Organon
- Otsuka
- Pfizer
- Regeneron Pharmaceuticals
- Sanofi
- UCB
- Viatris
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diagnosed and Drug-Treated Eczema Population
- 4.2.2 Expansion of Targeted Biologics and Small-Molecule Therapies
- 4.2.3 Broader Pediatric and Adolescent Label Coverage
- 4.2.4 Increasing Specialist and Specialty-Pharmacy Treatment Intensity
- 4.2.5 Biomarker-Led Sequencing of Immune Pathways
- 4.2.6 Home-Administration and Tele-Dermatology Refill Models
- 4.3 Market Restraints
- 4.3.1 High Annual Cost and Payer Utilization Controls
- 4.3.2 Long-Term Safety Warnings for Systemic Immunomodulators
- 4.3.3 Treatment Persistence Erosion from Itch Relief and Skin-Clearance Mismatch
- 4.3.4 Cold-Chain and Injection-Training Friction in Emerging Markets
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type of Eczema
- 5.1.1 Atopic Dermatitis
- 5.1.2 Contact Dermatitis
- 5.1.3 Seborrheic Dermatitis
- 5.1.4 Dyshidrotic Eczema
- 5.1.5 Others (Nummular Eczema, Chronic Hand Eczema)
- 5.2 By Drug Class
- 5.2.1 Corticosteroids
- 5.2.2 Calcineurin Inhibitors
- 5.2.3 PDE4 Inhibitors
- 5.2.4 JAK Inhibitors
- 5.2.5 IL-4 and IL-13 Inhibitors
- 5.2.6 IL-31 Inhibitors
- 5.2.7 Antibiotics and Antiseptics
- 5.2.8 Systemic Immunosuppressants
- 5.2.9 Others (Antihistamines and Other Eczema Therapies)
- 5.3 By Route of Administration
- 5.3.1 Topical
- 5.3.2 Oral
- 5.3.3 Parenteral
- 5.4 By Age Group
- 5.4.1 Pediatric
- 5.4.2 Adults
- 5.4.3 Geriatric
- 5.5 By Distribution Channel
- 5.5.1 Hospital Pharmacies
- 5.5.2 Retail Pharmacies and Drug Stores
- 5.5.3 Online Pharmacies
- 5.5.4 Other Distribution Channels
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 AbbVie Inc.
- 6.3.2 Almirall, S.A.
- 6.3.3 Amgen Inc.
- 6.3.4 Arcutis Biotherapeutics, Inc.
- 6.3.5 Astellas Pharma Inc.
- 6.3.6 Bayer AG
- 6.3.7 Bristol Myers Squibb Company
- 6.3.8 Dermavant Sciences Ltd.
- 6.3.9 Eli Lilly and Company
- 6.3.10 Galderma S.A.
- 6.3.11 Incyte Corporation
- 6.3.12 Kyowa Kirin Co., Ltd.
- 6.3.13 LEO Pharma A/S
- 6.3.14 Novartis AG
- 6.3.15 Organon & Co.
- 6.3.16 Otsuka Pharmaceutical Co., Ltd.
- 6.3.17 Pfizer Inc.
- 6.3.18 Regeneron Pharmaceuticals, Inc.
- 6.3.19 Sanofi
- 6.3.20 UCB S.A.
- 6.3.21 Viatris Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment


