

|
시장보고서
상품코드
2118974
니트로셀룰로오스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Nitrocellulose - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
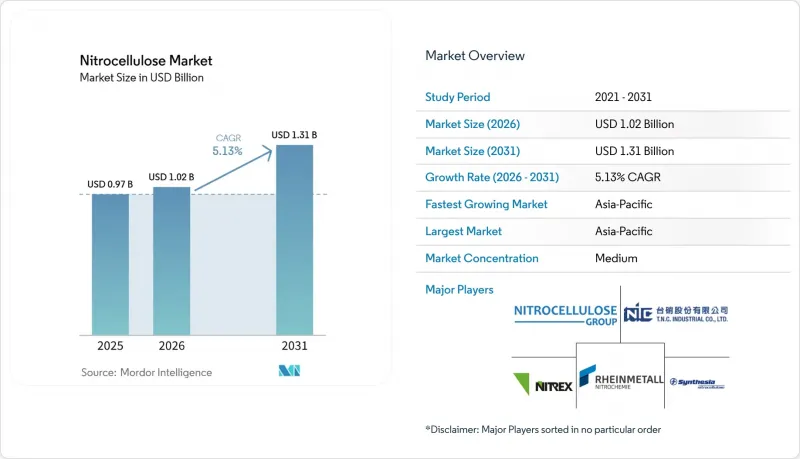
니트로셀룰로오스 시장은 2025년에 9억 7,000만 달러 규모로 평가되었습니다. 2026년 10억 2,000만 달러에서 2031년까지 13억 1,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 5.13%를 나타낼 전망입니다.
본 보고서는 등급(공업용 등급, 의약품용 등급, 특수 등급), 용도(인쇄 잉크, 자동차용 도료 등), 최종 이용 산업(페인트 및 코팅, 인쇄·포장, 의약품 및 헬스케어 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 니트로셀룰로오스 시장 동향 및 인사이트
산업용도 전반에 걸친 고광택·속건성 코팅에 대한 수요 증가
니트로셀룰로오스는 산업용 래커 시스템에서 용제의 신속한 방출, 자가 레벨링에 의한 필름 형성, 그리고 고광택 마감을 실현합니다. 자동차 재도장 공장, 가구 공장, 금속 표면 처리 업체들은 이러한 특성을 활용하여 도포, 취급 및 다음 제조 공정까지의 시간을 단축하고 있습니다. 건조 주기가 단축됨에 따라 경화 장비를 추가하거나 바닥 면적을 확대하지 않고도 기존 근무 시간 내에 생산 라인이 더 많은 작업을 완료할 수 있게 됩니다. 인도의 자동차 수리 도장 사업은 특히 신속한 수리 작업이 요구되는 분야에서 2031년까지 산업용 등급 재료에 대한 수요 기반을 제공합니다. 미국의 표면 코팅 요건은 제품 사양에 영향을 미치며, 배합 제조업체가 규정을 준수하는 용제 혼합물을 사용하도록 유도하고 있습니다. 수성 시스템에서 동일한 공정에서 동등한 처리 능력, 마감 품질 및 실용적인 건조 속도를 달성할 수 없는 경우, 니트로셀룰로오스 시장은 혜택을 받게 됩니다.
플렉소 및 그라비아 인쇄용 잉크에서 니트로셀룰로오스 사용 확대
니트로셀룰로오스는 접착력, 광택 및 용제의 빠른 증발을 촉진하기 때문에 용제형 그라비아 및 플렉소 인쇄 잉크에서 필름 형성용 바인더로 널리 사용되고 있습니다. 이러한 특성은 식품 및 소비재의 연포장에 사용되는 비흡수성 소재인 이축연신 폴리프로필렌(BOPP)(BOPP), 폴리에틸렌 테레프탈레이트(PET) 및 폴리아미드 필름에서 특히 유용합니다. 고속 인쇄 라인에서는 안정적인 필름 형성이 요구되며, 바인더의 변경은 인쇄 성능과 생산 설정 모두에 영향을 미칠 수 있습니다. 중국, 인도, 동남아시아에는 대규모 포장 필름 생산 거점이 있어, 이로 인해 해당 지역의 잉크 수요는 견고한 수익 기반을 구축하고 있습니다. 또한, 니트로셀룰로오스 시장은 유럽에서도 서로 다른 요구 사항에 직면하고 있으며, 이 지역에서는 수성 잉크 및 자외선(UV) 경화형 잉크의 사용이 확대되고 있습니다. 독일의 ‘인쇄 잉크 규정’이 2026년에 시행됨에 따라 식품 접촉용 잉크에서 특정 니트로셀룰로오스 유래 바인더의 사용이 제한될 예정이므로, 지역별 독자적인 배합 개발이 더욱 필요해지고 있습니다.
니트로셀룰로오스의 취급, 보관, 운송에 관한 엄격한 안전 요건
‘위험물의 국제 도로 운송에 관한 유럽 협정(ADR) 2025’에 따르면, 니트로셀룰로오스 용액은 UN 2059로 제3류 인화성 액체에 분류되어 엄격한 운송 조건이 부과됩니다. 건조된 고체 니트로셀룰로스는 UN 0340 또는 UN 0341로 분류되어 제1류 폭발물로 지정되어 있으며, 더 엄격한 관리가 요구됩니다. 허가된 운송, 사전 통지, 경로 제한 및 안전한 취급으로 인해 배송 비용이 증가하고, 현실적인 운송 거리가 제한될 가능성이 있습니다. 대규모 통합 생산자는 대량 생산을 통해 안전 인프라 비용을 분산시킬 수 있지만, 소규모 생산자는 톤당 규정 준수 비용이 더 높아집니다. 2024년 후베이성 라오허커우(Laohekou)의 니트로셀룰로오스 제조 공장에서 발생한 사고는 공정상의 안전 위험이 여전히 존재함을 여실히 보여주었습니다. 감독 체제가 강화되면서 운영 요건이 추가됨에 따라, 니트로셀룰로오스 시장에서는 산업용 등급공급이 더욱 부족해질 가능성이 있습니다.
부문별 분석
2025년에는 용제형 코팅, 인쇄 잉크, 자동차 수리용 도료, 가죽 마감재가 주도하면서 산업용 등급이 매출의 54.38%를 차지했습니다. 니트로셀룰로오스 시장의 산업용 등급 구매자들은 확립된 코팅 및 잉크 제품 라인을 위해 안정적인 납품 가격, 신뢰할 수 있는 점도, 그리고 안정적인 공급을 원합니다. 니트로셀룰로오스 업계는 기존 생산 공정에 적합한 대량 생산 제품을 통해 이러한 수요에 부응하고 있습니다. 이러한 광범위한 용도 기반 덕분에 산업용 등급은 매출의 중심을 계속 차지하고 있지만, 동시에 공급업체를 포장, 코팅, 마감 제품의 생산량 변동과 연결시키고 있습니다. 따라서 생산자는 지역별 수요 및 제품 사양의 변화에 대응하면서 신뢰할 수 있는 산업용 등급공급을 확보해야 합니다.
특수 등급은 의약품 첨가제 및 고순도 화장품 용도를 주축으로 2031년까지 연평균 성장률(CAGR) 5.83%를 나타낼 것으로 예측됩니다. 이러한 용도의 구매자들은 순도 인증, 로트 간 점도 안정성, 그리고 관리된 제조 공정을 요구합니다. 니트로셀룰로오스 막은 진단용 횡류 분석법을 뒷받침하는 반면, 특정 서방형 정제의 코팅이나 매니큐어에는 특수 등급이 요구됩니다. 의약품 등급은 무균성, 순도 및 규제 요건이 엄격하기 때문에 더 높은 이익률을 가져옵니다. 인증된 공급원이 제한적이라는 점은 공급 집중 위험을 높이고, 장기 구매 계약을 촉진할 가능성이 있습니다.
지역별 분석
아시아태평양은 2025년에 매출의 43.81%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.84%로 성장할 것으로 전망됩니다. 중국에는 산둥성, 장쑤성, 절강성에 생산 거점이 있습니다. 이 공급 거점은 국내 도료 및 잉크 제조업체와 동남아시아 및 라틴아메리카 전역의 수출 고객에게 제품을 공급하며, 니트로셀룰로오스 시장에서 아시아태평양의 입지를 강화하고 있습니다. 인도는 포장, 인쇄, 목재용 도료, 가죽 가공 분야의 중요한 수요 거점인 반면, 일본은 정밀 도료 및 고품질 가구용 마감재 수요를 뒷받침하고 있습니다. 인도는 중국산 니트로셀룰로오스 수입에 대해 반덤핑 관세를 부과하고 있으며, Nitrex Chemicals India사는 국내 및 수출 수요에 대응하기 위해 자가디아에서의 생산 능력을 확대되고 있습니다.
북미 수요는 자동차 수리용 도료, 캐비닛 및 바닥재용 마감재, 연포장용 인쇄 잉크에 의해 지탱되고 있으며, 주택 리모델링 시장이 캐비닛용 마감 래커 수요를 뒷받침하고 있습니다. 유럽에서는 식품 접촉용 잉크에 대한 규제가 강화되고 있는 반면, 일부 생산 능력은 에너지용 등급의 소재로 전환되고 있습니다. EU의 REACH 규정 및 독일의 인쇄 잉크 조례로 인해 공급업체와 배합 업체는 배합 재검토 및 규정 준수 대응 작업을 수행해야 합니다.
남미, 중동 및 아프리카는 여전히 규모는 작지만 수요가 확대되고 있는 지역입니다. 이 지역들의 니트로셀룰로오스 시장은 수입 및 현지 도료·잉크 제조업의 발전에 크게 의존하고 있습니다. 브라질과 멕시코는 포장, 가구 생산, 산업 용도료를 통해 남미 수요를 지탱하고 있으며, 라틴아메리카에서는 목재용 도료의 용도 확대가 가장 빠르게 진행되고 있습니다. 사우디아라비아와 남아프리카공화국은 중동 및 아프리카의 주요 수요 거점이며, 장식용 도료, 인쇄용 잉크, 가죽 마감재가 수입을 주도하고 있습니다. 현지 생산 규모가 제한적이고 인프라 제약으로 인해 1인당 소비량은 세계 평균보다 낮습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the nitrocellulose market was valued at USD 0.97 billion in 2025 and is estimated to grow from USD 1.02 billion in 2026 to reach USD 1.31 billion by 2031, at a CAGR of 5.13% during the forecast period (2026-2031).
This report is Segmented by Grade (Industrial Grade, Pharmaceutical Grade, and Specialty Grade), Application (Printing Inks, Automotive Paints, and More), End-Use Industry (Paints and Coatings, Printing and Packaging, Pharmaceuticals and Healthcare, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Nitrocellulose Market Trends and Insights
Growing Demand for High-Gloss and Fast-Drying Coatings Across Industrial Applications
Nitrocellulose provides fast solvent release, self-leveling film formation, and a high-gloss finish in industrial lacquer systems. Auto-refinish shops, furniture plants, and metal finishers use these properties to reduce the time between application, handling, and the next manufacturing step. Shorter drying cycles allow lines to complete more work within an existing shift without adding curing equipment or expanding floor space. Automotive refinish activity in India provides a demand base for industrial-grade material through 2031, particularly where repair work must be completed quickly. U.S. surface-coating requirements influence product specifications and have encouraged formulators to use compliant solvent blends. The nitrocellulose market benefits when waterborne systems cannot deliver comparable throughput, finish quality, and practical drying speed in the same operation.
Increasing Use of Nitrocellulose in Flexographic and Gravure Printing Inks
Nitrocellulose is widely used as a film-forming binder in solvent-based gravure and flexographic inks because it supports adhesion, gloss, and rapid solvent evaporation. These characteristics are particularly useful on Biaxially Oriented Polypropylene (BOPP), Polyethylene Terephthalate (PET), and polyamide films, which are non-absorbent materials used in flexible food and consumer-goods packaging. High-speed print lines need stable film formation, and a change in binder can affect both print performance and production settings. China, India, and Southeast Asia have large packaging-film production bases, which gives regional ink demand a substantial revenue base. The nitrocellulose market also faces a different requirement in Europe, where water-based and Ultraviolet (UV)-cured alternatives are gaining use. Germany's Printing Ink Ordinance took effect in 2026 and restricts certain nitrocellulose-derived binders in food-contact inks, making separate regional formulations more necessary.
Stringent Safety Requirements for the Handling, Storage, and Transportation of Nitrocellulose
The European Agreement concerning the International Carriage of Dangerous Goods by Road (ADR) 2025 classifies nitrocellulose solution under UN 2059 as a Class 3 flammable liquid with strict transport conditions. Dry solid nitrocellulose falls under UN 0340 or UN 0341 and is classified as a Class 1 explosive, requiring more demanding controls. Licensed transport, advance notification, route restrictions, and secure handling can increase delivered costs and limit viable transport distances. Large integrated producers can spread the cost of safety infrastructure across higher volumes, while smaller producers face higher compliance costs per ton. A 2024 incident at a nitrocellulose workshop in Laohekou, Hubei Province, highlighted continuing process-safety risks. The nitrocellulose market may see tighter industrial-grade availability when greater oversight adds operating requirements.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Premium Wood Coatings and Furniture Finishes
- Growing Preference for Fast-Curing Coating Systems to Improve Manufacturing Efficiency
- Increasing Competition from Alternative Resins such as Acrylics and Polyurethanes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial grade held 54.38% of revenue in 2025, supported by solvent-based coatings, printing inks, automotive refinish paints, and leather finishes. Industrial grade buyers in the nitrocellulose market seek delivered-price discipline, reliable viscosity, and consistent supply for established coating and ink lines. The nitrocellulose industry serves this demand through large-volume products that match existing production processes. Its wide application base keeps industrial grade central to revenue, but also links suppliers to changes in packaging, coating, and finishing output. Producers, therefore, need dependable industrial supply while managing shifts in regional demand and product specifications.
Specialty grade is forecast to grow at a 5.83% CAGR through 2031, led by pharmaceutical excipients and high-purity cosmetic applications. Buyers in these uses require purity certification, stable lot-to-lot viscosity, and controlled manufacturing practices. Nitrocellulose membranes support diagnostic lateral-flow assays, while selected controlled-release tablet coatings and nail lacquers require specialized grades. Pharmaceutical grade earns higher margins because sterility, purity, and regulatory requirements are demanding. Limited qualified supply can increase supply-concentration risk and encourage longer-term purchasing agreements.
Complete Report Scope:
- By Grade
- Industrial Grade
- Pharmaceutical Grade
- Specialty Grade
- By Application
- Printing Inks
- Automotive Paints
- Wood Coatings
- Leather Finishes
- Nail Varnishes
- Other Applications
- By End-Use Industry
- Paints and Coatings
- Printing and Packaging
- Pharmaceuticals and Healthcare
- Personal Care and Cosmetics
- Leather and Textile
- Other End-use Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 43.81% of revenue in 2025 and is forecast to grow at a 5.84% CAGR through 2031. China has a production base in Shandong, Jiangsu, and Zhejiang. This supply base serves domestic coatings and ink manufacturers and export customers across Southeast Asia and Latin America, reinforcing Asia-Pacific's position in the nitrocellulose market. India is an important demand center for packaging, printing, wood coatings, and leather processing, while Japan supports demand for precision coatings and high-quality furniture finishes. India has imposed anti-dumping duties on Chinese nitrocellulose imports, and Nitrex Chemicals India is expanding capacity at Jhagadia for domestic and export demand.
North American demand is based on auto-refinish paints, cabinetry and flooring finishes, and flexible-packaging printing inks, while its residential renovation base supports cabinet-finishing lacquer demand. Europe faces tighter food-contact ink requirements while some production capacity shifts toward energetic-grade material. EU REACH requirements and Germany's Printing Ink Ordinance create reformulation and compliance work for suppliers and formulators.
South America, and Middle-East, and Africa remain smaller but growing demand centers. The nitrocellulose market in these regions relies heavily on imports and the development of local coatings and ink manufacturing. Brazil and Mexico support South American demand through packaging, furniture production, and industrial coatings, with wood coatings providing the fastest application growth path in Latin America. Saudi Arabia and South Africa are the main Middle-East and Africa demand centers, where decorative coatings, printing inks, and leather finishes support imports. Limited local production and infrastructure constraints keep consumption per person below global averages.
- ARDIN CHEMICAL COMPANY
- Eurenco
- GRN Cellulose Pvt. Ltd.
- Hubei Xuefei Chemical Co., Ltd
- IVM Chemicals srl
- MSM Walsrode GmbH and Co. KG
- Nitrex Chemicals India Ltd
- Nitrocellulose Group
- Nitrochemie
- Synthesia Nitrocellulose, a.s.
- T.N.C. Industrial Co., Ltd.
- TNC Chemicals Philippines Inc.
- Unix Cellulose
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand for High-Gloss and Fast-Drying Coatings Across Industrial Applications
- 4.2.2 Increasing Use of Nitrocellulose in Flexographic and Gravure Printing Inks
- 4.2.3 Rising Demand for Premium Wood Coatings and Furniture Finishes
- 4.2.4 Growing Preference for Fast-Curing Coating Systems to Improve Manufacturing Efficiency
- 4.2.5 Increasing Product Innovation Toward Low-VOC and Environmentally Compliant Formulations
- 4.3 Market Restraints
- 4.3.1 Stringent Safety Requirements for the Handling, Storage, and Transportation of Nitrocellulose
- 4.3.2 Increasing Competition from Alternative Resins such as Acrylics and Polyurethanes
- 4.3.3 High Compliance Costs Associated with Storage, Safety, and Regulatory Requirements
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Grade
- 5.1.1 Industrial Grade
- 5.1.2 Pharmaceutical Grade
- 5.1.3 Specialty Grade
- 5.2 By Application
- 5.2.1 Printing Inks
- 5.2.2 Automotive Paints
- 5.2.3 Wood Coatings
- 5.2.4 Leather Finishes
- 5.2.5 Nail Varnishes
- 5.2.6 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Paints and Coatings
- 5.3.2 Printing and Packaging
- 5.3.3 Pharmaceuticals and Healthcare
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 Leather and Textile
- 5.3.6 Other End-use Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ARDIN CHEMICAL COMPANY
- 6.4.2 Eurenco
- 6.4.3 GRN Cellulose Pvt. Ltd.
- 6.4.4 Hubei Xuefei Chemical Co., Ltd
- 6.4.5 IVM Chemicals srl
- 6.4.6 MSM Walsrode GmbH and Co. KG
- 6.4.7 Nitrex Chemicals India Ltd
- 6.4.8 Nitrocellulose Group
- 6.4.9 Nitrochemie
- 6.4.10 Synthesia Nitrocellulose, a.s.
- 6.4.11 T.N.C. Industrial Co., Ltd.
- 6.4.12 TNC Chemicals Philippines Inc.
- 6.4.13 Unix Cellulose
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


