

|
시장보고서
상품코드
2119045
액체 대체 연료 및 원자재 연소 시스템 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Liquid Alternate Fuel and Raw Materials (AFR) Firing Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
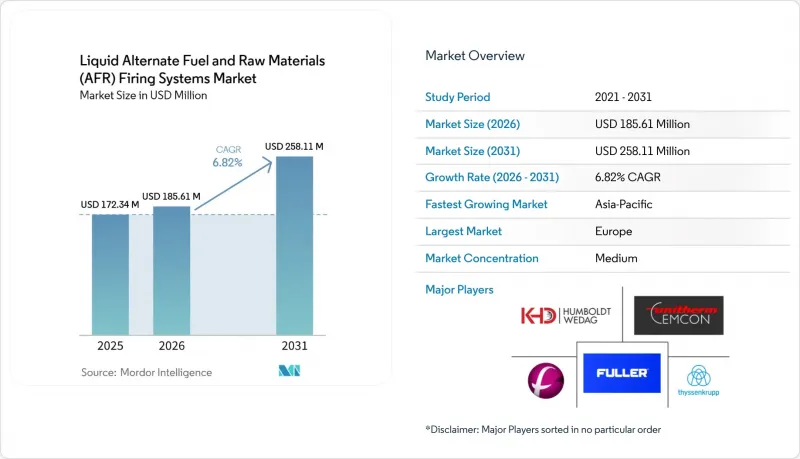
에 의하면, 액체 대체 연료 및 원자재 연소 시스템 시장 규모는 2025년에 1억 7,234만 달러로 평가되었습니다. 2026년 1억 8,561만 달러에서 2031년까지 2억 5,811만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년)에 6.82%의 연평균 복합 성장률(CAGR) 로 성장할 전망입니다.
본 보고서는 버너 시스템의 유형(로터리 킬른용 메인 버너, 칼시네이터, 멀티포인트, 기타), 연료의 유형(폐유, 사용 후 용제, 액체 바이오매스/바이오오일, 기타), 최종 사용자 산업(시멘트, 석회, 폐기물 발전, 펄프·제지, 기타),및 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 액체 대체 연료 및 원자재 연소 시스템 시장 동향 및 인사이트
탈탄소화 의무화와 배출 비용 회피
탄소 가격 도입은 가마의 운영 비용에 변화를 가져와 저탄소 연료 사용을 더욱 매력적으로 만듭니다. EU 배출권 거래 제도(ETS)는 시멘트 생산 업체들에게 화석 연료를 탄소 함량이 낮거나 일부가 생물 유래인 액체 대체 연료로 대체할 경제적 동기를 부여하고 있습니다. 홀심(Holcim)의 에클레펜스 공장에서는 폐유 및 동물성 지방의 사용을 확대함으로써 6개월 이내에 열 대체율을 70%에서 95% 가까이까지 끌어올렸습니다. 이러한 변화로 연간 4만 톤의 순 CO₂ 배출량이 감축되었습니다. 중국은 국내 탄소 배출권 거래 제도에 시멘트 제조업체를 포함시키고, 2025년 6월에 대체 연료 산정에 관한 기업 차원의 지침을 발표했습니다. 이러한 규제로 인해 연료 사용량 및 배출량을 측정·기록할 수 있는 제어 시스템에 대한 액체 대체 연료 및 원자재 연소 시스템 시장 수요가 증가하고 있습니다.
화석 연료 가격 변동과 에너지 안보
에너지 비용은 시멘트 생산 비용의 40%를 차지하고 있어, 생산자들은 석탄 및 석유 코크스 가격 변동의 영향을 받기 쉬운 상황에 놓여 있습니다. 폐유나 용제를 활용하는 유연성이 높은 시스템을 도입하면, 기존 연료 가격이 상승했을 때에도 그 영향을 완화할 수 있습니다. 2026년 조사에 따르면, 연료의 40%를 유분을 함유한 슬러지로 대체함으로써 기존 생산 비용이 톤당 392.89위안에서 358.45위안으로 낮아지고, CO2 배출량이 13.17% 감소한 것으로 나타났습니다. 이 결과는 중동 및 아프리카(MEA) 및 남아시아의 수입 연료 시장이 공급 안정 확보와 탄소 관리라는 두 가지 측면에서 액체 대체 연료를 검토하고 있는 이유를 보여줍니다. 풀러 테크놀로지스(Fuller Technologies)는 2025년, 시멘트 공장의 폐기물 및 RDF(고형 폐기물 연료)에서 열분해유를 생산하기 위한 ‘FUELFLEX Pyrolyzer’를 평가했습니다. 현장 생산을 통해 액체 대체 연료 및 원자재 연소 시스템 시장에서 외부 액체 연료 공급망에 대한 의존도를 낮출 수 있습니다.
높은 개조 자본 지출과 통합의 복잡성
기존 가마에서 액체 대체 연료를 안전하게 혼소하려면 버너 교체 이상의 조치가 필요합니다. 필요한 설비에는 이중 유체 분사 노즐, 예열 회로, 공급 모니터링, 비상 차단 및 제어 시스템 통합 등이 포함됩니다. 이러한 요건들로 인해 운영 비용 절감이 실현되기 전까지 전면적인 개조에는 막대한 비용이 소요됩니다. 2025년에 발표된 조사에 따르면, 특히 탄소 가격 책정 인센티브가 없는 저소득 시장에서 설비 투자 비용과 기술적 통합이 지속적인 장벽으로 작용하고 있는 것으로 밝혀졌습니다. 2026년, 시멘트 호주(Cement Australia)가 실시한 7,750만 호주 달러 규모의 가마 개조 공사에서는 45일간의 가동 중단이 필요했습니다. 이는 일부 사업자가 대규모 전환을 미루는 이유를 여실히 보여줍니다. 이러한 제약으로 인해, 특히 남미와 동남아시아 일부 지역에서 액체 대체 연료 및 원자재 연소 시스템 시장에서는 단계적인 혼소 방식이 선호되는 경향이 있습니다.
부문별 분석
2025년 기준, 로터리 킬른용 메인 버너형 액체 AFR 시스템은 액체 대체 연료 및 원자재 연소 시스템 시장 규모의 47.3%를 차지했습니다. 이러한 위상은 시멘트 열처리 공정에서 메인 버너가 주요 열원으로서의 역할을 수행하고 있음을 반영합니다. 설치 실적이 많고 가동상의 역할이 명확하기 때문에 대부분의 킬른 현대화 프로젝트는 이 부분부터 시작됩니다. 메인 버너는 기존 플랜트 레이아웃에서 액체, 고체, 기체 각 연료를 혼소할 수 있습니다. 그 도입은 기존의 화석 연료에서 벗어나고자 하는 플랜트에게 현실적인 첫걸음이 됩니다. 그러나 플랜트가 위성 또는 멀티포인트 기능을 추가하지 않는 한, 메인 버너를 통한 대체율은 보통 50-60%에 그칩니다. 이러한 한계로 인해 사업자들은 보다 광범위한 분사 구성을 검토하게 됩니다.
멀티포인트 액체 대체 연료 및 원자재 연소 시스템은 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 7.7%로 확대될 것으로 예측됩니다. 이 시스템은 액체 연료를 칼시네이터, 메인 버너 및 위성 분사 지점으로 분배합니다. 이러한 구성을 통해 운영자는 연료 품질이나 가마의 부하에 따라 연소를 조정할 수 있습니다. 2026년 조사에 따르면, 특정 액체 연료와 폐기물의 혼합 비율에 따라 단일 연료 기준 시나리오와 비교하여 CO 배출량을 최대 93.29%까지 감축할 수 있는 것으로 나타났습니다. 또한, 유럽의 배출량 모니터링 요건에서도 정확하고 추적 가능한 분사 제어가 가능한 시스템이 권장되고 있습니다. 칼시네이터 시스템은 프리칼시네이터 구역에서 80-100%의 열 치환율을 달성할 수 있어 여전히 주요 카테고리 중 하나로 자리 잡고 있습니다. KHD사의 ‘Pyrorotor’ 도입 사례는 칼시네이터 설비가 저품질 연료 스트림을 어떻게 처리할 수 있는지를 입증하고 있습니다. 그 밖의 시스템으로는 적은 투자로 추가적인 대체 효과를 실현할 수 있는 위성 버너 등이 있습니다.
지역별 분석
2025년, 유럽은 액체 대체 연료 및 원자재 연소 시스템 시장 점유율의 41.3%를 차지했습니다. EU의 탄소 비용, 매립 폐기물 감축 요건, 그리고 오랫동안 확립된 폐기물 인프라가 안정적인 액체 연료 공급을 뒷받침하고 있습니다. 프랑스, 독일, 이탈리아, 폴란드, 스페인은 이 지역의 주요 대규모 시장입니다. 오스트리아와 스위스에서는 높은 열적 대체 실적이 나타나고 있습니다. 홀심(Holcim)사의 에클레펜스 공장은 6개월 이내에 95%에 가까운 대체율을 달성하여 연간 4만 톤의 순 CO₂ 배출량을 감축했습니다. 유럽에서 향후 시행될 ‘산업 배출 지침’의 요건에 따라 2020년대 후반에 걸쳐 모니터링 및 제어 장비에 대한 지출이 증가할 전망입니다.
아시아태평양은 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 8.7%로 확대될 것으로 예측되며, 이는 지역별 부문 중 가장 높은 성장률입니다. 중국이 시멘트를 국가 탄소 시장에 임베디드함에 따라 대체 연료에 대한 투자에 더 명확한 재무적 근거가 마련되었습니다. KHD사는 2025년 12월, 콘치 그룹의 바오산 공장을 위해 두 번째 파이로로터 시스템을 가동했습니다. 콘치 그룹은 이후 그룹 전체 차원의 추가 도입을 검토하겠다고 밝혔습니다. 인도네시아의 세멘 바투라자(Semen Baturaja)는 2024년에 액체를 포함한 대체 연료 비율(AFR)을 41% 증가시켜 열 대체율을 3.18%로 끌어올렸습니다. 인도의 공장에서는 열 대체율이 평균 3-5%에 그치고 있어, 시스템 추가 도입을 위한 충분한 여지가 남아 있습니다.
북미, 남미, 중동 및 아프리카(MEA) 지역에서는 수요 상황이 다릅니다. 2024년 북미의 평균 열 대체율은 16%였으나, 유럽에서는 52%였으며, 연료의 안정적인 공급은 여전히 탄소 가격 책정보다 더 강력한 동기로 작용하고 있습니다. 남미에서는 순환형 경제 이니셔티브와 연소 시스템에 대한 투자를 통해 그 기세가 점점 더 커지고 있습니다. 중동 및 아프리카에는 연료 전환의 직접적인 기회가 있지만, 프로젝트는 현지 정책 및 자본 확보 상황에 따라 좌우됩니다. 시노마는 2025년 8월, 카심 시멘트(Kassim Cement)사와 1,200만 달러 규모의 EPC 계약을 체결하고, 브라이다 공장의 생산 라인을 원유 연소 방식에서 천연가스 연소 방식으로 전환하기로 했습니다. 이 프로젝트의 공사 기간은 15개월이었습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the liquid alternate fuel and Raw Materials Firing Systems Market size was valued at USD 172.34 million in 2025 and is estimated to grow from USD 185.61 million in 2026 to reach USD 258.11 million by 2031, at a CAGR of 6.82% during the forecast period (2026-2031).
This report is Segmented by Burner and System Type (Rotary Kiln Main Burner, Calciner, Multi-Point, Others), Fuel Type (Waste Oils, Used Solvents, Liquid Biomass/Bio-Oils, Others), End-User Industry (Cement, Lime, Waste-To-Energy, Pulp & Paper, Others), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Liquid Alternate Fuel and Raw Materials (AFR) Firing Systems Market Trends and Insights
Decarbonization Mandates and Emissions Cost Avoidance
Carbon pricing changes the cost of operating a kiln and makes lower-carbon fuel inputs more attractive. The EU Emissions Trading System gives cement producers a financial reason to replace fossil fuels with liquid alternative fuels that have lower or partly biogenic carbon content. Holcim's Eclepens plant increased its thermal substitution rate from 70% to nearly 95% within 6 months by expanding waste oil and animal fat use. The change reduced net CO2 emissions by 40,000 tonnes annually. China included cement producers in its national carbon emissions trading scheme and issued enterprise-level guidance for alternative-fuel accounting in June 2025. These rules increase demand in the Liquid AFR firing systems market for control systems that can measure and document fuel use and emissions.
Fossil Fuel Price Volatility and Energy Security
Energy represented 40% of cement production costs, leaving producers exposed to coal and petcoke price movements. Flexible systems that use waste oils and solvents can reduce that exposure when conventional fuel prices increase. A 2026 study found that replacing 40% of fuel with oily sludge reduced conventional production costs from CNY 392.89 to CNY 358.45 per tonne and reduced CO2 emissions by 13.17%. The result shows why imported-fuel markets in MEA and South Asia are considering liquid alternative fuels for supply security as well as for carbon management. Fuller Technologies evaluated its FUELFLEX Pyrolyzer in 2025 to produce pyrolysis oil from waste and RDF at cement plants. On-site production can reduce the Liquid AFR firing systems market's dependence on external liquid fuel supply chains.
High Retrofit Capital Expenditure and Integration Complexity
A legacy kiln needs more than a burner replacement to co-fire liquid alternative fuels safely. The required equipment can include dual-fluid atomization nozzles, preheating circuits, feed monitoring, emergency isolation, and control-system integration. These requirements make a full retrofit expensive before operating savings are realized. Research published in 2025 identified capital cost and technical integration as continuing barriers, particularly in lower-income markets without carbon-pricing incentives. Cement Australia's AUD 77.5 million kiln upgrade required a 45-day shutdown in 2026, illustrating why some operators delay extensive conversions. This constraint favors gradual co-firing in the Liquid AFR firing systems market, especially in South America and parts of Southeast Asia.
Other drivers and restraints analyzed in the detailed report include:
- Circular Economy and Landfill Diversion Requirements
- Cement Plant Modernization and Thermal Substitution Targets
- Variable Fuel Quality and Process Instability Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rotary Kiln Main Burner Liquid AFR Systems held 47.3% of the Liquid AFR firing systems market size in 2025. Their position reflects the main burner's role as the primary heat source in cement pyroprocessing. Most kiln modernization projects begin with this location because it has a large installed base and a clear operating role. Main burners can co-fire liquid, solid, and gaseous fuels in established plant layouts. Their use provides a practical first step for plants that are moving away from conventional fossil fuels. However, main burner substitution normally reaches 50-60% unless the plant adds satellite or multi-point capability. This limitation creates a reason for operators to consider more extensive injection configurations.
Multi-Point Liquid AFR Firing Systems are expected to grow at a 7.7% CAGR from 2026 to 2031. They distribute liquid fuel across the calciner, main burner, and satellite injection locations. This arrangement lets the operator adjust combustion to fuel quality and kiln load. A 2026 study found that specific mixed liquid-waste ratios can reduce CO emissions by as much as 93.29% against single-fuel baseline cases. European emissions-monitoring requirements also favor systems that offer precise and traceable injection control. Calciner systems remain another major category because they can achieve 80-100% thermal substitution in the precalciner zone. KHD's Pyrorotor installations demonstrate how calciner equipment can process lower-quality fuel streams. Other systems include satellite burners that provide a lower-capital route to incremental substitution gains.
Complete Report Scope:
- By Burner and System Type
- Rotary Kiln Main Burner Liquid AFR Systems
- Calciner Liquid AFR Firing Systems
- Multi-Point Liquid AFR Firing Systems
- Others
- By Fuel Type
- Waste Oils
- Used Solvents and Liquid Chemical Residues
- Liquid Biomass and Bio-Oils
- Sewage Sludge and Pumpable Slurries
- Others
- By End-User Industry
- Cement Industry
- Lime Industry
- Waste-to-Energy Plants
- Pulp & Paper Industry
- Other Industrial Kilns and Furnaces
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe held 41.3% of the Liquid AFR firing systems market share in 2025. EU carbon costs, landfill-diversion requirements, and long-established waste infrastructure support a consistent liquid fuel supply. France, Germany, Italy, Poland, and Spain are the region's main high-volume markets. Austria and Switzerland have demonstrated high thermal substitution performance. Holcim's Eclepens plant reached nearly 95% substitution within 6 months and reduced net CO2 output by 40,000 tonnes a year. Europe's upcoming Industrial Emissions Directive requirements are likely to increase spending on monitoring and control equipment through the late 2020s.
Asia-Pacific is projected to expand at an 8.7% CAGR from 2026 to 2031, the fastest rate among the geographic segments. China's inclusion of cement in its national carbon market gives alternative-fuel investments a clearer financial basis. KHD commissioned its second Pyrorotor system for Conch Group's Baoshan plant in December 2025. Conch then stated that it would assess further installations across its network. Indonesia's Semen Baturaja increased liquid-inclusive AFR use by 41% in 2024 and raised thermal substitution to 3.18%. India's plants averaged 3-5% thermal substitution, leaving material capacity for additional system adoption.
North America, South America, and MEA have different demand conditions. North America's average thermal substitution rate was 16% in 2024, compared with 52% in Europe, and fuel security remains a stronger motivation than carbon pricing. South America is building momentum through circular-economy initiatives and combustion-system investment. The Middle East and Africa have direct fuel-conversion opportunities, but projects are shaped by local policy and capital availability. Sinoma signed a USD 12 million EPC contract with Qassim Cement in August 2025 to convert Buraydah plant lines from crude oil firing to natural gas. The project had a 15-month schedule.
- A TEC Production & Services GmbH
- Dynamis Ltd.
- FCT Combustion Pty Ltd
- Fives Group
- Fuller Technologies, Inc.
- GRECO Combustion Systems Europe GmbH
- KHD Humboldt Wedag International AG
- SATAREM S.A.
- Sinoma International Engineering Co., Ltd.
- thyssenkrupp Polysius GmbH
- Unitherm Cemcon Feuerungsanlagen GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Decarbonization Mandates and Emissions-Cost Avoidance
- 4.2.2 Fossil-Fuel Price Volatility and Energy-Security Priorities
- 4.2.3 Circular-Economy and Landfill-Diversion Requirements
- 4.2.4 Cement-Plant Modernization and Thermal Substitution Targets
- 4.2.5 Liquid AFR Specification Variability Driving Adaptive Atomization Demand
- 4.2.6 Localized Waste Logistics and Seasonal Feedstock Availability
- 4.3 Market Restraints
- 4.3.1 High Retrofit Capex and Integration Complexity
- 4.3.2 Variable Fuel Quality and Process-Instability Risk
- 4.3.3 Hazardous-Liquid Handling Permitting and Liability Exposure
- 4.3.4 Contaminant-Driven Corrosion and Burner-Tip Wear
- 4.4 Value Chain Analysis
- 4.5 Technology Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Burner and System Type
- 5.1.1 Rotary Kiln Main Burner Liquid AFR Systems
- 5.1.2 Calciner Liquid AFR Firing Systems
- 5.1.3 Multi-Point Liquid AFR Firing Systems
- 5.1.4 Others
- 5.2 By Fuel Type
- 5.2.1 Waste Oils
- 5.2.2 Used Solvents and Liquid Chemical Residues
- 5.2.3 Liquid Biomass and Bio-Oils
- 5.2.4 Sewage Sludge and Pumpable Slurries
- 5.2.5 Others
- 5.3 By End-User Industry
- 5.3.1 Cement Industry
- 5.3.2 Lime Industry
- 5.3.3 Waste-to-Energy Plants
- 5.3.4 Pulp & Paper Industry
- 5.3.5 Other Industrial Kilns and Furnaces
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 A TEC Production & Services GmbH
- 6.4.2 Dynamis Ltd.
- 6.4.3 FCT Combustion Pty Ltd
- 6.4.4 Fives Group
- 6.4.5 Fuller Technologies, Inc.
- 6.4.6 GRECO Combustion Systems Europe GmbH
- 6.4.7 KHD Humboldt Wedag International AG
- 6.4.8 SATAREM S.A.
- 6.4.9 Sinoma International Engineering Co., Ltd.
- 6.4.10 thyssenkrupp Polysius GmbH
- 6.4.11 Unitherm Cemcon Feuerungsanlagen GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


