|
시장보고서
상품코드
2119196
비프탈레이트 가소제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Non-Phthalate Plasticizers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 비프탈레이트 가소제 시장은 2025년에 42억 7,000만 달러 규모로 평가되었습니다. 2026년 45억 8,000만 달러에서 2031년까지 67억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.97%를 나타낼 전망입니다.
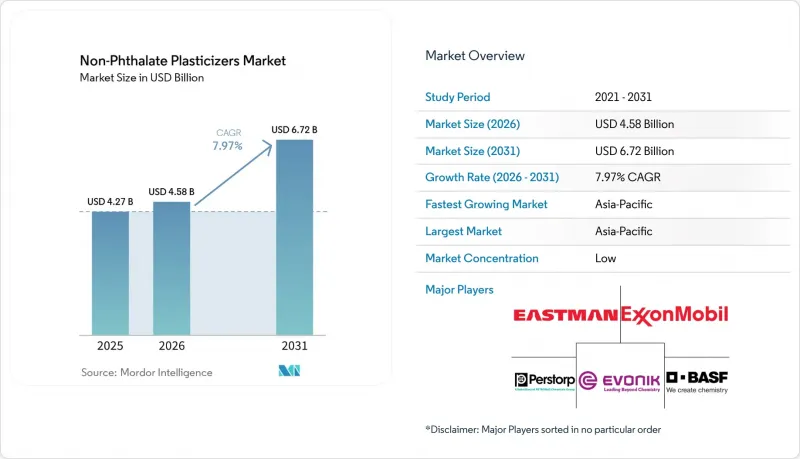
본 보고서는 유형별(테레프탈레이트, 아지페이트, 트리메리테이트 등), 용도별(바닥재·벽재, 전선 및 케이블 등), 최종 이용 산업별(건축 및 건설, 자동차 및 운송 등),및 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 비프탈레이트 가소제 시장 동향 및 인사이트
프탈산 에스테르 규제 및 보다 안전한 대체재 사용 의무
규제에 따른 제한은 비프탈레이트 가소제 시장의 전환을 촉진하는 가장 큰 구조적 촉진요인 중 하나입니다. 화학물질의 등록, 평가, 허가 및 제한(REACH)에 따라, 디(2-에틸헥실)프탈레이트(DEHP),벤질부틸 프탈레이트(BBP), 디부틸 프탈레이트(DBP) 및 디이소부틸 프탈레이트(DIBP)는 계속 사용하기 위해 승인이 필요하며, 2024년 11월 기준 후보 목록에는 242건이 등재되어 있었습니다. EU의 의료기기 관련 예외 조치에 따라 DEHP의 준수 기한은 2025년 5월에서 2030년 7월로 연장되었습니다. 따라서 제조업체는 기한까지 대체품의 적합성을 확인할 시간적 여유가 있습니다. 다만, 의료기기 제조업체는 2030년 7월까지 규정을 준수하는 제품 라인을 준비해야 하므로, 기한 변경으로 인해 배합 변경의 필요성이 사라지는 것은 아닙니다. REACH, 유해물질 규제법(TSCA) 및 중국의 GB 9685 규격은 주요 생산 지역 및 소비 지역 전반에 걸친 대체 요건을 종합적으로 규정하고 있습니다.
건설 및 인프라 분야의 가소화 PVC 수요
건설 분야는 계속해서 비프탈레이트 가소제 시장의 주요 수익원입니다. 이는 가소화된 PVC가 바닥재, 케이블 도관, 방수 시트 및 기타 건축자재에 사용되기 때문입니다. 아시아태평양, 중동 및 라틴아메리카 일부 지역의 인프라 구축 사업이 이러한 용도에 대한 수요를 뒷받침하고 있습니다. EU 건설 제품 규정(규정(EU) 2024/3110)은 2026년 1월 8일부터 적용되기 시작하며, EU 역내 건설 제품에 대한 요건을 통일하고 있습니다. 이 프레임워크는 유럽 건축 제품 공급망에서 적합성 기준을 충족하는 재료의 사용을 촉진하고 있습니다. 상업시설 리노베이션의 경우, 임차인이나 시설 관리자가 저이동성 및 저휘발성 유기화합물(VOC) 바닥재를 요구하는 상황에서 디옥틸테레프탈레이트(DOTP)가 함유된 고급 비닐 타일이 주목을 받고 있습니다. 이러한 사양은 제품에 대한 직접적인 규제가 적용되지 않는 경우에도 수요를 증가시킬 가능성이 있습니다.
가격에 민감한 배합에서 기존 프탈레이트 에스테르와의 비용 차이
DINP와 DIDP의 가격 차이는 비용에 민감한 용도에서 대체재의 채택을 여전히 제한하고 있습니다. 이러한 기존 프탈레이트는 일부 용도에서 일반 사용이 여전히 승인되어 있으므로, 강제적인 전환이 항상 일어나는 것은 아닙니다. 동등한 가소성을 지닌 PVC 배합에서 DOTP는 일반적으로 DINP에 비해 10-20%의 단위 비용 추가가 발생합니다. 시클로헥사노에이트계 대체재는 DOTP보다 비용이 더 높을 수 있습니다. 남아시아 및 동남아시아의 중규모 PVC 컴파운더들은 아직 비프탈레이트 소재를 필수로 규정하지 않은 사양에 따라 생산하는 경우가 많습니다. 이로 인해 범용 건축자재 및 소비자용 응용 분야의 비프탈레이트 가소제 시장에서 이 가격 차이는 직접적인 제약 요인으로 작용하고 있습니다.
부문별 분석
2025년 기준, 테레프탈레이트는 비프탈레이트 가소제 시장 점유율의 34.82%를 차지했습니다. DOTP는 바닥재, 전선 피복, 자동차용 비닐 등 유연성 PVC 용도에서 비용 대비 성능의 균형이 뛰어납니다. 낮은 휘발성과 열안정성 덕분에 폭넓은 용도에 적합합니다. 또한 FDA의 식품 접촉 허가를 획득하여, 접촉 요건이 중요한 분야에서 사용을 뒷받침하고 있습니다. 이스트만 168은 범용 비프탈레이트 대체재로 사용되는 DOTP의 한 예입니다. 비프탈레이트 가소제 업계에서는 DEHP의 주요 대체 경로로 테레프탈레이트를 중시하고 있습니다. 아지페이트는 저온에서도 유연성을 유지하므로 한랭 지역이나 특수 자동차 용도에 적합합니다. TOTM을 포함한 트리머리테이트는 더 높은 열 성능이 요구되는 전기 및 자동차 배선 용도에 대응하고 있습니다.
시트르산 에스테르계 가소제는 2031년까지 연평균 성장률(CAGR) 9.63%로 확대될 것으로 예측됩니다. 의료용 PVC 가공 및 식품 접촉 용도가 이러한 성장을 뒷받침하고 있습니다. 또한, 바이오 유래 원료는 브랜드 소유자가 추진하는 지속가능성 프로그램과도 부합합니다. 페르스토프(Perstorp)는 2024년 1월, 질량 균형 방식에 따른 추적성을 바탕으로 100% 재생 가능 탄소를 기반으로 한 비프탈레이트 가소제 ‘Pevalen Pro 100’을 출시했습니다. 이 회사에 따르면, 이 제품은 ISCC PLUS 인증을 획득했으며, 화석 유래 동급 제품에 비해 제품의 탄소 발자국이 80% 감소했다고 합니다. 따라서 벤조산 에스테르 및 기타 대체품은 조달 측면뿐만 아니라 성능 측면에서도 점점 더 차별화가 진행되고 있습니다. 에폭시 수지는 PVC의 열안정화를 뒷받침합니다. 세바신산 에스테르는 극저온에서 유연성이 요구되는 용도에 사용되며, 기타 유형은 특수 코팅의 요구 사항을 충족시키고 있습니다.
지역별 분석
아시아태평양은 2025년에 비프탈레이트 가소제 시장의 45.62%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.77%로 성장할 것으로 전망됩니다. 중국은 대규모의 유연한 PVC 생산 거점과 지속적인 인프라 투자를 통해 시장에 기여하고 있습니다. 또한 수출 제조업체들은 유럽 및 미국의 구매자들이 요구하는 규정 준수 요건을 충족해야 합니다. 인도는 주택 건설 확대와 ‘스마트 시티 미션’이 바닥재 및 케이블 절연재 수요를 뒷받침하고 있어, 이 지역 내 중요한 성장 거점으로 자리 잡고 있습니다. 국내 가소제 생산 능력은 증가하는 수요를 따라가지 못하고 있습니다. 이로 인해 한국, 일본, 중국으로부터의 수입이 시장을 지탱하고 있습니다. 일본과 한국은 국내 및 동남아시아 시장을 대상으로 고부가가치의 트리메리테이트와 특수 구연산염 등급을 공급하고 있습니다.
북미 수요는 엑슨모빌, 이스트만 케미컬, BASF의 생산 인프라에 의해 뒷받침되고 있습니다. TSCA 요건, 캘리포니아주 프로포지션 65, 그리고 AB 2300에 따라 의료용 튜브 및 포장재에서 DEHP 대체가 진행되고 있습니다. 미국의 전선 및 케이블 분야는 송전망 현대화, 재생에너지 연결, 그리고 전기차(EV) 충전 인프라에 의해 뒷받침되고 있습니다. 이러한 용도에서는 더 많은 내열성 절연 재료가 필요합니다. 유럽은 REACH 규제로 인해 많은 소비자용 및 의료용 분야에서 DEHP가 대체됨에 따라 규제 준수 기준이 가장 높습니다. 범용 테레프탈레이트 수요가 성숙기에 접어드는 가운데, 성장은 DINCH, 트리메리테이트 및 바이오 유래 대체재에 집중되고 있습니다. 독일이 지역 시장을 주도하고 있으며, 프랑스, 이탈리아, 영국에서는 의료 및 포장 분야의 가공 수요가 나타나고 있습니다.
남미, 중동 및 아프리카에서는 건설 활동과 국제적인 화학 물질 안전 요건에 대한 점진적인 조화가 수요를 뒷받침하고 있습니다. 브라질은 주택 프로젝트에 사용되는 파이프, 케이블, 바닥재를 통해 남미 수요 기반을 형성하고 있습니다. 프탈레이트 무함유 사양은 수출 지향적 제조를 통해 도입되는 경우가 많습니다. 사우디아라비아와 남아프리카공화국은 석유화학 분야에 대한 투자와 현지 컴파운딩 역량을 통해 지역 수요를 뒷받침하고 있습니다. 이러한 투자를 통해 수입 의존도를 낮출 수 있습니다. 비용에 대한 민감성과 법적 구속력이 있는 규제가 제한적이기 때문에 일부 제품 카테고리에서는 여전히 도입이 제한되고 있습니다. 수출 주도형 규정 준수 요건으로 인해 프탈레이트 무첨가 배합에 대한 기준은 점진적으로 높아지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 전망(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.02According to Mordor Intelligence, the non-Phthalate plasticizers market was valued at USD 4.27 billion in 2025 and is estimated to grow from USD 4.58 billion in 2026 to reach USD 6.72 billion by 2031, at a CAGR of 7.97% during the forecast period (2026-2031).
This report is Segmented by Type (Terephthalates, Adipates, Trimellitates, and More), Application (Flooring and Wall Coverings, Wires and Cables, and More), End-Use Industry (Building and Construction, Automotive and Transportation, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Non-Phthalate Plasticizers Market Trends and Insights
Phthalate Restrictions and Safer-Substitution Mandates
Regulatory restriction is one of the largest structural drivers for conversion in the non-phthalate plasticizers market. Under Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH), Di(2-Ethylhexyl) Phthalate (DEHP), Benzyl Butyl Phthalate (BBP), Dibutyl Phthalate (DBP), and Diisobutyl Phthalate (DIBP) require authorization for continued use, and the Candidate List contained 242 entries in November 2024. The EU medical-device exception extended the DEHP compliance deadline from May 2025 to July 2030. Manufacturers, therefore, have time to qualify alternatives before the deadline. The revised date does not eliminate the need for reformulation because device producers must prepare compliant product lines before July 2030. REACH, Toxic Substances Control Act (TSCA), and China's GB 9685 standard collectively shape substitution requirements across major producing and consuming regions.
Flexible PVC Demand in Construction and Infrastructure
Construction remains the main revenue anchor for the non-phthalate plasticizers market because flexible PVC is used in flooring, cable conduit, waterproofing membranes, and other building products. Infrastructure programs in Asia-Pacific, the Middle-East, and parts of Latin America support demand for these applications. The EU Construction Products Regulation, Regulation (EU) 2024/3110, became applicable from January 8, 2026, and aligns construction-product requirements across the bloc. This framework supports the use of compliant materials in European architectural product supply chains. In commercial renovation, Dioctyl Terephthalate (DOTP)-formulated luxury vinyl tile is gaining attention where tenants and facility managers seek low-migration and low-Volatile Organic Compound (VOC) flooring. Those specifications can increase demand even when a direct product restriction does not apply.
Higher Cost Versus Legacy Phthalates in Price-Sensitive Formulations
The price difference between DINP and DIDP continues to limit the uptake of alternatives in cost-sensitive uses. These legacy phthalates remain authorized for general use in several applications, so a mandatory switch does not always occur. DOTP commonly carries a 10-20% unit-cost premium over DINP in comparable flexible PVC formulations. Cyclohexanoate alternatives can cost more than DOTP. Mid-sized PVC compounders in South and Southeast Asia often work with specifications that do not yet require non-phthalate materials. This makes the price differential a direct constraint on the non-phthalate plasticizers market in commodity construction and consumer applications.
Other drivers and restraints analyzed in the detailed report include:
- Electrification-Driven Demand for High-Temperature Cable Insulation
- Medical-Device Conversion to Validated Alternative Plasticizers
- Feedstock and Esterification Capacity Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Terephthalates held 34.82% of the non-phthalate plasticizers market share in 2025. DOTP provides a cost-performance balance for flexible PVC uses such as flooring, wire insulation, and automotive vinyl. Its low volatility and thermal stability make it suitable for a wide group of applications. FDA food-contact clearance also supports its use where contact requirements matter. Eastman 168 is an example of DOTP used as a general-purpose non-phthalate alternative. The non-phthalate plasticizers industry relies on terephthalates as a main replacement route for DEHP. Adipates address cold-climate and specialized automotive uses because they retain flexibility at lower temperatures. Trimellitates, including TOTM, address electrical and automotive wiring uses that require higher thermal performance.
Citrates are forecast to expand at a 9.63% CAGR through 2031. Medical-grade PVC conversion and food-contact uses support this growth. Bio-origin feedstocks also align with sustainability programs used by brand owners. Perstorp launched Pevalen Pro 100 in January 2024 as a non-phthalate plasticizer based on 100% renewable carbon under mass-balance traceability. The company stated that the product had ISCC PLUS certification and an 80% lower product carbon footprint than its fossil-based equivalent. Benzoates and other alternatives are therefore increasingly differentiated through sourcing as well as performance. Epoxies support PVC heat stabilization. Sebacates serve applications requiring very low-temperature flexibility, while other types address specialty coating needs.
Complete Report Scope:
- By Type
- Terephthalates
- Adipates
- Trimellitates
- Benzoates
- Epoxies
- Citrates
- Sebacates
- Other Types
- By Application
- Flooring and Wall Coverings
- Wires and Cables
- Films and Sheets
- Coated Fabrics
- Medical Devices
- Consumer Goods
- Adhesives and Sealants
- Other Applications
- By End-Use Industry
- Building and Construction
- Automotive and Transportation
- Healthcare and Pharmaceuticals
- Packaging
- Electrical and Electronics
- Consumer Goods
- Industrial Manufacturing
- Other End-Use Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 45.62% of the non-phthalate plasticizers market share in 2025 and is forecast to grow at an 8.77% CAGR through 2031. China contributes through its large, flexible PVC production base and continuing infrastructure investment. Export manufacturers also face compliance requests from European and U.S. buyers. India is an important regional growth point because housing expansion and the Smart Cities Mission support demand for flooring and cable insulation. Domestic plasticizer capacity has not kept pace with rising demand. This supports imports from South Korea, Japan, and China. Japan and South Korea provide highervalue trimellitate and specialty citrate grades for domestic and Southeast Asian markets.
North America's demand is supported by production infrastructure from ExxonMobil, Eastman Chemical, and BASF. TSCA requirements, California Proposition 65, and AB 2300 support DEHP substitution in medical tubing and packaging. The U.S. wire and cable segment is supported by grid modernization, renewable-energy connections, and EV charging infrastructure. These uses require more high-temperature insulation materials. Europe has the highest regulatory compliance baseline because REACH has displaced DEHP in many consumer-facing and medical applications. Growth is concentrated in DINCH, trimellitates, and bio-based alternatives as commodity terephthalate demand matures. Germany leads the regional market, while France, Italy, and the United Kingdom have medical and packaging conversion demand.
In South America, and Middle-East and Africa, construction activity and gradual alignment with international chemical-safety requirements support demand. Brazil provides South America's demand base through pipes, cables, and flooring used in housing projects. Non-phthalate specifications often enter through export-oriented manufacturing. Saudi Arabia and South Africa support regional demand through petrochemical investment and local compounding capacity. These investments can reduce dependence on imports. Cost sensitivity and limited binding mandates continue to restrict adoption in several product categories. Export-led compliance requirements are gradually increasing the baseline for non-phthalate formulations.
- Aekyung Chemical Co., Ltd.
- BASF
- Eastman Chemical Company
- Evonik Industries AG
- Exxon Mobil Corporation
- Hallstar
- Hanwha Solutions
- KLJ Group
- Nan Ya Plastics Corporation
- Perstorp
- UPC Technology Corporation
- Valtris Specialty Chemicals
- Velsicol Chemical LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Phthalate Restrictions and Safer-Substitution Mandates
- 4.2.2 Flexible PVC Demand in Construction and Infrastructure
- 4.2.3 Electrification-Driven Demand for High-Temperature Cable Insulation
- 4.2.4 Medical-Device Conversion to Validated Alternative Plasticizers
- 4.2.5 Brand-Owner Preference for Traceable Low-Carbon Formulations
- 4.3 Market Restraints
- 4.3.1 Higher Cost Versus Legacy Phthalates in Price-Sensitive Formulations
- 4.3.2 Feedstock and Esterification Capacity Volatility
- 4.3.3 Performance Trade-Offs Across Temperature, Migration, and Fusion
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Terephthalates
- 5.1.2 Adipates
- 5.1.3 Trimellitates
- 5.1.4 Benzoates
- 5.1.5 Epoxies
- 5.1.6 Citrates
- 5.1.7 Sebacates
- 5.1.8 Other Types
- 5.2 By Application
- 5.2.1 Flooring and Wall Coverings
- 5.2.2 Wires and Cables
- 5.2.3 Films and Sheets
- 5.2.4 Coated Fabrics
- 5.2.5 Medical Devices
- 5.2.6 Consumer Goods
- 5.2.7 Adhesives and Sealants
- 5.2.8 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Building and Construction
- 5.3.2 Automotive and Transportation
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Packaging
- 5.3.5 Electrical and Electronics
- 5.3.6 Consumer Goods
- 5.3.7 Industrial Manufacturing
- 5.3.8 Other End-Use Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aekyung Chemical Co., Ltd.
- 6.4.2 BASF
- 6.4.3 Eastman Chemical Company
- 6.4.4 Evonik Industries AG
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 Hallstar
- 6.4.7 Hanwha Solutions
- 6.4.8 KLJ Group
- 6.4.9 Nan Ya Plastics Corporation
- 6.4.10 Perstorp
- 6.4.11 UPC Technology Corporation
- 6.4.12 Valtris Specialty Chemicals
- 6.4.13 Velsicol Chemical LLC
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment