

|
시장보고서
상품코드
2119198
블로우 성형 플라스틱 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Blow Molded Plastics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
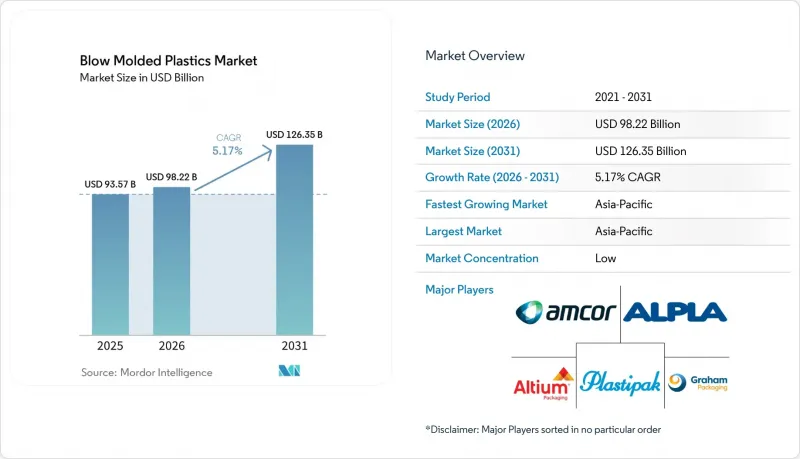
에 의하면, 블로우 성형 플라스틱 시장 규모는 2025년에 935억 7,000만 달러로 평가되었습니다. 2026년 982억 2,000만 달러에서 2031년까지 1,263억 5,000만 달러로 확대되어 예측 기간(2026-2031년) CAGR은 5.17%가 된다고 추정되고 있습니다.
본 보고서는 수지별(폴리에틸렌(PE), 폴리에틸렌 테레프탈레이트(PET) 등), 성형 방법별(압출 블로우 성형(EBM), 사출 블로우 성형(IBM) 등), 용도(식품 및 음료, 의약품 및 헬스케어, 기타),및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 블로우 성형 플라스틱 시장 동향 및 인사이트
유리나 금속을 대체하여 경량 플라스틱 포장으로의 전환이 진행되고 있습니다.
블로우 성형 용기는 경량성, 안전한 취급, 파손 방지가 중요한 음료, 가정용 화학제품 및 산업용 포장 분야에서 사용이 확대되고 있습니다. 블로우 성형 플라스틱 시장은 운송 하중을 경감하고, 소비자용 및 산업용 생산 현장의 고속 충전 라인에서 안정적으로 작동하는 용기에 의해 뒷받침되고 있습니다. 블로우 성형 용기는 동등한 유리 용기에 비해 20%에서 30%까지 경량화를 실현할 수 있습니다. 이러한 장점을 통해 운송 비용 절감, 파손으로 인한 손실 감소, 그리고 포장 및 유통 작업에서의 취급 편의성 향상을 도모할 수 있습니다. 폴리에틸렌 테레프탈레이트(PET)는 일부 프리미엄 음료 포맷으로의 확대가 진행되고 있는 한편, 병의 경량화를 도모하기 위해 좁은 입구 생산 기법이 채택되고 있습니다. 용기의 경량화 추세는 브랜드 소유자가 기대하는 기본 기능을 변경하지 않으면서도, 컨버터가 재료 효율이 높은 설계에 투자하는 이유가 되고 있습니다.
식품 및 음료 포장 업계 수요 증가
2025년, 식품 및 음료 분야는 수요의 31.64%를 차지하며, 블로우 성형 플라스틱 시장에서 여전히 가장 큰 용도 분야로 남아 있었습니다. 탄산음료, 생수, 유제품, 조미료, 기능성 음료는 성숙한 소비 시장이든 신흥 소비 시장이든 상관없이 대량의 경질 포장이 필요합니다. 다층 공압출 성형을 통해 제조업체는 단일 제조 공정 내에서 병 벽면에 산소, 자외선, 습기에 대한 차단층을 추가할 수 있습니다. 이러한 구조를 통해 소매업체와 브랜드 소유자가 요구하는 용기의 특성을 유지하면서, 변질되기 쉬운 제품의 유통 기한을 연장할 수 있습니다. EU의 ‘포장 및 포장 폐기물 규정’에 따라 재활용성 및 재사용 목표를 지원하는 설계에 대한 관심이 높아지고 있습니다. 또한 각 브랜드는 ‘국제 지속가능성·탄소 인증 기준’을 활용하여 재생 수지 함유량 주장을 검증하고 있으며, 이로 인해 포장 공급업체에 대한 문서화 요건이 더욱 엄격해지고 있습니다.
증가하는 플라스틱 폐기물 관리 및 재활용 인프라의 과제
회수 및 분리 처리 능력은 포장 공급업체, 브랜드 소유자 및 공공 기관이 내세우는 순환 경제 이니셔티브에 반드시 부합하는 것은 아닙니다. 다층 병은 뛰어난 차단성을 발휘하지만, 구조가 단순한 병에 비해 대규모 재활용이 여전히 어렵습니다. 이로 인해 블로우 성형 플라스틱 시장에서 제품 보호와 사용 후 처리 사이에서 상충 관계가 발생하고 있습니다. 이러한 제약은 엄격한 기술적 요건이 요구되는 EVOH 배리어 식품용 병, 다층 구조의 고밀도 폴리에틸렌(HDPE) 자동차 연료 탱크에서 특히 두드러집니다. 남아시아 및 동남아시아에서는 회수 시스템이 최소 재활용 소재 함유율을 요구하는 수출처 고객의 요건을 충족하지 못할 가능성이 있어 더욱 큰 압박에 직면해 있습니다. EU의 ‘포장 및 포장 폐기물 규정’에서는 2030년까지 포장재의 재활용 가능성을 의무화하고 있어, 규제 대상 시장에 제품을 판매하는 가공업체의 규정 준수 부담이 증가하고 있습니다.
부문별 분석
2025년, 폴리에틸렌은 매출의 38.92%를 차지하며 블로우 성형 플라스틱 시장에서 가장 큰 수지 부문이 되었습니다. 비용 특성, 내화학성, 그리고 압출 블로우 성형 및 공압출 성형과의 호환성 덕분에 대량 생산되는 포장 및 산업용도를 뒷받침하고 있습니다. HDPE는 산업용 용기, 가정용 화학 약품 병 및 벌크 포장용 드럼에 널리 사용됩니다. LDPE 및 LLDPE는 압착, 유연성 또는 제어된 배출이 요구되는 부드러운 형태의 제품을 뒷받침합니다. PET는 투명성, 차단 성능 및 재활용 옵션 덕분에 음료, 퍼스널케어, 의약품용 병에 적합하여 여전히 중요한 수지 중 하나입니다. 아시아태평양 및 북미에서의 사출 신장 블로우 성형(ISBM) 장비 도입 실적도 PET 가공을 뒷받침하고 있습니다.
블로우 성형 플라스틱 시장에서 바이오 및 재활용 플라스틱은 2031년까지 연평균 성장률(CAGR) 8.02%로 확대될 것으로 예측됩니다. PP는 블로우 성형 플라스틱 시장에서 자동차 및 의료 분야의 특수 용도로 사용되는 반면, PVC는 산업용 용기에 사용됩니다. ABS 및 PC는 보다 구체적인 특성이 요구되는 전자기기나 안전성이 극히 중요한 용도에 사용되고 있습니다. PA는 가혹한 환경에서 PE나 PP보다 효과적으로 열과 화학 물질에 대처할 수 있기 때문에 전기차의 유체 관리 시스템에서 그 역할을 확대되고 있습니다. LyondellBasell사가 2025년에 재생 PP 및 HDPE에 대해 FDA로부터 획득한 승인서는 특정 식품 접촉 용도 및 퍼스널케어 용도를 위한 공식적인 길을 제시하고 있습니다. 검증된 함유량 기준은 공급업체가 재생 수지 및 바이오 수지에 대한 주장을 추적 가능한 문서를 통해 입증하는 데 도움이 됩니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 48.33%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.96%로 성장할 것으로 전망됩니다. 이러한 실적을 바탕으로 이 지역은 블로우 성형 플라스틱 시장에서 가장 큰 점유율과 성장률을 자랑하고 있습니다. 중국 광둥성과 저장성에 위치한 석유화학 산업 클러스터는 하류 가공업체 및 포장 사업으로의 효율적인 원자재 유통을 뒷받침하고 있습니다. 인도의 의약품 제조 확대는 고정밀도 및 위변조 방지 기능을 갖춘 용기에 대한 수요를 촉진하고 있습니다. 일본과 한국은 고사양 의약품 및 반도체 부품 포장 분야에서 여전히 중요한 역할을 수행하고 있습니다.
북미에는 성형 설비, 위탁 포장 사업, 자동차 생산 및 의약품 포장에 대한 투자라는 확고한 기반이 구축되어 있습니다. 그레이엄 패키징(Graham Packaging)은 루이지애나주 해먼드에 위치한 자사 시설에 대해 3,500만 달러 규모의 확장 및 현대화 프로젝트를 발표했으며, 2027년까지 업그레이드를 완료할 계획입니다. 유럽에서는 ‘포장 및 포장 폐기물 규정(PPWR)’의 요건에 따라 투자가 단일 소재나 재생 소재를 포함한 구조로 전환되고 있어, 부가가치를 중시하는 경향이 강해지고 있습니다. 독일, 프랑스, 이탈리아, 영국은 이러한 변화에서 중요한 시장입니다. 규정을 준수하는 경질 용기를 공급할 수 있는 공급업체는 소비재 제조업체에 대한 입지를 강화할 수 있습니다.
남미, 중동 및 아프리카는 블로우 성형 플라스틱 시장에 있어 독자적인 수요원을 형성하고 있습니다. 브라질과 아르헨티나는 식품 가공 및 농약 포장을 통해 남미의 소비를 뒷받침하고 있습니다. 사우디아라비아와 남아프리카공화국은 중동 및 아프리카을 주도하고 있으며, 이 지역에서는 걸프협력회의(GCC)에 의한 석유화학 산업의 통합이 수지부터 포장재로의 전환을 뒷받침하고 있습니다. 도시화와 소비재의 보급으로 사하라 이남 아프리카 전역에서 장기적인 수요가 발생하고 있습니다. 재활용 및 수거 체계의 미비는 다국적 가공업체들에게 지속가능성 관련 규정 준수를 복잡하게 만들 가능성이 있습니다. 그레이프(Graef)는 2026년 6월, 스페인의 엔바플라스트(Envaplast) 인수를 완료하여 유럽 및 중동 및 아프리카의 폴리머 포장 사업 확장을 뒷받침할 제조 거점을 추가했습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.02According to Mordor Intelligence, the blow molded plastics market was valued at USD 93.57 billion in 2025 and is estimated to grow from USD 98.22 billion in 2026 to reach USD 126.35 billion by 2031, at a CAGR of 5.17% during the forecast period (2026-2031).
This report is Segmented by Resin (Polyethylene (PE), Polyethylene Terephthalate (PET), and More), Molding Method (Extrusion Blow Molding (EBM), Injection Blow Molding (IBM), and More), Application (Food and Beverage, Pharmaceutical and Healthcare, and More), and Geography (Asia-Pacific, North America, Europe, South America and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Blow Molded Plastics Market Trends and Insights
Growing Replacement of Glass and Metal with Lightweight Plastic Packaging
Blow molded containers are gaining use in beverage, household chemical, and industrial packaging where operators value lower weight, dependable handling, and reduced breakage. The blow molded plastics market is supported by containers that can reduce shipment loads and work reliably on high-speed filling lines across consumer and industrial production sites. The blow molded containers can achieve 20% to 30% weight reductions compared with glass equivalents. This benefit can lower freight costs, reduce breakage losses, and improve handling during packaging and distribution operations. Polyethylene Terephthalate (PET) is extending into selected premium beverage formats, while narrow-neck production methods are being used to lower bottle weight. The move toward lighter containers gives converters a reason to invest in material-efficient designs without changing the basic functionality expected by brand owners.
Expanding Demand from the Food and Beverage Packaging Industry
Food and beverage accounted for 31.64% of demand in 2025 and remained the largest application base for the blow molded plastics market. Carbonated drinks, bottled water, dairy products, condiments, and functional beverages require large volumes of rigid packaging across established and developing consumer markets. Multi-layer co-extrusion allows producers to add oxygen, ultraviolet, and moisture barriers within a bottle wall during one manufacturing process. These structures can extend the shelf life of sensitive products while retaining the container characteristics required by retailers and brand owners. The EU Packaging and Packaging Waste Regulation is increasing interest in designs that support recyclability and reuse objectives. Brands are also using the International Sustainability and Carbon Certification Standard to verify recycled-resin content claims, which raises documentation requirements for packaging suppliers.
Rising Plastic Waste Management and Recycling Infrastructure Challenges
Collection and sorting capacity does not always match the circular-economy commitments made by packaging suppliers, brand owners, and public authorities. Multi-layer bottles can deliver strong barrier properties but remain harder to recycle at scale than simpler structures. This creates a tradeoff between product protection and end-of-life processing in the blow molded plastics market. The constraint is especially relevant to EVOH-barrier food bottles and multilayer High-Density Polyethylene (HDPE) automotive fuel tanks that serve demanding technical applications. South Asia and Southeast Asia face added pressure because collection systems may not meet the requirements of export customers seeking minimum recycled content. The EU Packaging and Packaging Waste Regulation requires packaging to be recyclable by 2030, increasing the compliance burden for converters that sell into regulated markets.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Use of Blow Molded Plastics in Pharmaceutical and Healthcare Packaging
- Rising Automotive Lightweighting and Electric Vehicle Component Production
- Volatility in Petrochemical Feedstock and Plastic Resin Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene held 38.92% of revenue in 2025 and represented the largest resin segment in the blow molded plastics market. Its cost profile, chemical resistance, and compatibility with extrusion blow molding and co-extrusion support high-volume packaging and industrial applications. HDPE is used widely in industrial containers, household chemical bottles, and bulk packaging drums. LDPE and LLDPE support softer formats that require squeezing, flexibility, or controlled dispensing. PET remains another important resin because of its clarity, barrier performance, and recycling options, which suit beverage, personal care, and pharmaceutical bottles. The installed base of Injection Stretch Blow Molding (ISBM) equipment in the Asia-Pacific and North America also supports PET processing.
Bio-based and recycled plastics are projected to expand at an 8.02% CAGR through 2031 within the blow molded plastics market. PP serves specialized automotive and medical uses within the blow molded plastics market, while PVC is used in industrial containers. ABS and PC are used in electronic and safety-critical applications that require more specific properties. PA has an expanding role in electric vehicle fluid-management systems because it handles heat and chemicals more effectively than PE or PP in demanding settings. LyondellBasell's 2025 FDA letters for recycled PP and HDPE offer a formal pathway for selected food-contact and personal-care applications. Verified content standards can help suppliers show that recycled and bio-based resin claims are supported by traceable documentation.
Complete Report Scope:
- By Resin
- Polyethylene (PE)
- Polyethylene Terephthalate (PET)
- Polypropylene (PP)
- Polyvinyl Chloride (PVC)
- Polystyrene (PS)
- Acrylonitrile Butadiene Styrene (ABS)
- Polycarbonate (PC)
- Polyamide (PA)
- Bio-based and Recycled Plastics
- Other Resins
- By Molding Method
- Extrusion Blow Molding (EBM)
- Injection Blow Molding (IBM)
- Injection Stretch Blow Molding (ISBM)
- Co-Extrusion Blow Molding
- By Application
- Food and Beverage
- Pharmaceutical and Healthcare
- Personal Care and Cosmetics
- Household Chemicals
- Automotive and Transportation
- Building and Construction
- Electrical and Electronics
- Industrial Manufacturing
- Agriculture
- Consumer Goods
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 48.33% of global revenue in 2025 and is forecast to grow at a 5.96% CAGR through 2031. This performance gives the region the leading share and growth rate in the blow molded plastics market. China's petrochemical clusters in Guangdong and Zhejiang support efficient raw material flows to downstream converters and packaging operations. India's pharmaceutical manufacturing expansion supports demand for precise and tamper-evident containers. Japan and South Korea maintain a premium role in high-specification pharmaceutical and semiconductor component packaging.
North America has an established base of molding assets, contract packaging operations, automotive production, and pharmaceutical packaging investment. Graham Packaging announced a USD 35 million expansion and modernization project for its Hammond, Louisiana, facility, with upgrades targeted for completion by 2027. Europe is becoming more value-intensive as Packaging and Packaging Waste Regulation (PPWR) requirements redirect investment toward monomaterial and recycled-content structures. Germany, France, Italy, and the UK are important markets for these changes. Suppliers that can provide compliant rigid containers can strengthen their position with consumer goods companies.
South America and Middle-East and Africa offer distinct sources of demand for the blow molded plastics market. Brazil and Argentina support South American consumption through food processing and agrochemical packaging. Saudi Arabia and South Africa lead in Middle-East and Africa, where Gulf Cooperation Council petrochemical integration supports resin-to-packaging conversion. Urbanization and consumer goods penetration create longer-term demand across Sub-Saharan Africa. Recycling and collection gaps can complicate sustainability compliance for multinational converters. Greif completed the acquisition of Envaplast in Spain in June 2026, adding a manufacturing platform that supports its Europe and Middle-East and Africa polymer-packaging expansion.
- ALPLA
- Altium Packaging
- Amcor plc
- Comar, LLC
- Gerresheimer AG
- Graham Packaging
- Greif Inc.
- Inpress Plastics Ltd.
- Mauser Packaging Solutions
- Plastipak Holdings, Inc.
- Pretium Packaging, L.L.C.
- Retal Industries Ltd.
- Serioplast S.p.A.
- Silgan Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Replacement of Glass and Metal with Lightweight Plastic Packaging
- 4.2.2 Expanding Demand from the Food & Beverage Packaging Industry
- 4.2.3 Increasing Use of Blow Molded Plastics in Pharmaceutical and Healthcare Packaging
- 4.2.4 Rising Automotive Lightweighting and Electric Vehicle Component Production
- 4.2.5 Growing Adoption of Recycled and Bio-Based Resins in Blow Molding Applications
- 4.3 Market Restraints
- 4.3.1 Rising Plastic Waste Management and Recycling Infrastructure Challenges
- 4.3.2 Volatility in Petrochemical Feedstock and Plastic Resin Prices
- 4.3.3 Growing Competition from Flexible Packaging, Paper-Based Packaging, and Alternative Materials
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polyethylene Terephthalate (PET)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Polyvinyl Chloride (PVC)
- 5.1.5 Polystyrene (PS)
- 5.1.6 Acrylonitrile Butadiene Styrene (ABS)
- 5.1.7 Polycarbonate (PC)
- 5.1.8 Polyamide (PA)
- 5.1.9 Bio-based and Recycled Plastics
- 5.1.10 Other Resins
- 5.2 By Molding Method
- 5.2.1 Extrusion Blow Molding (EBM)
- 5.2.2 Injection Blow Molding (IBM)
- 5.2.3 Injection Stretch Blow Molding (ISBM)
- 5.2.4 Co-Extrusion Blow Molding
- 5.3 By Application
- 5.3.1 Food and Beverage
- 5.3.2 Pharmaceutical and Healthcare
- 5.3.3 Personal Care and Cosmetics
- 5.3.4 Household Chemicals
- 5.3.5 Automotive and Transportation
- 5.3.6 Building and Construction
- 5.3.7 Electrical and Electronics
- 5.3.8 Industrial Manufacturing
- 5.3.9 Agriculture
- 5.3.10 Consumer Goods
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ALPLA
- 6.4.2 Altium Packaging
- 6.4.3 Amcor plc
- 6.4.4 Comar, LLC
- 6.4.5 Gerresheimer AG
- 6.4.6 Graham Packaging
- 6.4.7 Greif Inc.
- 6.4.8 Inpress Plastics Ltd.
- 6.4.9 Mauser Packaging Solutions
- 6.4.10 Plastipak Holdings, Inc.
- 6.4.11 Pretium Packaging, L.L.C.
- 6.4.12 Retal Industries Ltd.
- 6.4.13 Serioplast S.p.A.
- 6.4.14 Silgan Holdings Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


