

|
시장보고서
상품코드
2119236
육불화황 대체 전기 절연 가스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Sulfur Hexafluoride Replacement Electrical Insulating Gases - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
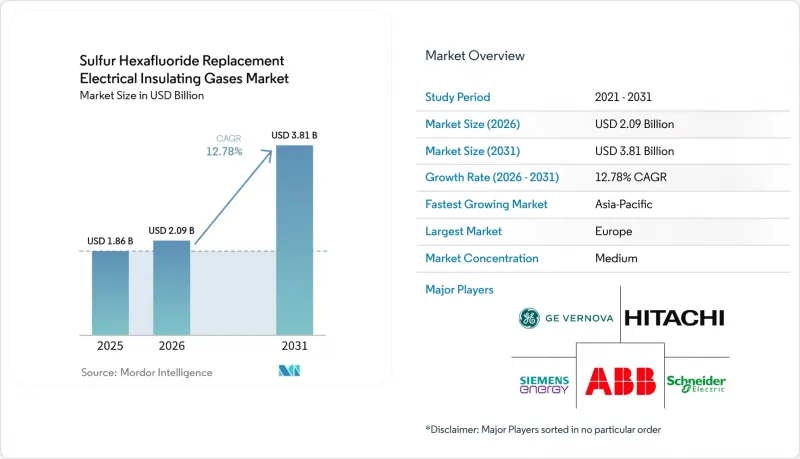
에 의하면, 육불화황 대체 전기 절연 가스 시장 규모는 2025년에 18억 6,000만 달러로 평가되었습니다. 2026년 20억 9,000만 달러에서 2031년까지 38억 1,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 12.78%를 나타낼 전망입니다.
본 보고서는 가스 화학(드라이 에어/테크니컬 에어, 기타), 용도(차단기, 기타), 수요 유형(OEM 초기 충전, 기타), 기술 구성(가스 절연 기술, 기타), 최종 사용자 산업(산업 시설, 기타), 지역(아시아태평양, 기타)별로 세분화되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시됩니다.
세계의 육불화황 대체 전기 절연 가스 시장 동향 및 인사이트
SF6 단계적 폐지 규정 및 전력 사업자의 조달 전환
EU 규정 2024/573은 신규 개폐 장치에 대한 육불화황(SF6) 사용에 대한 단계적 제한 일정을 규정하고 있으며, 전력 사업자에게 사양 업데이트를 위한 명확한 일정을 제시하고 있습니다. 24 kV 이하의 중전압 신규 기기에 대한 규제는 2026년 1월에 발효되었으며, 52-145 kV 기기에 대한 규제는 2028년에, 145 kV를 초과하는 기기에 대한 규제는 2032년에 시행될 예정입니다. 또한, 유럽연합 집행위원회 시행규칙 2025/627에서는 고정식 전기 개폐 장치의 취급에 대해 인증된 담당자의 배치를 의무화하고 있어, SF6 장비를 유지 관리하는 데 있어 운영상의 부담이 증가하고 있습니다. 2026년 규정은 창고에 보관 중인 신규 설비와 2025년 12월 31일 시점에서 가동되지 않았던 계획 중인 설비에 적용됩니다. Thuga는 기한 전에 Siemens Energy와 Schneider Electric의 SF6 프리 제품군을 사전 인증하여, 다른 유럽 전력 회사들도 참고할 수 있는 조달 방안을 제시했습니다. 따라서 SF6 대체 전기 절연 가스 시장은 기한에 따른 수요 증가에 앞서, 적합 제품을 확보하기 위한 조기 프레임워크 계약에 달려 있습니다.
송전망 현대화 및 노후화된 고전압 자산의 교체
송전망 설비의 노후화에 따라 전력 회사가 고전압 자산을 갱신하는 과정에서 SF6 프리 설계를 우선시하는 갱신 주기가 형성되고 있습니다. 2026년 국제대전력망협의회(CIGRE)의 분석에 따르면, 네트워크 확장과 구형 자산의 폐기에 따라 2050년까지 교류 차단기 설치 대수가 40-60% 증가할 것으로 예측됩니다. 동 분석에 따르면, SF6 프리 기술로의 전환을 가속화하면 현상 유지 시나리오와 비교해 SF6 배출량을 20% 가까이 줄일 수 있는 반면, 도입이 지연될 경우 최대 75% 더 많은 차단기가 필요할 가능성이 있습니다. 각국의 송전 사업자는 기술 사양에 따라 장기 조달 프레임워크에 어떤 제품이 채택될지가 결정되기 때문에 이는 수요에 영향을 미치고 있습니다. 이러한 프레임워크에 SF6 프리 요건을 포함시키는 전력 회사는 공급이 부족한 기간에도 인증된 장비에 대한 접근성을 개선할 수 있습니다. SF6 대체 전기 절연 가스 시장에서 대체 주기는 단순한 장비 교체에 그치지 않고 새로운 시험 프로토콜, 서비스 계약, 가스 관리 기법도 필요로 합니다.
SF6를 사용하지 않는 장비의 높은 초기 비용
연간 설비 투자 예산을 주요 기준으로 프로젝트를 평가하는 전력 사업자에게 있어 초기 설비 가격은 여전히 장벽으로 작용하고 있습니다. 이러한 비용 차이는 규제 준수가 그다지 시급하지 않은 남미, 중동 및 아프리카에서 특히 두드러집니다. 가스 구매 비용, 누출 감지, 규제 당국에 대한 보고 등을 고려하면, 30년에 걸친 설비 수명 기간 동안의 총 소유 비용은 개선될 가능성이 있습니다. 그러나 이러한 장기적인 관점이 개별 프로젝트에 대한 투자 승인을 반드시 결정짓는 것은 아닙니다. 중전압 청정 공기 제품은 생산량 증가로 인한 혜택을 볼 가능성이 있지만, 초고전압 가스 시스템의 경우 여전히 전문적인 조정과 취급이 필요합니다. 그 결과, SF6 대체 전기 절연 가스 시장은 규제 압력이나 자금 조달 관행이 다른 지역에 따라 도입률이 편차를 보일 가능성이 높다고 생각됩니다.
부문별 분석
플루오로니트릴-CO2 혼합 가스는 2025년 가스 화학 부문 매출의 41.45%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 13.12%를 나타낼 것으로 예측되어, 이 카테고리는 고전압 용도에서 주도적인 위치를 차지하게 될 것입니다. 이 혼합 가스는 유전 요구 사항으로 인해 단순한 절연 가스의 사용이 제한되는 설치 환경에 대응합니다. 기존 SF6 인클로저 크기와 호환되므로, 장비 교체에 따른 토목 공사 변경을 최소화할 수 있습니다. 플루오로니트릴 계열 시스템은 송전 변전소 및 해상 용도에서 컴팩트한 설계를 가능하게 합니다. 이 화학 성분의 SF6 대체 전기 절연 가스 시장 규모는 기존 설치 장소에 적합한 장비를 찾는 전력 회사에 의해 뒷받침되고 있습니다.
드라이 에어 또는 테크니컬 에어는 중전압 부문에서 금속 밀폐형 개폐 장치(GIS)의 진공 차단 기구와 연동하여 독자적인 역할을 수행하고 있습니다. SF6에 비해 유전 성능이 낮기 때문에 고전압 수준에서는 더 큰 치수나 더 높은 압력이 필요할 수 있습니다. CIGRE는 클린 에어 GIS에 대해, 국제전기표준회의(IEC) 62271-4의 기준 범위 내에서의 밀봉 성능 및 기밀성을 포함하여, 장기적인 신뢰성이 허용 범위 내에 있다고 보고하고 있습니다. 또한, 플루오로케톤계 혼합 가스는 혼합 가스의 안정성이 중요한 ‘평생 밀봉형’ 중전압 제품에도 사용되고 있습니다. 그 결과, 클린에어는 보다 단순한 중전압 요구 사항을 충족하고, 플루오로니트릴계 혼합 가스는 가혹한 송전 조건에 대응하는 등, 서로를 보완하는 화학 조성의 조합이 실현되고 있습니다.
가스 절연 개폐 장치(GIS)는 2025년에 SF6 대체 전기 절연 가스 시장의 47.23% 점유율을 차지했으며, 이는 소형 송배전 변전소에서 GIS가 수행하는 역할을 반영합니다. GIS는 도시 지역의 부지 제약, 지하 설치, 해상 설비로 인해 공기 절연 설계가 현실적이지 않은 장소에서 여전히 중요한 역할을 수행하고 있습니다. 또한 밀폐된 장치 케이스 내에 디지털 센서를 탑재할 수 있습니다. 링 메인 유닛과 차단기는 2차 배전 분야에서 여전히 중요한 용도 범주입니다. 유럽의 배전 사업자들은 새로운 장비 규제가 시행됨에 따라 체계적인 중전압 장비 교체 프로그램을 시작하고 있습니다.
가스 절연 송전선(GIL)은 2031년까지 연평균 성장률(CAGR) 13.31%를 나타낼 것으로 예측되며, 가장 빠르게 성장하는 용도 부문이 될 전망입니다. 이 성장률은 이미 설치된 GIL 회랑에 대한 현장 가스 보충 절차가 상업적으로 인증된 사실을 반영하고 있습니다. 420 kV에서의 형식 시험과 ‘Nan 변전소’ 프로젝트는 전력 사업자들에게 자산의 완전한 교체를 대체할 수 있는 가스 교체 사례를 보여주고 있습니다. 2035년에 예정된 미사용 SF6에 대한 유지보수 제한은 자산 소유자에게 명확한 의사 결정의 분기점이 될 것입니다. SF6 대체 전기 절연 가스 시장은 신규 GIS 수주와 기존 GIL 시스템 전환에 관한 이전 결정 모두에 의해 뒷받침되고 있습니다.
지역별 분석
2025년, 유럽은 SF6 대체 전기 절연 가스 시장 점유율의 38.12%를 차지했습니다. 이 지역은 법적 구속력이 있는 규제, 확립된 OEM 공급망, 송전 시스템 운영 사업자의 적극적인 조달의 혜택을 받고 있습니다. 독일은 주요 참조 시장으로 자리 잡고 있으며, TenneT Germany는 2026년 6월 에르츠하우젠에서 420 kV SF6 프리 GIS 시험을 완료했습니다. GE Vernova는 RTE를 위해 최초의 245 kV SF6 프리 가스 절연 변전소를 납품할 예정이며, 이는 프랑스 고전압 분야에서의 주요 실적을 더욱 확대하게 될 것입니다. 북미에는 연방 차원의 SF6 규제는 없지만, 각 주의 조달 지침 및 송전망 현대화 프로그램에서 SF6 프리 요건이 점점 더 중요하게 여겨지고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 13.50%를 나타낼 것으로 예측되어, 가장 빠르게 성장하는 지역이 될 전망입니다. 중국에서는 국가전망(State Grid)의 도입을 통해 최고 전압 수준에서의 구축이 진행되고 있습니다. 히타치 에너지에 따르면, 2026년 5월 우한에 위치한 국가전망공사(SGCC)의 옥현 500 kV 변전소에서 550 kV SF6 프리 GIS가 가동에 들어갔습니다. 일본에서는 전력 회사 주도의 프로그램을 통해 진전이 보이고 있습니다. 주부전력은 2026년 3월, 550 kV ‘EconiQ’ GIS를 발주했으며, 이 설치 공사에서는 550 kV GIS의 모든 구성 요소가 SF6 프리로 적용될 예정입니다. 이 지역의 움직임은 신규 송전망 건설과 장비 표준화라는 두 가지 측면을 통해 SF6 대체 전기 절연 가스 시장을 뒷받침하고 있습니다.
남미, 중동 및 아프리카에서는 설비 비용과 전문 서비스 제공 능력이 여전히 제약 요인으로 작용하고 있어 도입은 초기 단계에 있습니다. 브라질의 송전망 확장과 사우디아라비아의 전력 인프라 계획에 따라 신규 건설용 GIS 도입 기회가 생겨나고 있습니다. 현지 도입은 유럽 및 아시아태평양 제조업체의 제품과 공급 일정에 좌우됩니다. 호주는 인근 지역의 참고 사례가 되고 있으며, ElectraNet은 2026년 3월에 히타치 에너지(Hitachi Energy)사의 EconiQ 145kV 및 72.5kV 라이브 탱크형 차단기를 최초로 도입했습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the sulfur hexafluoride replacement electrical insulating gases market size was valued at USD 1.86 billion in 2025 and is estimated to grow from USD 2.09 billion in 2026 to reach USD 3.81 billion by 2031, at a CAGR of 12.78% during the forecast period (2026-2031).
This report is Segmented by Gas Chemistry (Dry/Technical Air and More), Application (Circuit Breakers and More), Demand Type (OEM First-Fill and More), Technology Configuration (Gas-Insulated Technology and More), End-User Industry (Industrial Facilities and More), and Geography (Asia-Pacific and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Sulfur Hexafluoride Replacement Electrical Insulating Gases Market Trends and Insights
SF6 Phase-Out Rules and Utility Procurement Conversion
EU Regulation 2024/573 establishes a phased restriction schedule for SF6 in new switchgear, giving utilities a firm timetable for updating specifications. Restrictions on new medium-voltage equipment up to 24 kV took effect in January 2026, while restrictions for 52-145 kV equipment are due in 2028 and for equipment above 145 kV in 2032. Commission Implementing Regulation 2025/627 also requires certified personnel to handle stationary electrical switchgear, increasing the operational burden of retaining SF6 equipment. The 2026 rule applies to new equipment held in warehouses and to planned installations that were not operational by December 31, 2025. Thuga pre-qualified SF6-free product ranges from Siemens Energy and Schneider Electric before the deadline, offering a procurement approach that other European utilities can replicate. The SF6-replacement electrical insulating gases market, therefore, depends on early framework agreements that secure compliant products before deadline-driven demand increases.
Grid Modernization and Aging High-Voltage Asset Replacement
Aging grid equipment is creating a replacement cycle that favors SF6-free designs as utilities renew high-voltage assets. A 2026 Conseil International des Grands Reseaux Electriques (CIGRE) analysis projected a 40-60% increase in the AC circuit breaker population by 2050 as networks expand and older assets retire. The same analysis found that a faster transition to SF6-free technology could reduce SF6 emissions by nearly 20% relative to a business-as-usual scenario, while a delayed rollout could require up to 75% more circuit breakers. National transmission operators influence demand because their technical specifications determine which products can enter long-term procurement frameworks. Utilities that include SF6-free requirements in those frameworks can improve access to certified equipment during periods of constrained supply. For the SF6-replacement electrical insulating gases market, the replacement cycle extends beyond simple equipment substitution, as it also requires new testing protocols, service arrangements, and gas management practices.
Higher Initial Cost of Non-SF6 Equipment
Initial equipment prices remain a barrier for utilities that evaluate projects primarily through annual capital expenditure budgets. This cost difference is particularly significant in South America, the Middle-East, and Africa, where compliance mandates are less immediate. Total ownership costs can improve over a 30-year equipment life when operators account for gas purchases, leak detection, and regulatory reporting. However, this longer-term view does not always determine investment approvals for individual projects. Medium-voltage clean-air products may benefit from higher manufacturing volumes, while extra-high-voltage gas systems still require specialist conditioning and handling. As a result, the SF6-replacement electrical insulating gases market is likely to show varying adoption rates across regions with differing regulatory pressures and financing practices.
Other drivers and restraints analyzed in the detailed report include:
- Offshore Wind and High Voltage Direct Current (HVDC) Substation Expansion
- High-Voltage Retrofill Demand for Installed Gas-Insulated Assets
- High-Voltage Procurement Lead Times and Limited Production Slots
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fluoronitrile-CO2 blends held 41.45% of 2025 gas chemistry revenue and are forecast to grow at a 13.12% CAGR through 2031, giving the category the leading position in high-voltage applications. The blends support installations where dielectric requirements limit the use of simpler insulating gases. Their compatibility with existing SF6 enclosure footprints can reduce civil changes during equipment replacement. Fluoronitrile systems support compact designs for transmission substations and offshore applications. The SF6-Replacement Electrical Insulating Gases Market size for this chemistry is supported by utilities seeking equipment that fits existing sites.
Dry or technical air serves a distinct role at medium voltage, where it works with vacuum interruption in metal-enclosed switchgear. Its lower dielectric performance compared to SF6 may require larger dimensions or higher pressure at higher voltage levels. CIGRE reported acceptable long-term reliability for clean-air GIS, including seal performance and gas tightness within International Electrotechnical Commission (IEC) 62271-4 thresholds. Fluoroketone-based blends also serve sealed-for-life medium-voltage products where mixture stability is important. The resulting chemistry mix is complementary, with clean air serving simpler medium-voltage needs and fluoronitrile blends addressing demanding transmission conditions.
Gas-Insulated Switchgear (GIS) held 47.23% of the SF6-Replacement Electrical Insulating Gases Market share in 2025, reflecting its role in compact transmission and distribution substations. GIS remains important where urban land constraints, underground sites, and offshore installations make air-insulated designs impractical. It can accommodate digital sensors within sealed equipment enclosures. Ring Main Units and circuit breakers remain important application categories in secondary distribution. European distribution operators have begun structured medium-voltage replacement programs as new equipment restrictions take effect.
Gas-Insulated Lines (GIL) are forecast to grow at a 13.31% CAGR through 2031, making them the fastest-growing application segment. This rate reflects the commercial qualification of on-site retrofill procedures for installed GIL corridors. Type testing at 420 kV and the Nan Substation project give utilities examples of gas substitution in place of complete asset replacement. The 2035 maintenance restriction on virgin SF6 creates a defined decision point for asset owners. The SF6-Replacement Electrical Insulating Gases Market is supported by both new GIS orders and earlier decisions to convert installed GIL systems.
Complete Report Scope:
- By Gas Chemistry
- Fluoronitrile-CO2 Blends
- Fluoroketone-Based Blends
- Dry/Technical Air
- Others
- By Application
- Gas-Insulated Switchgear (GIS)
- Ring Main Units (RMUs)
- Circuit Breakers
- Gas-Insulated Lines (GILs)
- Others
- By Demand Type
- OEM First-Fill
- Retrofit and Retrofill
- Maintenance Refill
- By Technology Configuration
- Gas-Insulated Technology
- Vacuum Interruption with Clean-Air Insulation
- Others
- By End-User Industry
- Transmission and Distribution Utilities
- Renewable Energy Projects
- Industrial Facilities
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Europe held 38.12% of the SF6-replacement electrical insulating gases market share in 2025. The region benefits from binding restrictions, established OEM supply chains, and active procurement by transmission system operators. Germany serves as a key reference market, with TenneT Germany completing testing of a 420 kV SF6-free GIS at Erzhausen in June 2026. GE Vernova is set to deliver the first 245 kV SF6-free gas-insulated substation for RTE, extending high-voltage reference activity in France. North America has no federal SF6 mandate, but state procurement guidelines and grid modernization programs are increasingly favoring SF6-free requirements.
Asia-Pacific is forecast to grow at a 13.50% CAGR through 2031, making it the fastest-growing geography. China is advancing at the highest voltage levels through State Grid deployments. Hitachi Energy reported that a 550 kV SF6-free GIS was energized at SGCC's Yuxian 500 kV substation in Wuhan in May 2026. Japan is progressing through utility-led programs, with Chubu Electric Power Grid ordering 550 kV EconiQ GIS in March 2026 for an installation in which all 550 kV GIS components will be SF6-free. This regional activity supports the SF6-replacement electrical insulating gases market through both new transmission construction and equipment standardization.
South America, the Middle-East, and Africa are at an earlier stage of adoption, as equipment costs and specialist service capacity remain constraints. Brazil's grid expansion and Saudi Arabia's power infrastructure programs create new-build GIS opportunities. Local adoption depends on products and supply schedules from European and Asia-Pacific manufacturers. Australia provides a nearby reference case, with ElectraNet accepting its first EconiQ 145 kV and 72.5 kV live-tank circuit breakers from Hitachi Energy in March 2026.
- ABB
- CG Power & Industrial Solutions Ltd.
- Eaton
- Fuji Electric Co.,Ltd.
- GE Vernova
- HD Hyundai Electric Co., Ltd.
- Hitachi Energy Ltd
- Hyosung
- Lucy Group Ltd.
- MEIDENSHA CORPORATION
- Mitsubishi Electric Corporation
- NISSIN ELECTRIC Co.,Ltd.
- Schneider Electric
- Siemens Energy
- TE Connectivity
- TOSHIBA CORPORATION
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 SF6 Phase-Out Rules and Utility Procurement Conversion
- 4.2.2 Grid Modernization and Aging High-Voltage Asset Replacement
- 4.2.3 Offshore Wind and HVDC Substation Expansion
- 4.2.4 Urban Space Constraints Favoring Compact GIS
- 4.2.5 High-Voltage Retrofill Demand for Installed GIL Assets
- 4.2.6 Utility Digitalization and Condition-Based Maintenance
- 4.3 Market Restraints
- 4.3.1 Higher Initial Cost of Non-SF6 Equipment
- 4.3.2 High-Voltage Procurement Lead Times and Limited Production Slots
- 4.3.3 Voltage-Class and Footprint Limits of Dry-Air Systems
- 4.3.4 Long Replacement Cycles and Economical SF6 Leak-Repair Programs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Gas Chemistry
- 5.1.1 Fluoronitrile-CO2 Blends
- 5.1.2 Fluoroketone-Based Blends
- 5.1.3 Dry/Technical Air
- 5.1.4 Others
- 5.2 By Application
- 5.2.1 Gas-Insulated Switchgear (GIS)
- 5.2.2 Ring Main Units (RMUs)
- 5.2.3 Circuit Breakers
- 5.2.4 Gas-Insulated Lines (GILs)
- 5.2.5 Others
- 5.3 By Demand Type
- 5.3.1 OEM First-Fill
- 5.3.2 Retrofit and Retrofill
- 5.3.3 Maintenance Refill
- 5.4 By Technology Configuration
- 5.4.1 Gas-Insulated Technology
- 5.4.2 Vacuum Interruption with Clean-Air Insulation
- 5.4.3 Others
- 5.5 By End-User Industry
- 5.5.1 Transmission and Distribution Utilities
- 5.5.2 Renewable Energy Projects
- 5.5.3 Industrial Facilities
- 5.5.4 Others
- 5.6 By Geography
- 5.6.1 Asia-Pacific
- 5.6.1.1 China
- 5.6.1.2 India
- 5.6.1.3 Japan
- 5.6.1.4 South Korea
- 5.6.1.5 ASEAN Countries
- 5.6.1.6 Rest of Asia-Pacific
- 5.6.2 North America
- 5.6.2.1 United States
- 5.6.2.2 Canada
- 5.6.2.3 Mexico
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 NORDIC Countries
- 5.6.3.6 Rest of Europe
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle-East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 South Africa
- 5.6.5.3 Rest of Middle-East and Africa
- 5.6.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 ABB
- 6.4.2 CG Power & Industrial Solutions Ltd.
- 6.4.3 Eaton
- 6.4.4 Fuji Electric Co.,Ltd.
- 6.4.5 GE Vernova
- 6.4.6 HD Hyundai Electric Co., Ltd.
- 6.4.7 Hitachi Energy Ltd
- 6.4.8 Hyosung
- 6.4.9 Lucy Group Ltd.
- 6.4.10 MEIDENSHA CORPORATION
- 6.4.11 Mitsubishi Electric Corporation
- 6.4.12 NISSIN ELECTRIC Co.,Ltd.
- 6.4.13 Schneider Electric
- 6.4.14 Siemens Energy
- 6.4.15 TE Connectivity
- 6.4.16 TOSHIBA CORPORATION
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

(주말 및 공휴일 제외)


