|
시장보고서
상품코드
2119263
기술 기반 조직 기술 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Skills-Based Organization Technology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
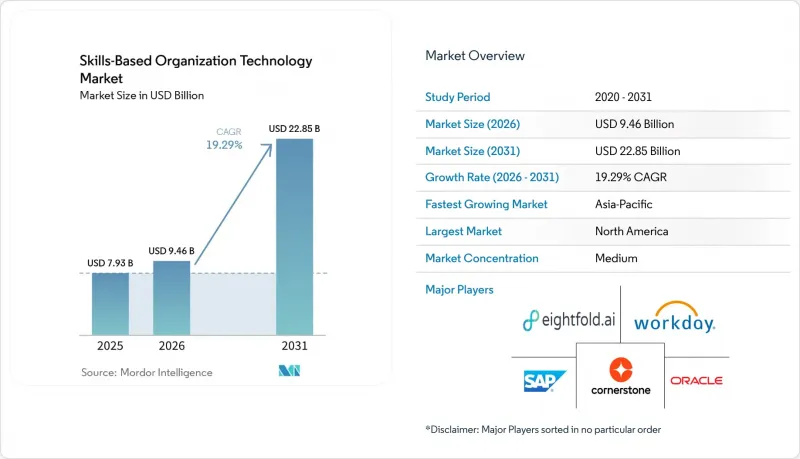
에 의하면, 기술 기반 조직 기술 시장 규모는 2025년에 79억 3,000만 달러로 평가되었습니다. 2026년 94억 6,000만 달러에서 2031년까지 228억 5,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 19.29%를 나타낼 전망입니다.
본 보고서는 구성 요소(플랫폼 및 서비스), 배포 모델(클라우드, On-Premise, 하이브리드), 기업 규모(대기업, 중소기업), 용도(사내 인재 유동화 등), 최종 사용자 산업(IT 및 통신 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 단위로 표시되어 있습니다.
세계의 기술 기반 조직 기술 시장 동향 및 인사이트
직무 중심에서 기술 중심으로의 운영 모델 전환
직무명에 기반한 인재 설계에서 벗어나는 것은 여전히 기술 기반 조직을 위한 기술 시장의 가장 강력한 촉진요인으로 작용하고 있습니다. Workday는 2025년 4월, 경영진의 불과 32%만이 현재 직원의 기술이 미래의 요구 사항에 부합한다고 확신하고 있다고 보고했습니다. 이로 인해 조직은 역량 데이터를 지속적으로 갱신하는 시스템 도입을 서두르고 있습니다. 같은 조사에 따르면, 55%의 조직이 이미 기술 기반 운영 모델로의 전환을 시작했으며, 추가로 23%가 12개월 이내에 전환할 계획인 것으로 나타나, 이 모델이 얼마나 빠르게 표준 관행으로 자리 잡고 있는지를 보여줍니다. 기업들이 단순히 직원 수뿐만 아니라 기술 자체를 파악하기 시작함에 따라, 인재 계획은 더욱 지속 가능한 형태로 변모하고 있으며, 고정된 채용 주기에 대한 의존도는 낮아지고 있습니다. 이에 따라 구매 담당자들은 단일 기술 계층에서 재배치, 학습, 계획을 지원할 수 있는 플랫폼을 점점 더 요구하게 되었고, 조달 행태에 변화가 일어나고 있습니다. 따라서 기술 기반 조직을 위한 기술 시장은 기업이 ‘업무’ 자체를 정의하는 방식에 대한 구조적 변화에 의해 형성되고 있습니다.
AI를 활용한 대규모 기술 추론 및 매칭
AI 기반 추론은 기술 기반 조직을 위한 기술 시장에서 오랫동안 지속되어 온 데이터 문제를 완화했습니다. 이는 본인 신고나 상사의 보고에 기반한 기술 데이터는 깊이가 부족하고 금세 구식이 되어버리는 경우가 많기 때문입니다. 최신 시스템은 작성한 컨텐츠, 이수한 교육, 협업 패턴과 같은 신호로부터 역량을 추론할 수 있어, 데이터의 포괄성과 업데이트 빈도를 향상시키고 있습니다. Gloat사는 2026년 3월, 자사의 Loomra 엔진이 240만 개의 기술 노드와 1,870만 개의 기술 관계로 구성된 기술 그래프에서 작동하고 있다고 발표하며, 각 벤더들이 실시간 인력 활용을 위해 대규모 추론 인프라를 구축하고 있는 실태를 보여주었습니다. 또한 Workday사는 직책명과 같은 최소한의 구조화된 입력 정보로부터 관련 스킬을 추론하는 기술적 과제에 대해서도 언급하며, 저지연 추론이 단순한 부가 기능이 아닌 핵심 제품 기능으로 자리 잡고 있음을 시사하고 있습니다. 추론 정확도의 향상은 기존 분류 체계에서는 간과되었던 스킬을 밝혀내고, 사내 이동 및 인재 계획의 신뢰성을 높이기 때문에 비즈니스적으로 중요한 의미를 지닙니다. 이는 신입 사원의 행동 하나하나가 사업 전반에서 활용되는 데이터 레이어를 개선하게 되므로, 시간이 지남에 따라 플랫폼의 가치를 강화하는 결과로 이어집니다.
직원의 데이터 개인정보 보호 및 AI 거버넌스 부담
개인정보 보호와 거버넌스는 여전히 기술 기반 조직을 위한 기술 시장에서 가장 시급한 제약 요인으로 남아 있습니다. 기술 추론 시스템은 작성한 컨텐츠, 프로젝트 이력, 협업 활동 등 수동적인 업무 신호를 분석하는 경우가 많으며, 이러한 신호가 채용 결정에 재사용될 경우 동의 및 투명성에 대한 의문이 제기됩니다. 캘리포니아주 민권위원회는 2025년 6월, 2025년 10월에 발효될 자동 의사결정 시스템에 대한 규정을 최종 확정했습니다. 이 규정에 따라 해당 도구에 대해서는 편향 방지 테스트, 기록 보관 및 광범위한 감독이 의무화됩니다. 또한, EU의 AI법에 따라 고용 관련 AI 시스템에 대한 심사가 강화되면서, 조달 및 도입 시 문서화, 심사, 감독 요건이 증가하고 있습니다. 이러한 의무는 이미 법무, 엔지니어링, 감사 자원을 갖추고 있는 대규모 벤더에게 유리하게 작용하는 경향이 있습니다. 아울러 구매자가 도입 승인을 받는 데 시간이 소요되고, 많은 경우 초기 단계부터 거버넌스 관리를 포함하도록 프로젝트 범위를 확대함에 따라 지출 계상이 지연되는 결과로 이어지기도 합니다.
부문 분석
2025년 기술 기반 조직을 위한 기술 시장에서 플랫폼 소프트웨어는 72.41%의 점유율을 차지했으며, 이는 구매자가 여전히 핵심 온톨로지, 추론 및 의사 결정 계층을 가장 중요하게 여긴다는 사실을 뒷받침합니다. 모빌리티, 학습, 계획을 포함한 대부분의 하류 이용 사례는 지속적으로 갱신 가능한 영구적인 스킬 그래프에 의존하고 있으므로, 이러한 우위는 앞으로도 유지될 전망입니다. 플랫폼 소프트웨어 중에서는 스킬 인텔리전스 및 온톨로지 플랫폼이 기반 계층을 형성하고, 그 위에 인재 인텔리전스,사내 이동 및 인재 계획 모듈이 구축되어 있습니다. 많은 기업이 핵심 온톨로지 프로젝트를 통해 기술 기반 조직을 위한 기술 시장에 진입하고, 데이터 계층이 실질적인 신호를 제공하기 시작한 후에 지출을 확대해 나가기 때문에 이 순서는 중요합니다.
서비스 시장은 2026년부터 2031년까지 연평균 성장률(CAGR) 22.67%로 확대될 것으로 예측됩니다. 이는 대규모의 분산된 직원 기반 전체에 스킬 인프라를 구축하는 데 필요한 도입 공수를 반영한 것입니다. 구매 기업들은 분류 체계 설계, 변경 관리, 거버넌스 및 통합에 대한 지원이 필요하며, 이러한 요구는 소프트웨어 가동 후에도 계속됩니다. 2026년 1월 Docebo가 365Talents를 인수한 것은 벤더들이 기술 식별을 보다 광범위한 학습 시스템 내의 개발 활동과 직접 연결하고자 하는 욕구가 점점 더 커지고 있음을 보여줍니다. 이러한 움직임은 또한 기술 기반 조직을 위한 기술 시장에서 서비스가 단순한 설정 작업에 그치지 않고 지속적인 운영 지원으로 확대될 것임을 시사합니다. 에이전트 기반 기능이 보급됨에 따라 기업들은 관리형 거버넌스, 정책 설정, 워크플로우 모니터링에도 더 많은 비용을 투자하게 될 것입니다. 이로 인해 플랫폼 소프트웨어가 여전히 주요 수익원임에도 불구하고, 서비스는 구조적으로 중요한 위치를 계속 차지하게 될 것입니다.
2025년 시점에서 클라우드가 기술 기반 조직 기술 시장 규모의 68.92%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 23.83%를 기록하며 가장 빠르게 성장하는 도입 모델이 될 것으로 전망됩니다. 이러한 조합은 기업 소프트웨어에서는 이례적인 것으로, 실시간 추론, 온톨로지 업데이트 및 다중 시스템 통합이 클라우드 아키텍처를 얼마나 강력하게 뒷받침하고 있는지를 보여줍니다. 규제가 엄격한 환경에서는 On-Premise 배포가 여전히 중요하지만, 스킬 데이터를 지속적으로 업데이트하고 여러 워크플로우 간에 공유해야 하는 경우 그 유지 관리가 어려워집니다. 많은 구매자에게 있어 스킬 기반 조직 기술 시장은 더 이상 기존의 인사 소프트웨어 구매라기보다는 규모,속도, 업데이트 빈도를 필요로 하는 데이터 계층 수준의 의사결정으로 보이기 시작했습니다.
일부 대기업의 경우, 직원 데이터의 처리 및 저장 위치를 보다 엄격하게 관리해야 하므로 하이브리드 도입은 여전히 전략적으로 중요합니다. 이는 특히 유럽에서 두드러지며, 소버린 클라우드에 대한 선호나 현지 규정 준수 의무가 플랫폼 설계 및 벤더 선정에 영향을 미칠 수 있습니다. 도이치 텔레콤이 2025년부터 2026년에 걸쳐 전개할 AI 탑재형 ‘Growth Hub’는 대기업이 세계 플랫폼 전략과 국내 거버넌스 요건을 어떻게 양립시키고 있는지를 보여줍니다. 이러한 추세로 볼 때, 하이브리드가 도입 규모 측면에서 클라우드를 능가하지는 않겠지만, 규제가 엄격한 대기업에서는 앞으로도 확고한 역할을 계속 수행할 것임을 시사합니다. 운영상의 유연성과 지역별 관리를 모두 지원할 수 있는 벤더는 다국적 기업 대상 프로그램을 수주하는 데 유리한 입장에 있습니다. 이는 또한 기술 기반 조직을 위한 기술 시장에서 도입 선택이 단순한 IT 선호도뿐만 아니라 거버넌스의 성숙도와 점점 더 밀접하게 연결되어 있음을 의미합니다.
지역별 분석
2025년, 북미는 기술 기반 조직 기술 시장 점유율의 41.64%를 차지하며, 지역별 매출 기준 중 가장 큰 비중을 차지했습니다. 미국은 디지털 성숙도가 높은 기업이 밀집해 있을 뿐만 아니라, HCM(인적 자본 관리) 및 인재 관리 소프트웨어에 대한 오랜 투자 실적을 갖추고 있어 여전히 핵심 수요 거점으로 자리 잡고 있습니다. 2025년 10월부터 시행될 캘리포니아주의 자동화된 의사 결정에 관한 규제 또한 AI를 활용한 고용 결정에 있어 감사 가능하고 설명 가능한 인력 데이터에 대한 필요성을 높이고 있습니다. 캐나다와 멕시코는 규모는 작지만, 캐나다는 기업 내 도입 경로가 미국과 유사하며, 멕시코에서는 제조업 및 공유 서비스 분야에서 수요가 나타나고 있습니다.
유럽은 기술 기반 조직을 위한 기술 시장에서 큰 기회가 있는 반면, 규정 준수 부담이 비교적 큰 지역입니다. EU AI법에 따라 고용 관련 AI는 더욱 엄격한 거버넌스 체계에 임베디드되어 조달 주기가 장기화되는 한편, 관리 조치를 명확하게 문서화할 수 있는 공급업체가 우대받고 있습니다. 프랑스와 독일은 대규모 통신 및 산업계 기업들이 기술 데이터를 체계적으로 정비하고 있다는 점을 배경으로, 여전히 가장 큰 기업 수요 원천으로 자리 잡고 있습니다. 영국도 도입 추세를 유지하고 있으며, 스킬스 잉글랜드(Skills England)의 『2026년 연례 기술 보고서』는 경제 전반에 걸친 주요 역량 격차를 해소하기 위해 구조화된 기술 데이터의 중요성을 강조하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 27.17%를 나타낼 것으로 예측되며, 기술 기반 조직 기술 시장에서 가장 빠르게 성장하고 가장 강력한 성장 영역이 될 전망입니다. 싱가포르, 인도, 한국이 주요 수요 견인 역할을 하고 있습니다. 이는 디지털 기술 프레임워크, 성숙해 가는 HR 기술 생태계, 그리고 산업의 고도화가 감사 가능한 역량 데이터의 활용 사례를 더욱 공고히 하고 있기 때문입니다. 남미에서는 시장 발전 속도가 비교적 완만하지만, 고용주들의 관심은 채용 자동화에서 기술 주도형 역량 개발로 점차 이동하고 있습니다. 중동에서는 도입이 아직 초기 단계이지만, 사우디아라비아와 아랍에미리트(UAE)의 자본 지원을 받는 프로그램들이 국가 차원의 노동력 현대화 계획과 연계되어 의미 있는 기업 수요를 창출하고 있습니다. 아프리카는 아직 발전의 초기 단계에 있지만, 금융 서비스 및 통신 분야에서 남아프리카공화국과 케냐가 가장 두드러진 활동의 중심지가 되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the skills-based organization technology market size was valued at USD 7.93 billion in 2025 and estimated to grow from USD 9.46 billion in 2026 to reach USD 22.85 billion by 2031, at a CAGR of 19.29% during the forecast period (2026-2031).
This report is Segmented by Component (Platforms, and Services), Deployment Model (Cloud, On-Premises, and Hybrid), Enterprise Size (Large Enterprises, Small and Medium-Sized Enterprises), Application (Internal Talent Mobility, and More), End-User Industry Vertical (IT and Telecommunications, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Skills-Based Organization Technology Market Trends and Insights
Shift from Job-Based to Skills-Based Operating Models
The move away from job-title-based workforce design remains the strongest driver for the skills-based organization technology market. Workday reported in April 2025 that only 32% of business leaders strongly believed their current workforce skills matched future needs, which keeps pressure on organizations to adopt systems that update capability data continuously.The same study found that 55% of organizations had already started the shift to a skills-based operating model, and another 23% planned to do so within 12 months, which shows how quickly this model is becoming standard practice. As companies begin to inventory skills rather than headcount alone, workforce planning becomes more continuous and less dependent on fixed requisition cycles. This changes procurement behavior because buyers increasingly want platforms that can support redeployment, learning, and planning from one skills layer. The skills-based organization technology market is therefore being shaped by a structural change in how enterprises define work itself.
AI-Enabled Skills Inference and Matching at Scale
AI-based inference has eased a longstanding data problem in the skills-based organization technology market, because self-reported and manager-reported skills data often lack depth and go stale quickly. Modern systems can infer capabilities from signals such as authored content, completed learning, and collaboration patterns, thereby improving coverage and update frequency. Gloat stated in March 2026 that its Loomra engine operates on a skills graph with 2.4 million skill nodes and 18.7 million skill relationships, showing how vendors are building large-scale inference infrastructure for real-time workforce use. Workday has also highlighted the engineering challenge of inferring relevant skills from minimal structured inputs, such as job titles, indicating that low-latency inference is becoming a core product capability rather than an add-on. Better inference matters commercially because it reveals skills that formal taxonomies had missed and makes internal mobility and planning more credible. This strengthens platform value over time, since each new employee action improves the data layer used across the business.
Employee Data Privacy and AI Governance Burden
Privacy and governance remain the most immediate restraints on the skills-based organization technology market. Skills inference systems often analyze passive work signals, such as authored content, project history, and collaboration activity, raising consent and transparency questions when those signals are reused for employment decisions. California's Civil Rights Council finalized automated decision-making system regulations in June 2025, effective October 2025, that require anti-bias testing, record retention, and broad oversight for covered tools. The EU AI Act has also raised scrutiny of employment-related AI systems, increasing documentation, review, and oversight requirements during procurement and deployment. These obligations tend to favor larger vendors that already have legal, engineering, and audit resources in place. They also slow spending recognition because buyers take longer to approve deployments and often widen project scope to include governance controls from the start.
Other drivers and restraints analyzed in the detailed report include:
- Internal Mobility and Retention Prioritization
- Agentic Workflow Demand for Machine-Readable Skills Graphs
- Integration Complexity Across HCM and Learning Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Platform software held 72.41% of the 2025 skills-based organization technology market share, which confirms that buyers still place the highest value on the core ontology, inference, and decisioning layer. That lead should remain intact because most downstream use cases, including mobility, learning, and planning, depend on a persistent skills graph that can be updated continuously. Within platform software, skills intelligence and ontology platforms form the base layer, while talent intelligence, internal mobility, and workforce planning modules build on top of that foundation. This sequencing matters because many enterprises enter the skills-based organization technology market with a core ontology project and then widen spend after the data layer starts to deliver usable signals.
Services are projected to expand at a CAGR of 22.67% from 2026 to 2031, which reflects the implementation effort required to deploy skills infrastructure across large and distributed workforces. Buyers need support with taxonomy design, change management, governance, and integration, and those needs do not end once the software goes live. Docebo's January 2026 acquisition of 365Talents showed that vendors increasingly want to connect skills identification directly to development actions inside broader learning systems. That move also suggests that services in the skills-based organization technology market will extend beyond setup work and into ongoing operating support. As agent-based capabilities spread, enterprises are also likely to spend more on managed governance, policy configuration, and workflow monitoring. This keeps services structurally important even though platform software remains the main revenue anchor.
Cloud accounted for 68.92% share of the skills-based organization technology market size in 2025, and it is also projected to be the fastest-growing deployment model at a CAGR of 23.83% through 2031. That combination is unusual in enterprise software and shows how strongly real-time inference, ontology updates, and multi-system integration favor cloud architecture. On-premises deployments still matter in regulated settings, but they are harder to maintain when skills data must be refreshed continuously and shared across multiple workflows. For many buyers, the skills-based organization technology market now looks less like a traditional HR software purchase and more like a data-layer decision that requires scale, speed, and update frequency.
Hybrid deployment remains strategically important because some large organizations still need tighter control over where employee data is processed and stored. This is especially relevant in Europe, where sovereign cloud preferences and local compliance obligations can shape platform design and vendor selection. Deutsche Telekom's rollout of its AI-powered Growth Hub across 2025 and 2026 illustrates how large enterprises are pairing global platform ambition with domestic governance requirements. That pattern suggests hybrid will not overtake cloud on volume, but it will hold a durable role in large regulated accounts. Vendors that can support both operational flexibility and local control are better positioned to win multinational programs. This also means deployment choice in the skills-based organization technology market is increasingly tied to governance maturity, not just IT preference.
Complete Report Scope:
- By Component
- Platforms
- Skills Intelligence and Ontology Platforms
- Talent Intelligence and Internal Mobility Platforms
- Workforce Planning and Analytics Platforms
- Services
- Platforms
- By Deployment Model
- Cloud
- On-Premises
- Hybrid
- By Enterprise Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Application
- Internal Talent Mobility and Marketplaces
- Skills-Based Recruitment and Talent Acquisition
- Skills-Driven Learning and Capability Development
- Workforce Planning and Scenario Intelligence
- Performance, Succession and Skills Mapping
- By End-User Industry Vertical
- IT and Telecommunications
- Healthcare and Life Sciences
- BFSI
- Manufacturing and Industrial Operations
- Retail and E-Commerce
- Education
- Government and Public Sector
- Energy and Utilities
- Media and Entertainment
- Other End-User Industry Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-pacific
- China
- Japan
- India
- Australia
- South Korea
- Singapore
- Rest of Asia-pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America held 41.64% of the skills-based organization technology market share in 2025, making it the largest regional revenue base. The United States remains the core demand center because it combines a dense population of digitally mature enterprises with a long history of investment in HCM and talent software. California's automated decision-making rules, effective from October 2025, have also increased the need for auditable, explainable workforce data in AI-supported employment decisions. Canada and Mexico remain smaller in scale, but Canada follows a similar enterprise adoption path while Mexico is showing demand in manufacturing and shared-services settings.
Europe is a high-opportunity but more compliance-heavy region for the skills-based organization technology market. The EU AI Act has pushed employment-related AI into a stricter governance framework, extending procurement cycles and favoring vendors that can clearly document controls. France and Germany remain the largest enterprise demand pools, supported by large telecom and industrial employers that are formalizing skills data at scale. The UK is also maintaining strong adoption momentum, and Skills England's Annual Skills Report 2026 underscored the importance of structured skills data for closing major competency gaps across the economy.
Asia-Pacific is projected to grow at a CAGR of 27.17% through 2031, making it the fastest-growing region and the strongest growth area for the skills-based organization technology market. Singapore, India, and South Korea are the main demand engines because digital-skills frameworks, maturing HR technology ecosystems, and industrial upgrading are creating stronger use cases for auditable competency data. South America is emerging more gradually, but employer interest is shifting from hiring automation toward skills-led capability development. The Middle East is still earlier in adoption, though capital-backed programs in Saudi Arabia and the United Arab Emirates are creating meaningful enterprise demand tied to national workforce modernization agendas. Africa remains nascent, with South Africa and Kenya as the clearest centers of activity in financial services and telecommunications.
- Eightfold AI Inc.
- Workday, Inc.
- SAP SE
- Oracle Corporation
- Cornerstone OnDemand, Inc.
- Gloat Ltd.
- Beamery Inc.
- Degreed, Inc.
- Fuel50 Limited
- Phenom People, Inc.
- TechWolf BV
- iMocha Inc.
- TalentGuard, Inc.
- Censia, Inc.
- Workera Corp.
- Textkernel B.V.
- 365Talents SAS
- Neobrain SAS
- Reejig Pty Ltd.
- ProFinda Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Shift From Job-Based to Skills-Based Operating Models
- 4.3.2 Internal Mobility and Retention Prioritization
- 4.3.3 AI-Enabled Skills Inference and Matching at Scale
- 4.3.4 Regulatory Pressure for Auditable Workforce Data
- 4.3.5 Agentic Workflow Demand for Machine-Readable Skills Graphs
- 4.3.6 Verifiable Credentials and Skills Portability
- 4.4 Market Restraints
- 4.4.1 Employee Data Privacy and AI Governance Burden
- 4.4.2 Integration Complexity Across HCM and Learning Systems
- 4.4.3 Taxonomy Drift From Rapidly Evolving Hybrid Roles
- 4.4.4 Suite Vendor Bundling Compressing Standalone Pricing Power
- 4.5 Industry Value-Chain Analysis
- 4.6 Supply Chain Analysis
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
- 4.10 Pricing Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Component
- 5.1.1 Platforms
- 5.1.1.1 Skills Intelligence and Ontology Platforms
- 5.1.1.2 Talent Intelligence and Internal Mobility Platforms
- 5.1.1.3 Workforce Planning and Analytics Platforms
- 5.1.2 Services
- 5.1.1 Platforms
- 5.2 By Deployment Model
- 5.2.1 Cloud
- 5.2.2 On-Premises
- 5.2.3 Hybrid
- 5.3 By Enterprise Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-Sized Enterprises
- 5.4 By Application
- 5.4.1 Internal Talent Mobility and Marketplaces
- 5.4.2 Skills-Based Recruitment and Talent Acquisition
- 5.4.3 Skills-Driven Learning and Capability Development
- 5.4.4 Workforce Planning and Scenario Intelligence
- 5.4.5 Performance, Succession and Skills Mapping
- 5.5 By End-User Industry Vertical
- 5.5.1 IT and Telecommunications
- 5.5.2 Healthcare and Life Sciences
- 5.5.3 BFSI
- 5.5.4 Manufacturing and Industrial Operations
- 5.5.5 Retail and E-Commerce
- 5.5.6 Education
- 5.5.7 Government and Public Sector
- 5.5.8 Energy and Utilities
- 5.5.9 Media and Entertainment
- 5.5.10 Other End-User Industry Verticals
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 Australia
- 5.6.4.5 South Korea
- 5.6.4.6 Singapore
- 5.6.4.7 Rest of Asia-pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Nigeria
- 5.6.6.4 Kenya
- 5.6.6.5 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Eightfold AI Inc.
- 6.4.2 Workday, Inc.
- 6.4.3 SAP SE
- 6.4.4 Oracle Corporation
- 6.4.5 Cornerstone OnDemand, Inc.
- 6.4.6 Gloat Ltd.
- 6.4.7 Beamery Inc.
- 6.4.8 Degreed, Inc.
- 6.4.9 Fuel50 Limited
- 6.4.10 Phenom People, Inc.
- 6.4.11 TechWolf BV
- 6.4.12 iMocha Inc.
- 6.4.13 TalentGuard, Inc.
- 6.4.14 Censia, Inc.
- 6.4.15 Workera Corp.
- 6.4.16 Textkernel B.V.
- 6.4.17 365Talents SAS
- 6.4.18 Neobrain SAS
- 6.4.19 Reejig Pty Ltd.
- 6.4.20 ProFinda Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment