|
시장보고서
상품코드
2119289
선택적 촉매 환원(SCR) 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Selective Catalytic Reduction System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 선택적 촉매 환원(SCR) 시스템 시장 규모는 2025년에 52억 3,000만 달러로 평가되었습니다. 예측 기간(2026-2031년) CAGR 6.13%로 확대되어 2026년 55억 4,000만 달러에서 2031년에는 74억 5,000만 달러에 이를 전망입니다.
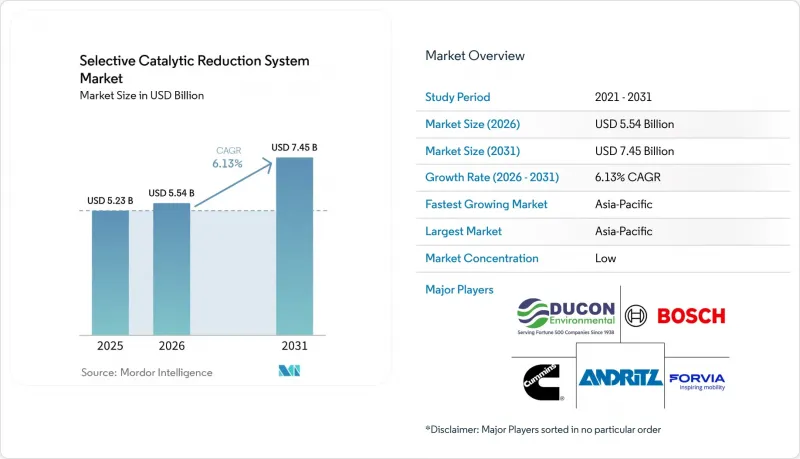
본 보고서는 촉매 유형(바나듐계 촉매, 제올라이트계 촉매 등), 설치 유형(신규 설치, 개조 설치 등), 최종 사용자 산업(자동차, 선박 등) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 선택적 촉매 환원(SCR) 시스템 시장 동향 및 인사이트
고정 배출원 및 이동 배출원에 대한 NOx 배출 기준 강화
2026년에는 고정 배출원 및 이동 배출원에 대한 규제 요건이 강화되면서, 규제 준수에 있어 선택적 촉매 환원(SCR) 시스템 시장의 역할이 확대되었습니다. 미국 환경보호청(EPA)은 2026년 1월 9일, 신규 배출원 성능 기준(NSPS) 개정을 최종 확정하고, 8억 5,000만 영국 열량 단위/시간(MMBtu/h) 이상이며 가동률이 45% 이상인 신규 대형 고가동률 천연가스 터빈에 대해 SCR을 배출 감축을 위한 최적의 시스템으로 지정했습니다. 이 규정에서는 2024년 12월 13일 이후 건설이 시작된 대상 설비에 대해 NOx 배출 기준을 5ppm으로 설정했습니다. 이에 따라 기존에는 연소 제어에 의존하던 가스터빈 프로젝트에도 연소 후처리가 도입되게 됩니다. 유로 7은 2026년 11월 이후 형식 인가를 받는 신규 경차에 적용되며, 디젤차의 NOx 배출 상한치를 80mg/km에서 30mg/km로 낮추는 한편, 더 낮은 온도와 낮은 부하 조건에서의 시험 범위를 확대합니다. 이러한 조건은 기존 바나듐계 배합에서 인용되던 250°C라는 임계값과 비교하여, 150-180°C 범위에서 활성을 유지하는 Cu 제올라이트 촉매의 채택을 뒷받침하는 것입니다. EPA의 2026년 7월 초안에서는 2027년형(MY2027) 이후 엔진에 대해 기존 대형차용 NOx 감축 목표의 90%가 유지되며, 상용차용 SCR 시스템의 필요성이 계속해서 요구되고 있습니다.
선박용 Tier III 규제 준수 및 SCR 사후 장착 수요
선박 규제로 인해 개조 수요가 지속적으로 발생하고 있습니다. 이는 외항선이 25-30년 동안 계속 운항되는 경우가 많기 때문입니다. 2025년 4월 11일에 채택된 IMO 결의안 MEPC.399(83)은 2026년 5월 1일에 발효되어, 대상 선박에 대한 SCR 관련 지침 및 NOx 측정 요건을 개정했습니다. 이 새로운 체계에서는 명시적인 ±5%의 정확도 요건 대신, 촉매 상태 모니터링에서 충분한 정확도를 갖춘 성능 기반의 실증 방식이 채택되었습니다. 2026년 3월 노르웨이 해역 및 캐나다 북극해가 NOx 배출 규제 해역으로 지정됨에 따라, 기존에는 후처리가 필요하지 않았던 항로에도 Tier III 요건이 적용되게 되었습니다. 이러한 요건은 저속 엔진의 배출량을 3.4 g/kWh로 제한하는 것으로, 영향을 받는 운항 사업자의 계획 기간을 단축하게 됩니다. 또한, 선택적 촉매 환원(SCR) 시스템 시장에서도 ISO 18611-1을 준수하는 AUS 40공급 및 저장 인프라가 북극권 및 아북극권의 각 항만에 고르게 구축되어 있지 않아 운영상의 제약에 직면하고 있습니다. MEPC 83에서 채택되어 2027년 3월 1일에 발효될 것으로 예상되는 ‘NOx 기술 코드 2008’의 개정에 따라, 2028년 1월 이후 대대적인 개조를 실시하는 선박에 대한 SCR 사후 장착 인증 요건이 갱신됩니다.
높은 자본 비용, 개조 비용 및 수명 주기 운영 비용
당국의 규정 준수 단속이 일관되지 않거나 설치 비용보다 낮은 벌금이 부과되는 지역에서는 자본 요건이 여전히 중요한 고려 사항입니다. 600MW 석탄 화력 발전 설비를 전면 개조하는 경우, 일반적으로 1,500만-2,500만 달러의 비용이 소요됩니다(가동 중단 기간, 암모니아 저장, 촉매 관리 비용 제외). 이 비용은 규제된 요금 마진이 좁은 범위에서 운영되는 남아시아 및 동남아시아의 전력 회사에 영향을 미칩니다. 분진 농도가 높고 유황 함량이 많은 석탄 환경에서는 300°C 미만에서 발생하는 중황산암모늄에 의한 오염으로 인해, 일반적으로 예상되는 5년이 아닌 3년마다 촉매를 교체해야 할 수도 있습니다. 규제 집행이 미흡한 지역에서는 소규모 시멘트, 철강, 화학 기업의 경우, 설비 보유 비용이 규제 위반에 따른 벌금보다 더 높아질 수 있습니다. 정밀한 투여 제어를 통해 시약 사용량을 줄일 수는 있지만, 선택적 촉매 환원(SCR) 시스템 시장의 주요 설비 투자 요건을 배제하는 것은 아닙니다.
부문 분석
2025년 기준, 바나듐계 촉매는 촉매 유형별 선택적 촉매 환원(SCR) 시스템 시장에서 50.18%의 점유율을 차지했습니다. 이러한 위상은 아시아 및 북미 전역의 분진량이 많은 석탄 화력 발전소에서 수년에 걸쳐 도입되어 온 실적을 반영한 것입니다. 이러한 시스템은 SO₂ 노출 및 가혹한 배기가스 조건도 견딜 수 있습니다. 확립된 도입 실적이 전력 사업 분야의 교체 수요를 뒷받침하고 있습니다. 조달 결정 시 기계적 내구성과 검증된 현장 성능이 우선시되는 경우, 바나듐계 촉매는 여전히 중요한 역할을 하고 있습니다. 따라서 선택적 촉매 환원(SCR) 시스템 시장에서는 많은 대규모 고정 설비에서 계속해서 바나듐계 시스템이 채택되고 있습니다.
제올라이트계 촉매는 2031년까지 연평균 성장률(CAGR) 6.71%를 나타낼 것으로 예측됩니다. Cu-SSZ-13 및 Fe-제올라이트 배합은 200°C 미만의 온도에서 더 높은 질소산화물(NOx) 전환율을 달성하여 유로 7의 콜드 스타트 요건 및 배기 온도가 변동하는 용도에 대응하고 있습니다. 중국 장쑤성에서 Cu-제올라이트 생산은 자동차 및 비도로용 기기를 위한 OEM 및 애프터마켓 채널로 확대되고 있습니다. 귀금속 촉매는 요소 인프라가 없는 수소 엔진용 수동형 선택적 촉매 환원(SCR) 설계 등 특수한 용도로 사용되고 있습니다. 구리계, 이산화티타늄, 혼합 금속 배합 등 기타 재료들도 특정 공정 요건을 충족하고 있습니다. 바나듐 오산화물의 가격 동향과 Cu-제올라이트의 워시코트용 희토류 전구체에 대한 중국의 규제는 명확한 공급 리스크를 초래하고 있으며, 각 OEM 기업들은 이중 조달 전략을 유지하도록 권장받고 있습니다.
지역별 분석
아시아태평양은 2025년에 선택적 촉매 환원(SCR) 시스템 시장 점유율의 37.15%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.84%를 나타낼 것으로 전망됩니다. 중국에서는 200 MW를 초과하는 석탄 화력 발전 설비를 대상으로 NOx 배출 상한을 50 mg/Nm³로 하는 확립된 SCR 기반이 구축되어 있습니다. 이 나라 수요는 설비 교체 주기, 중형 산업용 보일러, 그리고 시멘트, 유리, 철강 업계를 대상으로 한 배기가스 규제로 이동하고 있습니다. 인도에서는 중앙전력청(CEA)이 단계적으로 도입하고 있는 NOx 규제 하에 210 GW의 화력 발전 설비가 가동 중이며, 신규 설비에는 100 mg/Nm³의 배출 상한이 설정되어 있습니다. 이에 따라 인도에서는 대규모 석탄 화력 발전 설비 전반에 걸쳐 초기 도입 시 개보수가 추진되고 있습니다. 일본과 한국에서는 산업용 보일러의 규제 요건을 충족하기 위해 고성능 및 고활성 촉매의 도입이 추진되고 있습니다.
북미 및 유럽은 규제 시행에 따라 선택적 촉매 환원(SCR) 시스템 시장에서 여전히 주요 지역으로 자리 잡고 있습니다. 미국에서는 2026년 1월 ‘신규 배출원 성능 기준(NSPS)’ 개정에 따라, 대상인 가동률이 높은 천연가스 터빈에 SCR 도입이 의무화되었습니다. 또한 노후화된 가스 터빈의 경우, 수명 중반에 이르는 개조 시기에 사후 장착 기회가 생기고 있습니다. 유럽에서는 전동화로 인해 소형 차량 수요가 점차 감소하고 있음에도 불구하고, 유로 7을 통해 자동차용 SCR에 대한 지원이 계속되고 있습니다. 고정 설비 수요는 시멘트, 철강, 화학 플랜트의 ‘최적 이용 기술(BAT)’ 사이클에서 발생하고 있습니다. 북유럽 시장에서는 2026년 3월 노르웨이 해역 NOx 배출 규제 구역(NECA)의 발효로 인해 선박 분야 수요가 더욱 확대되었습니다.
남미, 중동 및 아프리카에서는 각각 다른 수요 상황이 나타나고 있습니다. 브라질에서는 대형 차량의 배기가스 기준과 상파울루 및 리우데자네이루의 산업 활동을 통해 자동차 및 석유화학 분야의 SCR 적용이 지원되고 있습니다. 아르헨티나 및 기타 남미 국가에서는 환율 변동과 시약 수입 비용이 소규모 사업자들의 발목을 잡고 있습니다. 사우디아라비아에서는 산업의 다각화와 가스 화력 발전 용량 확충으로 인해 가스 터빈용 SCR 시스템을 둘러싼 경쟁이 촉진되고 있습니다. 지멘스 에너지는 2025년, 오만의 미스파 및 두쿰에 위치한 독립 발전 프로젝트를 위해 SGT5-4000F 터빈 6기를 수주했습니다. 남아프리카공화국에서는 노후화된 석탄 화력 발전 설비와 강화된 환경 규제로 인해 산업용 SCR의 조기 도입 기회가 생겨나고 있습니다. 그러나 해당 국가의 재생에너지 전환으로 인해 장기적인 화력 발전 기반이 제한될 가능성이 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the selective catalytic reduction system market size was estimated at USD 5.23 billion in 2025 and is estimated to grow from USD 5.54 billion in 2026 to USD 7.45 billion by 2031, at a CAGR of 6.13% during the forecast period (2026-2031).
This report is Segmented by Catalyst Type (Vanadium-Based Catalysts, Zeolite-Based Catalysts, and More), Installation Type (New Installations, Retrofit Installations, and More), End-User Industry (Automotive, Marine, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Selective Catalytic Reduction System Market Trends and Insights
Tightening NOx Emission Standards for Stationary and Mobile Sources
Regulatory requirements for stationary and mobile sources increased in 2026, expanding the role of the selective catalytic reduction (SCR) system market in compliance. The US Environmental Protection Agency finalized amendments to the New Source Performance Standards (NSPS) on January 9, 2026, identifying SCR as the best system of emission reduction for new large, high-utilization natural gas turbines above 850 million British thermal units per hour (MMBtu/h) and a 45% capacity factor. The rule set a 5-ppm NOx standard for covered units that began construction after December 13, 2024, bringing post-combustion treatment into gas turbine projects that previously relied on combustion controls. Euro 7 will apply to new light-duty type approvals from November 2026 and lower diesel NOx limits from 80 mg/km to 30 mg/km while extending testing to colder and lower-load conditions. These conditions support Cu-zeolite catalysts that remain active at 150-180°C, compared with the 250°C threshold cited for conventional vanadium formulations. The EPA's July 2026 draft proposal retained 90% of prior heavy-duty NOx reductions for Model Year 2027 (MY2027) and later engines, maintaining the need for commercial-vehicle SCR systems.
Marine Tier III Compliance and SCR Retrofit Demand
Marine regulations create a retrofit pipeline because ocean-going vessels often remain in operation for 25-30 years. IMO Resolution MEPC.399(83), adopted on April 11, 2025, entered into force on May 1, 2026, and updated SCR guidance and NOx measurement requirements for relevant vessels. The new framework uses a performance-based demonstration of sufficient accuracy for catalyst-condition monitoring rather than an explicit +-5% accuracy requirement. The March 2026 activation of the Norwegian Sea and Canadian Arctic as NOx Emission Control Areas applied Tier III requirements to routes that previously did not require aftertreatment. These requirements limit emissions from slow-speed engines to 3.4 g/kWh and shorten the planning window for affected operators. The selective catalytic reduction system market also faces an operational constraint, as ISO 18611-1-compliant AUS 40 supply and storage infrastructure has not scaled evenly across Arctic and sub-Arctic ports. Amendments to the NOx Technical Code 2008, adopted at MEPC 83 and expected to enter into force on March 1, 2027, will update SCR retrofit certification for vessels undergoing substantial modification from January 2028.
High Capital, Retrofit, and Lifecycle Operating Costs
Capital requirements remain a key consideration in regions where authorities enforce compliance inconsistently or impose penalties below installation costs. A full-scale retrofit of a 600 MW coal unit typically costs USD 15-25 million, excluding downtime, ammonia storage, and catalyst management. This cost affects utilities in South Asia and Southeast Asia that operate with narrow regulated tariff margins. In high-dust and high-sulfur coal environments, ammonium bisulfate fouling below 300°C can require catalyst replacement after 3 years instead of the usual 5-year assumption. Smaller cement, steel, and chemical companies may find that ownership costs exceed noncompliance penalties in areas with weak enforcement. Advanced dosing controls can reduce reagent use, but they do not eliminate the primary capital requirement for the Selective Catalytic Reduction System market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of High-NOx Industrial and Power Assets in Asia-Pacific
- Low-Temperature Catalyst Deployment, Digital Ammonia-Dosing, and Hydrogen Engine Validation
- Catalyst Poisoning, Electrification, and Reagent Availability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vanadium-based catalysts held 50.18% of the catalyst-type Selective Catalytic Reduction System market share in 2025. This position reflected their long-standing deployment in high-dust coal-fired power plants across Asia and North America. These systems tolerate SO2 exposure and demanding flue-gas conditions. Their established installed base supports replacement demand in utility applications. Vanadium remains relevant where procurement decisions prioritize mechanical durability and proven field performance. Therefore, the Selective Catalytic Reduction System market continues to rely on vanadium systems for many large stationary installations.
Zeolite-based catalysts are forecast to grow at a CAGR of 6.71% through 2031. Cu-SSZ-13 and Fe-zeolite formulations achieve higher nitrogen oxide (NOx) conversions below 200°C, supporting Euro 7 cold-start requirements and applications with variable exhaust temperatures. Cu-zeolite production in Jiangsu, China, has expanded across OEM and aftermarket channels for automotive and non-road equipment. Precious-metal catalysts are used in specialized applications, including passive Selective Catalytic Reduction (SCR) designs for hydrogen engines without urea infrastructure. Other materials, including copper-based, titanium dioxide, and mixed-metal formulations, address specific process requirements. Vanadium pentoxide pricing and China's control over rare-earth precursors for Cu-zeolite washcoats pose distinct supply risks, encouraging OEMs to maintain dual-sourcing strategies.
Complete Report Scope:
- By Catalyst Type
- Vanadium-Based Catalysts
- Zeolite-Based Catalysts
- Precious Metal Catalysts
- Others (Copper-Based, Titanium Dioxide, Mixed Metal Catalysts)
- By Installation Type
- New Installations
- Retrofit Installations
- Others (Catalyst Replacement and Regeneration)
- By End-User Industry
- Power Generation
- Automotive
- Marine
- Chemicals and Petrochemicals
- Industrial Manufacturing (Cement, Steel, Boilers, Others)
- Others (Waste Incineration, Oil and Gas, Mining, Rail)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 37.15% of the Selective Catalytic Reduction System market share in 2025 and is forecast to register a CAGR of 6.84% through 2031. China has an established SCR base for coal-fired capacity above 200 MW, with a 50 mg/Nm3 NOx ceiling. Demand in the country is shifting toward replacement cycles, mid-size industrial boilers, and emissions controls for cement, glass, and steel. India operates a 210 GW thermal fleet under phased Central Electricity Authority NOx requirements, including a 100 mg/Nm3 limit for new units. Therefore, India supports first-install retrofits across a large coal fleet. Japan and South Korea support adopting premium, high-activity catalysts to meet industrial boiler requirements.
North America and Europe remain key regions in the Selective Catalytic Reduction System market due to regulatory enforcement. The United States requires SCR for covered high-utilization natural gas turbines under the January 2026 New Source Performance Standards (NSPS) amendments. Aging gas turbines also create retrofit opportunities during mid-life renovations. Europe continues to support automotive SCR through Euro 7, even as electrification gradually reduces demand from the light-duty fleet. Stationary demand comes from best-available-technique cycles for cement, steel, and chemical facilities. Nordic markets gained additional marine demand from the activation of the Norwegian Sea NOx Emission Control Area (NECA) in March 2026.
South America, the Middle-East, and Africa have distinct demand conditions. Brazil supports automotive and petrochemical SCR applications through heavy-vehicle standards and industrial activity in Sao Paulo and Rio de Janeiro. Currency volatility and reagent import costs constrain smaller operators in Argentina and the rest of South America. Saudi Arabia's industrial diversification and additions to gas-fired power capacity support competition for gas-turbine SCR systems. Siemens Energy secured six SGT5-4000F turbine contracts for Oman's Misfah and Duqm independent power projects in 2025. South Africa's aging coal fleet and environmental enforcement create an early opportunity for industrial SCR. However, the country's renewable energy transition may limit the long-term thermal power base.
- ANDRITZ
- Babcock & Wilcox Enterprises, Inc.
- Cummins Inc.
- Ducon Environmental Systems Inc.
- Durr CTS
- FORVIA
- GE Vernova
- Kautex Textron GmbH & Co. KG
- MITSUBISHI HEAVY INDUSTRIES, LTD.
- Robert Bosch GmbH
- Shandong Longking Environmental Protection Co., Ltd.
- Siemens Energy
- Sud-Chemie India Pvt. Ltd.
- Tenneco Inc.
- YANMAR Marine International
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening NOx Emission Standards for Stationary and Mobile Sources
- 4.2.2 Marine Tier III Compliance and SCR Retrofit Demand
- 4.2.3 Expansion of High-NOx Industrial and Power Assets in Asia-Pacific
- 4.2.4 Low-Temperature Catalyst Deployment in Cement and Biomass Applications
- 4.2.5 Digital Ammonia-Dosing and Closed-Loop Emissions Control
- 4.2.6 SCR Validation for Hydrogen-Fueled Internal-Combustion Engines
- 4.3 Market Restraints
- 4.3.1 High Capital, Retrofit, and Lifecycle Operating Costs
- 4.3.2 Catalyst Poisoning, Fouling, and Shortened Service Life
- 4.3.3 Light-Duty Electrification Reducing the Addressable Diesel Base
- 4.3.4 Reagent Availability, Storage, and Maritime Bunkering Uncertainty
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Catalyst Type
- 5.1.1 Vanadium-Based Catalysts
- 5.1.2 Zeolite-Based Catalysts
- 5.1.3 Precious Metal Catalysts
- 5.1.4 Others (Copper-Based, Titanium Dioxide, Mixed Metal Catalysts)
- 5.2 By Installation Type
- 5.2.1 New Installations
- 5.2.2 Retrofit Installations
- 5.2.3 Others (Catalyst Replacement and Regeneration)
- 5.3 By End-User Industry
- 5.3.1 Power Generation
- 5.3.2 Automotive
- 5.3.3 Marine
- 5.3.4 Chemicals and Petrochemicals
- 5.3.5 Industrial Manufacturing (Cement, Steel, Boilers, Others)
- 5.3.6 Others (Waste Incineration, Oil and Gas, Mining, Rail)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ANDRITZ
- 6.4.2 Babcock & Wilcox Enterprises, Inc.
- 6.4.3 Cummins Inc.
- 6.4.4 Ducon Environmental Systems Inc.
- 6.4.5 Durr CTS
- 6.4.6 FORVIA
- 6.4.7 GE Vernova
- 6.4.8 Kautex Textron GmbH & Co. KG
- 6.4.9 MITSUBISHI HEAVY INDUSTRIES, LTD.
- 6.4.10 Robert Bosch GmbH
- 6.4.11 Shandong Longking Environmental Protection Co., Ltd.
- 6.4.12 Siemens Energy
- 6.4.13 Sud-Chemie India Pvt. Ltd.
- 6.4.14 Tenneco Inc.
- 6.4.15 YANMAR Marine International
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment