|
시장보고서
상품코드
2119318
PFAS 흡착제 재생용 화학물질 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)PFAS Adsorbent Regeneration Chemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
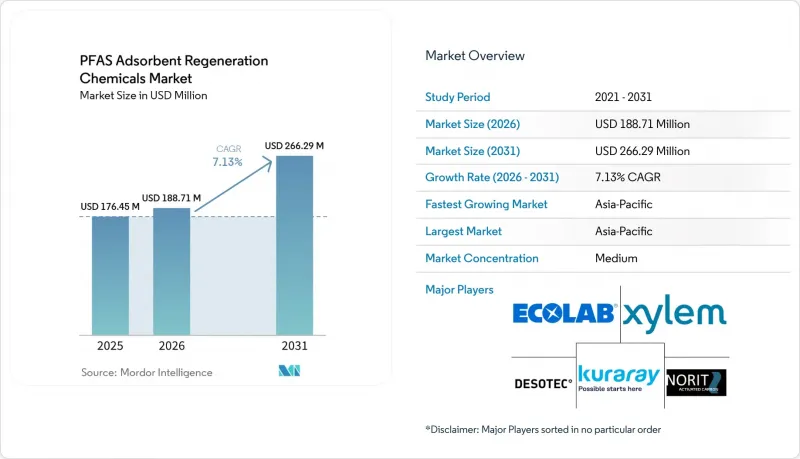
에 의하면, PFAS 흡착제 재생용 화학물질 시장은 2025년에 1억 7,645만 달러 규모로 평가되었습니다. 2026년 1억 8,871만 달러에서 2031년까지 2억 6,629만 달러에 이를 것으로 예측됩니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 7.13%를 나타낼 것으로 전망됩니다.
본 보고서는 화학 물질 유형(수산화나트륨, 알코올계 화학 물질 등), 흡착제 유형(과립형 활성탄 등), 최종 이용 산업(도시 용수 처리, 공업용수 처리 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 PFAS 흡착제 재생용 화학물질 시장 동향 및 인사이트
규제를 배경으로 한 ‘포집 및 파괴(Capture-and-Destroy)’ 처리 방식의 도입
미국 환경보호청(EPA)은 2024년 4월 ‘국가 1차 음용수 규정(NPDR)’을 최종 확정하고, 퍼플루오로옥탄산 및 퍼플루오로옥탄설폰산의 최대 오염 물질 농도를 4 parts per trillion으로 설정했습니다. 또한, 이 규정에서는 일반적으로 GenX 화학물질로 불리는 퍼플루오로헥산설폰산, 퍼플루오로노난산 및 헥사플루오로프로파일렌옥사이드 이량체산에 대해서도 10조분의 1이라는 상한치가 설정되었습니다. 이러한 규제로 인해 상수도 유틸리티자는 사용 후 입상 활성탄을 단순한 폐기물로 취급하지 않고, 재생 및 파괴 방법을 모색하도록 권장받고 있습니다. 이는 화학 물질 사용을 문서화된 처리 및 폐기물 관리 요건과 연계함으로써 PFAS 흡착제 재생용 화학 물질 시장을 뒷받침하고 있습니다. PFOS 및 PFOA에 대한 리터당 50나노그램이라는 일본의 강제 기준은 2026년 4월에 시행되었으며, 수도 유틸리티자에게 검사, 조사 및 결과 공개가 의무화되었습니다. 유럽의 계획 또한 화학물질의 등록, 평가, 허가 및 제한(REACH) 체계에 기반한 종합적인 규제안의 영향을 받고 있으며, 이에 대한 과학적 평가는 2026년 말까지 완료될 전망입니다.
단쇄 PFAS 처리에 대한 수요 증가
표준 입상 활성탄 여과는 소수성 상호 작용에 크게 의존하지만, 이 방법은 탄소 수가 6 미만인 퍼플루오로알킬산에 대해서는 효과가 떨어집니다. 이온 교환 수지는 소수성 결합에 정전기적 상호 작용을 더하기 때문에 장쇄 화합물과 단쇄 화합물 모두의 제거 효율을 향상시킬 수 있습니다. 그 결과 발생하는 재생 공정에서는 메탄올·염수 또는 에탄올·염수의 혼합액이 자주 사용되며, 이로 인해 용도에 맞는 화학약품 투입 및 농축액 처리에 대한 수요가 발생하고 있습니다. 2025년에 발표된 조사에 따르면, 재생액 중 메탄올의 90% 이상을 50°C에서 4시간 이내에 로터리 증발기를 사용하여 회수할 수 있으며, 회수된 용매에서 PFAS의 검출 가능한 캐리오버는 확인되지 않았습니다. 수지 용도의 경우, 표준 가성 알칼리 사이클이 아닌 재료별로 고유한 재생 프로토콜이 필요하기 때문에 이러한 전환으로 인해 PFAS 흡착제 재생용 화학물질 시장은 혜택을 보고 있습니다.
PFAS를 함유한 재생액의 유해 물질 취급 요건
사용 후 재생액은 용매 기반 이온 교환 재생 또는 알칼리성 입상 활성탄의 탈착 과정에서 생성되는 PFAS를 포함하는 농축 액체입니다. 이를 관리하기 위해서는 추적 가능한 취급과 폐기물 처리 허가를 받은 시설로의 이송이 필요하며, 이로 인해 처리 업체의 운영 부담이 증가합니다. 또한, 용매 기반 폐기물 흐름에는 적절한 보관 및 안전 대책이 필요하며, 이로 인해 현장에서 재생 시스템에 대한 설비 투자 요건이 높아집니다. 중소규모의 유틸리티체에서는 유해 폐기물에 대한 전문 지식을 갖춘 인력이 부족하거나, 전용 처리 설비를 유지하기 위해 필요한 처리량을 확보하지 못하는 경우가 있습니다. 이러한 제약으로 인해 재생 처리의 수명 주기 비용이 낮은 경우에도, 분산된 각 거점은 일회용 매체에 의존할 수밖에 없는 상황이 발생합니다. 따라서 PFAS 흡착제 재생용 화학물질 시장은 집중형 인프라와 문서화된 폐기물 물류를 활용할 수 있는 대규모 사업자에게 여전히 진입하기 쉬운 상황입니다.
부문 분석
2025년, 수산화나트륨은 시장 매출의 41.86%를 차지했습니다. 이는 고pH 입상 활성탄의 재활성화 프로토콜이나 이온 교환 수지의 세척 주기에 사용됩니다. 알칼리성 조건은 전하를 띤 흡착제 표면에 결합된 PFAS의 결합력을 약화시켜 탈착을 촉진합니다. 메탄올이나 에탄올을 주성분으로 하는 알코올계 화학 약품은 용매를 이용한 이온 교환 수지의 재생 처리에 사용됩니다. 이러한 사용은 설치된 수지 용량 및 처리 후 용매를 회수·관리해야 할 필요성과 관련이 있습니다.
독자적으로 배합된 화학 약품 시장은 2031년까지 연평균 성장률(CAGR) 8.57%를 나타낼 것으로 예측됩니다. 이러한 화학 약품의 채택은 사이클로덱스트린 폴리머, 불소 수지 흡착제, 분자 임프린팅 재료 등 새로운 PFAS 선택성 재료와 관련이 있습니다. 이러한 소재에는 각각의 특정 흡착 거동에 맞추어 설계된 재생 프로토콜이 필요합니다. 2024년 『Nature Communications』지에 게재된 연구에 따르면, 적절한 탈착 화학 반응을 사용할 경우, 불소 수지 흡착제는 5회의 재생 주기를 거친 후에도 90% 이상의 PFAS 흡착 효율을 유지하는 것으로 밝혀졌습니다. PFAS 흡착제 재생용 화학물질 시장에서는 이러한 소재들이 파일럿 프로젝트 단계에서 본격적인 시스템으로 전환됨에 따라, 설계된 혼합물의 사용이 증가할 전망입니다.
지역별 분석
아시아태평양은 2025년에 시장 매출의 39.91%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.53%로 확대될 것으로 전망됩니다. 일본에서는 2026년 4월부터 리터당 50나노그램이라는 PFOS 및 PFOA 강제 기준이 시행되어, 상수도 유틸리티자에게 검사, 점검 및 정보 공개 요건이 부과되고 있습니다. 이에 따라 입상 활성탄의 재활성화 및 이온 교환 수지의 재생 프로그램에 대한 투자가 촉진되고 있습니다. 한국은 2025년 중반까지 PFOS, PFOA 및 퍼플루오로헥산설폰산에 대한 규제를 확대했습니다. 한편, 대만은 반도체 제조에 따른 PFAS 폐수 문제에 직면해 있으며, 싱가포르와 태국을 포함한 아세안(ASEAN) 국가들은 규제 도입 초기 단계에 있어 PFAS 흡착제 재생용 화학물질 시장 전망 수요원이 될 전망입니다.
북미는 2024년 음용수 규정에 대한 미국의 규제 대응과 처리 인프라에 대한 투자에 힘입어 성장하고 있습니다. 2026년 2월, 쿠라레의 자회사인 칼곤 카본 코퍼레이션은 오하이오주 콜럼버스에 위치한 공장에 약 1억 달러를 투자하여 연간 2,700만 파운드의 재생 능력을 추가할 것이라고 발표했습니다. 가동 시작은 2028년 1분기로 예정되어 있습니다. 이번 확장은 2031년 준수 기한에 앞서 국내 생산 능력을 확보하기 위한 것이며, 한편 애리조나주, 뉴욕주, 오하이오주에서의 반도체 제조 확대는 PFAS 흡착제 재생용 화학물질 시장에서 단쇄 PFAS 재생 화학물질에 대한 현장별 수요를 창출하고 있습니다.
유럽에서는 유럽연합(EU)의 규제가 지자체 및 산업 시설의 처리 계획에 영향을 미치고 있습니다. PFAS 함유 소화용 거품제에 대한 EU 규제는 2025년 10월에 공포되었으며, 퍼플루오로헥산산 관련 물질에 대한 규제는 2026년 10월에 발효됩니다. DESOTEC은 2023년에 Evoqua의 활성탄 재생 사업을 인수하고, 2025년에는 Sentinel Water Solutions와 제휴를 맺음으로써 미국 내 사업 기반을 확대했습니다. 남미, 중동 및 아프리카는 여전히 발전 초기 단계에 있는 지역이지만, 광업에 의한 오염 관리 및 지자체 투자를 통해 PFAS 흡착제 재생용 화학물질 시장에서 선택적인 비즈니스 기회가 창출되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the PFAS adsorbent regeneration chemicals market was valued at USD 176.45 million in 2025 and is estimated to grow from USD 188.71 million in 2026 to reach USD 266.29 million by 2031, at a CAGR of 7.13% during the forecast period (2026-2031).
This report is Segmented by Chemical Type (Sodium Hydroxide, Alcohol-Based Chemicals, and More), Adsorbent Type (Granular Activated Carbon, and More), End-Use Industry (Municipal Water Treatment, Industrial Water Treatment, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global PFAS Adsorbent Regeneration Chemicals Market Trends and Insights
Regulatory-Driven Adoption of Capture-and-Destroy Treatment
The United States Environmental Protection Agency finalized the National Primary Drinking Water Regulation in April 2024 and set maximum contaminant levels of 4 parts per trillion for perfluorooctanoic acid and perfluorooctane sulfonic acid. The rule also set limits of 10 parts per trillion for perfluorohexane sulfonic acid, perfluorononanoic acid, and hexafluoropropylene oxide dimer acid, commonly called GenX chemicals. These obligations have encouraged utilities to assess regeneration and destruction pathways rather than treat spent granular activated carbon as a disposal-only material. This supports the PFAS adsorbent regeneration chemicals market by tying chemical use to documented treatment and waste-management requirements. Japan's mandatory standards for PFOS and PFOA at 50 nanograms per liter became effective in April 2026 and require water suppliers to test, inspect, and disclose results. European planning is also affected by the proposed universal restriction under the Registration, Evaluation, Authorisation and Restriction of Chemicals framework, whose scientific evaluation is expected to conclude by the end of 2026.
Rising Demand for Short-Chain PFAS Treatment
Standard granular activated carbon filtration relies heavily on hydrophobic interactions, which are less effective for perfluoroalkyl acids with chain lengths below 6 carbons. Ion exchange resins add electrostatic interactions to hydrophobic binding and can therefore improve the removal of both long-chain and short-chain compounds. The resulting regeneration process often uses methanol-brine or ethanol-brine mixtures, which creates demand for tailored chemical inputs and handling of the concentrated stream. Research published in 2025 found that more than 90% of methanol in regenerant solutions could be recovered by rotary evaporation within 4 hours at 50 °C, without detectable PFAS carryover into the recovered solvent. The PFAS adsorbent regeneration chemicals market gains from this transition because resin applications require material-specific regeneration protocols rather than a standard caustic cycle.
Hazardous Handling Requirements for PFAS-Loaded Regenerants
Spent regenerants are concentrated PFAS-bearing liquids produced during solvent-based ion exchange regeneration or alkaline granular activated carbon desorption. Their management requires traceable handling and transfer to facilities permitted to process the waste, which increases the operating burden on treatment providers. Solvent-based waste streams also require appropriate storage and safety controls, raising the capital requirement for on-site regeneration systems. Small and medium utilities may lack staff with hazardous waste expertise or the processing volumes needed to support dedicated handling equipment. These limitations can keep distributed sites reliant on single-use media even when regeneration has lower lifecycle costs. The PFAS adsorbent regeneration chemicals market, therefore, remains more accessible to large operators that can use centralized infrastructure and documented waste logistics.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Centralized Regeneration Services
- Increasing Cost of Spent Adsorbent Disposal
- Uncertainty Regarding PFAS Destruction Byproducts
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sodium hydroxide held 41.86% of the market revenue in 2025. It is used in high-pH granular activated carbon reactivation protocols and during cleaning cycles for ion exchange resins. Alkaline conditions can weaken PFAS binding on charged adsorbent surfaces and support desorption. Alcohol-based chemicals, mainly methanol and ethanol, are used in solvent-based ion exchange regeneration. Their use is tied to installed resin capacity and the need to recover or manage the solvent after treatment.
Proprietary chemical blends are forecast to grow at an 8.57% CAGR through 2031. Their adoption is linked to newer PFAS-selective materials, including cyclodextrin polymers, fluoropolymer sorbents, and molecularly imprinted materials. These materials need regeneration protocols designed for their specific adsorption behavior. A 2024 Nature Communications study found that a fluoropolymer sorbent retained more than 90% PFAS sorption efficiency after 5 regeneration cycles when the appropriate desorption chemistry was used. The PFAS adsorbent regeneration chemicals market is likely to use more engineered blends as these materials progress from pilot projects to full-scale systems.
Complete Report Scope:
- By Chemical Type
- Sodium Hydroxide
- Alcohol-Based Chemicals
- Proprietary Chemical Blends
- Other Chemical Types (Acetone, Salt Solutions, Surfactant-Based Chemicals)
- By Adsorbent Type
- Granular Activated Carbon
- Ion Exchange Resins
- Powdered Activated Carbon
- Other Adsorbent Types (Modified Clay, Bio-Based and Hybrid Adsorbents)
- By End-Use Industry
- Municipal Water Treatment
- Industrial Water Treatment
- Semiconductor Manufacturing
- Other End-Use Industries (Landfill Leachate Treatment, Defense and Aerospace, Mining and Metals, Chemicals and Petrochemicals)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 39.91% of the market revenue in 2025 and is forecast to expand at an 8.53% CAGR through 2031. Japan's mandatory PFOS and PFOA standards at 50 nanograms per liter became effective in April 2026 and apply to water supply operators through testing, inspection, and disclosure requirements. This supports investment in granular activated carbon reactivation and ion exchange regeneration programs. South Korea extended restrictions on PFOS, PFOA, and perfluorohexane sulfonic acid by mid-2025, while Taiwan faces PFAS wastewater concerns associated with semiconductor operations, and ASEAN countries, including Singapore and Thailand, are at earlier regulatory stages that provide a future pipeline for the PFAS adsorbent regeneration chemicals market.
The North America region is anchored by the U.S. regulatory response to the 2024 drinking water rule and by investment in treatment infrastructure. In February 2026, Calgon Carbon Corporation, a subsidiary of KURARAY CO., LTD., announced a nearly USD 100 million investment in its Columbus, Ohio, plant to add 27 million pounds per year of reactivation capacity, with operations expected to begin in the first quarter of 2028. The expansion is intended to position domestic capacity before the 2031 compliance deadline, while semiconductor fabrication growth in Arizona, New York, and Ohio adds site-specific demand for short-chain PFAS regeneration chemistry in the PFAS adsorbent regeneration chemicals market.
In Europe, the European Union restriction is affecting treatment planning across municipal and industrial sites. The European Union restriction on PFAS-containing firefighting foams was published in October 2025, and the restriction on perfluorohexanoic acid-related substances takes effect in October 2026. DESOTEC expanded its U.S. position through the 2023 acquisition of Evoqua's carbon reactivation business and a 2025 partnership with Sentinel Water Solutions. South America, and Middle-East and Africa remain earlier-stage areas where mining contamination management and municipal investment create selective opportunities for the PFAS adsorbent regeneration chemicals market.
- DESOTEC
- DuPont
- Ecolab Inc.
- Envirogen Group
- JACOBI CARBONS GROUP
- KURARAY CO., LTD.
- Kurita Water Industries Ltd.
- LANXESS
- Norit
- Onterris, Inc.
- Puraffinity
- Puragen
- ResinTech, Inc.
- Xylem
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory-Driven Adoption of Capture-and-Destroy Treatment
- 4.2.2 Expansion of Centralized Regeneration Services
- 4.2.3 Rising Demand for Short-Chain PFAS Treatment
- 4.2.4 Increasing Cost of Spent Adsorbent Disposal
- 4.2.5 Regenerant Recycling and Closed-Loop Solvent Recovery
- 4.2.6 Modular Regeneration Systems for Distributed Treatment Sites
- 4.3 Market Restraints
- 4.3.1 Hazardous Handling Requirements for PFAS-Loaded Regenerants
- 4.3.2 Limited Availability of Specialized Reactivation Capacity
- 4.3.3 Uncertainty Regarding PFAS Destruction Byproducts
- 4.3.4 High Chemical Recovery and Wastewater Treatment Requirements
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Chemical Type
- 5.1.1 Sodium Hydroxide
- 5.1.2 Alcohol-Based Chemicals
- 5.1.3 Proprietary Chemical Blends
- 5.1.4 Other Chemical Types (Acetone, Salt Solutions, Surfactant-Based Chemicals)
- 5.2 By Adsorbent Type
- 5.2.1 Granular Activated Carbon
- 5.2.2 Ion Exchange Resins
- 5.2.3 Powdered Activated Carbon
- 5.2.4 Other Adsorbent Types (Modified Clay, Bio-Based and Hybrid Adsorbents)
- 5.3 By End-Use Industry
- 5.3.1 Municipal Water Treatment
- 5.3.2 Industrial Water Treatment
- 5.3.3 Semiconductor Manufacturing
- 5.3.4 Other End-Use Industries (Landfill Leachate Treatment, Defense and Aerospace, Mining and Metals, Chemicals and Petrochemicals)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 DESOTEC
- 6.4.2 DuPont
- 6.4.3 Ecolab Inc.
- 6.4.4 Envirogen Group
- 6.4.5 JACOBI CARBONS GROUP
- 6.4.6 KURARAY CO., LTD.
- 6.4.7 Kurita Water Industries Ltd.
- 6.4.8 LANXESS
- 6.4.9 Norit
- 6.4.10 Onterris, Inc.
- 6.4.11 Puraffinity
- 6.4.12 Puragen
- 6.4.13 ResinTech, Inc.
- 6.4.14 Xylem
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment