

|
시장보고서
상품코드
2119333
전력 변압기 냉각 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Power Transformer Cooling Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
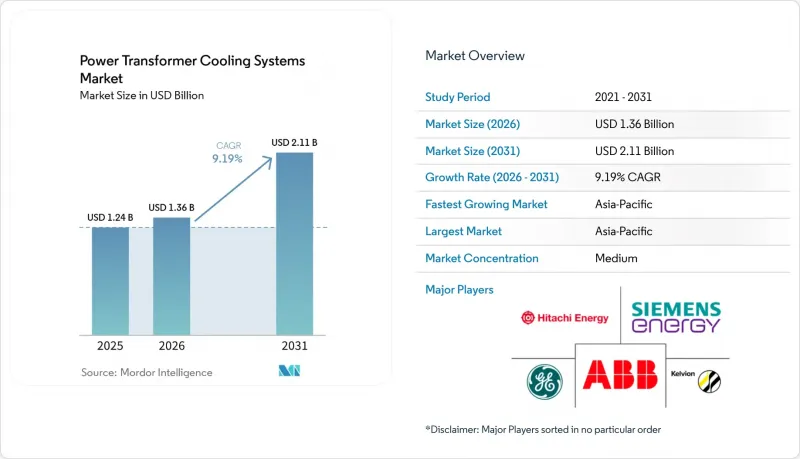
에 의하면, 전력 변압기 냉각 시스템 시장 규모는 2025년 12억 4,000만 달러로 평가되었습니다. 2026년 13억 6,000만 달러에서 2031년까지 21억 1,000만 달러로 확대되어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 9.19%를 나타낼 것으로 예측됩니다.
본 보고서는 냉각 방식(ONAN, ONAF, OFAF, OFWF, 기타), 냉각 장치(라디에이터 및 냉각 패널 등), 최종 사용자(유틸리티, 독립 발전 사업자, 산업·광업 등), 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 전력 변압기 냉각 시스템 시장 동향 및 인사이트
송전망 현대화 및 노후 변압기 교체
송전망 운영 사업자들은 수요 증가에 직면해 있는 반면, 대규모의 신형 변압기를 짧은 프로젝트 일정 내에 확보하는 것은 여전히 어려운 실정입니다. First Energy는 2026년부터 2030년까지 360억 달러 규모의 자본 계획을 발표했으며, 이 중 190억 달러 이상이 송전 인프라에 할당될 예정입니다. 2025년 중반 시점에서 대형 전력 변압기의 납기 기간은 평균 128주, 발전기용 승압 장치의 납기 기간은 평균 144주였습니다. 이러한 리드 타임을 고려할 때, ONAF에서 OFAF로 변환하는 키트, 교체용 라디에이터 뱅크 및 업데이트된 제어반은 이미 송전망에서 가동 중인 설비에 대해 실용적인 용량 증강 방안이 됩니다. 디지털화된 기존 냉각 장치의 도면과 호환 가능한 개조 설계를 통해, 구형 설비의 인터페이스에 맞추기 위해 필요한 설계 작업을 줄일 수 있습니다. 또한, 모듈식 냉각 시스템의 업그레이드를 통해 전력 회사는 교체용 설비의 발주가 진행 중인 동안에도 대상 변압기의 정격을 높일 수 있게 됩니다.
재생에너지 통합 및 열 사이클 증가
풍력 및 태양광 발전의 경우, 출력이 급격히 상승할 때 변압기의 유면 온도나 권선 핫스팟 온도가 반복적으로 변화합니다. 이러한 운전 패턴은 기존의 발전 프로파일보다 누적적인 열 피로를 유발합니다. 계통 연계형 인버터에서 발생하는 고조파 전류는 부유 손실 및 와전류 손실을 증가시켜, 정상 운전 조건을 기반으로 한 모델로는 예측할 수 없는 국부적인 핫스팟을 발생시킬 가능성이 있습니다. 발전기 승압 변압기가 ONAF 구성이 아닌 OFAF 냉각이 필요한 경우, 전력 변압기 냉각 시스템 시장이 혜택을 받게 됩니다. 재생에너지의 발전 패턴은 설치 장소 및 가동 시기를 조사한 연구에서 특히 동서 방향으로 설치된 태양광 발전 설비가 있는 지역에서 변압기 고장률과 관련이 있는 것으로 나타났습니다. 이러한 요구는 관측된 열 조건에 따라 냉각 장치를 작동시키는 모니터링 시스템의 도입을 촉진하고 있습니다.
CRGO 강재, 구리, 알루미늄 및 부품의 리드타임 변동
원자재 가격 변동은 냉각 시스템의 이익률을 낮추고 최종 사용자의 프로젝트 비용을 증가시킬 가능성이 있습니다. 제공된 조사에 따르면, 구리와 알루미늄을 합치면 전력 변압기 제조 비용의 60% 이상을 차지합니다. 또한 2020년부터 2025년에 걸쳐 CRGO 실리콘강의 가격이 톤당 1,700달러에서 2,300달러로 상승한 반면, 같은 기간 전력 변압기 가격은 77% 상승한 것으로 보고되었습니다. 이러한 압박으로 인해 라디에이터,펌프, 팬 및 기타 냉각 장비 공급업체의 견적 유효 기간이 단축되고 있습니다. 이에 따라 장기 계약에는 투입 비용의 변동을 프로젝트 가격에 전가하는 가격 조정 조항이 포함될 수 있습니다. 또한, 미국 연방 정부가 자금을 지원하는 프로젝트의 국내 조달 요건으로 인해 CRGO 강판 및 구리의 조달처 선택지가 더욱 제한될 가능성이 있습니다.
부문 분석
ONAF는 팬 냉각으로 충분한 방열이 가능한 중부하 범위를 지원하기 때문에 2025년 전력 변압기 냉각 시스템 시장에서 36.8%의 점유율을 차지했습니다. 그 도입 실적에는 각 지역에 걸쳐 있는 대용량 배전 변전소, 산업용 서비스 변압기 및 상업용 송전망 설비가 포함됩니다. 이 방식은 강제 송풍 팬을 채택하면서도 능동적인 오일 순환에 따르는 비용과 유지보수의 필요성을 피하고 있습니다. ONAN 시스템은 팬이나 펌프용 보조 전원이 필요하지 않기 때문에 저부하 용도나 지방에서 계속해서 이용되고 있습니다. 또한, 수동적인 설계 덕분에 유지보수의 필요성도 낮습니다. OFWF는 궤도 차량, 양수 발전 및 산업용 용광로용 변압기를 포함한 보다 제한된 용도 그룹에 대응합니다. 수자원을 활용할 수 있기 때문에 OFWF 시스템은 설치 면적을 최소화하면서도 높은 방열 성능을 실현할 수 있습니다.
OFAF는 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 9.8%로 확대될 것으로 예측되며, 본 조사에서 대상으로 한 냉각 방식 중 가장 높은 성장률을 보이고 있습니다. OFAF 기반 전력 변압기 냉각 시스템 시장 규모는 지속적인 열 부하 하에서 가동되는 해상 풍력 발전기의 승압 장치 및 데이터센터의 연결 설비에 의해 뒷받침되고 있습니다. 대형이면서 컴팩트한 변압기의 경우, ONAF 구성에 필요한 방열기의 표면적을 확보할 충분한 공간이 없는 경우가 있습니다. 한 기술 리뷰에 따르면, 고부하 또는 변동 부하 상태의 40 MVA-60 MVA 변압기에서 OFAF 및 오일 지향형 강제 공랭식 시스템이 점점 더 많이 채택되고 있습니다. 능동적인 오일 펌핑은 수동적인 오일 순환에 비해 열 성능을 향상시킵니다. IEC 60076-1 및 더 광범위한 IEC 60076 시리즈는 신규 및 업그레이드된 장비의 냉각 분류 및 공장 내 열 시험을 규정하고 있습니다.
지역별 분석
아시아태평양은 2025년 전력 변압기 냉각 시스템 시장 점유율의 43.6%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 11.3%를 나타낼 것으로 예측됩니다. 중국의 1,000 kV AC 및 ±800 kV DC 초고압 간선망에 대한 투자가 고MVA 변압기에 사용되는 OFAF 및 OFWF 시스템에 대한 수요를 뒷받침하고 있습니다. 인도의 ‘배전 부문 개혁 계획(Revamped Distribution Sector Scheme)’은 347억 6,000만 달러 규모의 프로그램으로, 송전 및 배전 분야의 변압기 조달과 냉각 시스템 업그레이드를 지원하고 있습니다. 일본의 변압기 에너지 효율 기준은 2026년에 시행될 예정이며, 24개 변압기 범주 전반에 걸쳐 11.4%의 효율 개선을 목표로 하고 있습니다. 이러한 요건은 효율이 낮은 냉각 설비의 교체를 촉진하고 있습니다. 인도네시아, 베트남, 태국에서는 송전망 용량 확대가 진행 중이며, 이는 신규 설치 및 개보수 수요를 모두 뒷받침하고 있습니다.
본 조사에서 북미와 유럽은 두 번째로 큰 지역 클러스터를 형성하고 있으며, 변압기 공급 제약이 수요를 좌우하고 있습니다. 히타치 에너지는 2025년 9월, 미국 내 10억 달러 이상의 제조 투자를 발표했습니다. 여기에는 사우스 보스턴 근교에 위치한 대형 전력 변압기 공장에 대한 4억 5,700만 달러의 투자가 포함됩니다. 이 지역의 전력 변압기 냉각 시스템 시장은 공급 부족 시의 설비 갱신 및 냉각 시스템 개보수로부터도 혜택을 받고 있습니다. 히타치 에너지는 2025년 7월, 독일의 송전망 인프라 공급과 관련하여 E.ON사와 최대 7억 달러 규모의 계약을 체결했습니다. 슈타트베르케 카를스루에(Stadtwerke Karlsruhe)는 2025년부터 5년에 걸쳐 3,600만 유로(3,900만 달러) 이상을 투자하여 고전압 인프라를 정비하는 한편, 4개 변전소에 설치된 수명이 다한 변압기 9기를 교체하는 프로그램을 시작했습니다. 북해 및 발트해의 해상 풍력 발전 증설도 100 MVA를 초과하는 발전기용 승압 변압기를 위한 선박용 등급의 OFAF 및 OFWF 시스템에 대한 수요를 뒷받침하고 있습니다.
남미, 중동 및 아프리카의 합산 점유율은 작지만, 2031년까지 중요한 성장 지역으로 남아 있을 것입니다. WEG사는 브라질의 변압기 생산 능력에 5억 4,300만 브라질 레알(9,900만 달러)을 투자한다고 발표했습니다. 여기에는 최대 230 kV 전압 등급에 대응하는 생산 능력도 포함됩니다. 베팀 공장의 확장으로 2026년 중반까지 생산 능력이 10% 증가할 것으로 예측됩니다. 또한 WEG는 브라질 아시스 변전소에 525 kV 단상 500 MVA 변압기 3기를 납품했습니다. 사우디아라비아의 ‘비전 2030’ 송전망 계획, UAE의 데이터센터 개발, 그리고 북아프리카의 태양광 발전 프로젝트가 새로운 변압기 수요를 뒷받침하고 있습니다. 사하라 이남 아프리카에서는 전기화 진전과 산업 투자 증가에 따라 장기적인 잠재 수요가 예상됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the power transformer cooling systems market size is projected to expand from USD 1.24 billion in 2025 and USD 1.36 billion in 2026 to USD 2.11 billion by 2031, at a CAGR of 9.19% between 2026 and 2031.
This report is Segmented by Cooling Method (ONAN, ONAF, OFAF, OFWF, Other), Cooling Equipment (Radiators and Cooling Panels, and More), End User (Utilities, Independent Power Producers, Industrial and Mining, and More), and Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Power Transformer Cooling Systems Market Trends and Insights
Grid Modernization and Aging Transformer Replacement
Grid operators face rising demand while large new transformers remain difficult to secure within short project schedules. FirstEnergy announced a USD 36 billion capital plan for 2026 through 2030, including more than USD 19 billion for transmission infrastructure. Large power transformers averaged 128 weeks for delivery by mid-2025, and generator step-up units averaged 144 weeks. These lead times make ONAF-to-OFAF conversion kits, replacement radiator banks, and updated control panels practical capacity measures for equipment already operating on the grid. Digitized legacy cooler drawings and compatible retrofit designs can reduce the engineering effort needed to match old equipment interfaces. Modular cooling upgrades also allow utilities to uprate selected transformers while replacement equipment remains on order.
Renewable Energy Integration and Higher Thermal Cycling
Wind and solar generation expose transformers to repeated top-oil and winding hot-spot temperature changes during rapid output ramps. These operating patterns create more cumulative thermal fatigue than conventional generation profiles. Harmonic currents from grid-tied inverters can increase stray and eddy-current losses and create localized hot spots beyond models based on steady operating conditions. The power transformer cooling systems market benefits when generator step-up transformers need OFAF cooling rather than ONAF configurations. Renewable generation patterns were associated with transformer failure rates in research that examined location and operating timing, especially in areas with east-west photovoltaic installations. This need also supports monitoring systems that activate cooling equipment in response to observed thermal conditions.
CRGO Steel, Copper, Aluminum and Component Lead-Time Volatility
Material price changes can reduce cooling system margins and increase the cost of projects for end users. The supplied research states that copper and aluminum together account for more than 60% of power transformer manufacturing costs. It also reports that CRGO silicon steel prices increased from USD 1,700 per ton to USD 2,300 per ton between 2020 and 2025, while power transformer prices rose 77% over that period. These pressures shorten quotation validity periods for suppliers of radiators, pumps, fans, and other cooling equipment. Long-term contracts may therefore include escalation clauses that pass changes in input costs into project pricing. Domestic content conditions for federally funded U.S. projects can further limit sourcing choices for CRGO steel and copper inputs.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscale Data Center and Electrification Load Growth
- Industrial and Mining Electrification in Emerging Economies
- High Installed Cost and Skilled-Service Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ONAF held 36.8% of the power transformer cooling systems market share in 2025 because it serves the medium-load range where fan cooling provides sufficient heat removal. Its installed base includes bulk distribution substations, industrial service transformers, and commercial grid equipment across regions. The arrangement uses forced-air fans while avoiding the cost and maintenance needs of active oil circulation. ONAN systems continue to serve lower-load and rural applications because they do not require ancillary power for fans or pumps. Their passive design also has low maintenance requirements. OFWF serves a smaller application group that includes traction, pumped-storage hydro, and industrial furnace transformers. Water availability allows OFWF systems to achieve high heat rejection with a smaller site footprint.
OFAF is projected to expand at a 9.8% CAGR from 2026 through 2031, the fastest rate among cooling methods in the supplied research. The power transformer cooling systems market size for OFAF is supported by offshore wind generator step-up units and data center connections that operate under sustained thermal loads. Large compact transformers can lack enough room for the radiator surface area that an ONAF configuration would require. A technical review found that OFAF and oil-directed air-forced systems are increasingly specified for transformers above 40 MVA to 60 MVA under high or variable loads. Active oil pumping improves thermal performance compared with passive oil circulation. IEC 60076-1 and the wider IEC 60076 series govern cooling classifications and factory thermal testing for new and upgraded units.
Complete Report Scope:
- By Cooling Method
- Oil Natural Air Natural (ONAN)
- Oil Natural Air Forced (ONAF)
- Oil Forced Air Forced (OFAF)
- Oil Forced Water Forced (OFWF)
- Other Cooling Systems
- By Cooling Equipment
- Radiators and Cooling Panels
- Cooling Fans and Blowers
- Oil Pumps and Valves
- Oil-to-Air Heat Exchangers
- Oil-to-Water Heat Exchangers
- Cooling Control Panels and Monitoring Units
- Other Cooling Equipment
- By End User
- Utilities
- Independent Power Producers
- Industrial and Mining
- Commercial Infrastructure and Data Centers
- Renewable Energy Operators
- Rail and Traction Operators
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific accounted for 43.6% of the power transformer cooling systems market share in 2025 and is forecast to grow at an 11.3% CAGR through 2031. China's 1,000 kV AC and +-800 kV DC ultra-high-voltage backbone investments support demand for OFAF and OFWF systems used in high-MVA transformers. India's Revamped Distribution Sector Scheme is a USD 34.76 billion program that supports transformer procurement and cooling upgrades across transmission and distribution. Japan's energy efficiency standards for transformers became effective in 2026 and target an 11.4% improvement across 24 transformer categories. These requirements support the replacement of less efficient cooling configurations. Indonesia, Vietnam, and Thailand are expanding grid capacity, which supports both new installation and retrofit demand.
North America and Europe form the next-largest regional cluster in the supplied research, with demand shaped by transformer supply constraints. Hitachi Energy announced more than USD 1 billion of U.S. manufacturing investment in September 2025, including USD 457 million for a large power transformer facility near South Boston. The power transformer cooling systems market in these regions also benefits from equipment replacement and cooling retrofits during supply shortages. Hitachi Energy signed an agreement worth up to USD 700 million with E.ON in July 2025 for German grid infrastructure delivery. Stadtwerke Karlsruhe began a five-year program in 2025 to invest more than EUR 36 million, or USD 39 million, in high-voltage infrastructure and replace 9 end-of-life transformers across 4 substations. Offshore wind additions in the North Sea and Baltic also support demand for marine-grade OFAF and OFWF systems in generator step-up transformers above 100 MVA.
South America and the Middle East and Africa have smaller combined shares but remain important expansion areas through 2031. WEG announced BRL 543 million, or USD 99 million, of investment in transformer capacity in Brazil, including capacity for voltage classes up to 230 kV. The Betim expansion was expected to add 10% of production capacity by mid-2026. WEG also supplied three single-phase 500 MVA transformers at 525 kV for Brazil's Assis Substation. Saudi Arabia's Vision 2030 grid program, data center development in the UAE, and North African solar projects support new transformer demand. Sub-Saharan Africa offers longer-term potential as electrification and industrial investment increase.
- ABB Ltd.
- Alfa Laval AB
- Bharat Heavy Electricals Limited
- CG Power and Industrial Solutions Limited
- GE Vernova Inc.
- Hitachi Energy Ltd.
- Hyosung Heavy Industries Corporation
- Kelvion Holding GmbH
- Luvata Soderkoping AB
- M&I Materials Limited
- Modine Manufacturing Company
- Radiator Manufacturing Company
- Siemens Energy AG
- SPX Technologies, Inc.
- Sterling Thermal Technology
- Tada Electric Co., Ltd.
- Thermofin GmbH
- Toshiba Energy Systems & Solutions Corporation
- Trantech Radiator Products, Inc.
- United Heat Exchanger
- WEG S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Grid Modernization and Aging Transformer Replacement
- 4.2.2 Renewable Energy Integration and Higher Thermal Cycling
- 4.2.3 Hyperscale Data Center and Electrification Load Growth
- 4.2.4 Industrial and Mining Electrification in Emerging Economies
- 4.2.5 Legacy Cooler Drawing Digitization and Retrofit Compatibility
- 4.2.6 Modular Cooling Upgrades for Transformer Uprating
- 4.3 Market Restraints
- 4.3.1 CRGO Steel, Copper, Aluminum and Component Lead-Time Volatility
- 4.3.2 High Installed Cost and Skilled-Service Requirements
- 4.3.3 Legacy Cooler Interface Fragmentation and Qualification Burden
- 4.3.4 Cybersecurity and Interoperability Risk in Connected Controls
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Cooling Method
- 5.1.1 Oil Natural Air Natural (ONAN)
- 5.1.2 Oil Natural Air Forced (ONAF)
- 5.1.3 Oil Forced Air Forced (OFAF)
- 5.1.4 Oil Forced Water Forced (OFWF)
- 5.1.5 Other Cooling Systems
- 5.2 By Cooling Equipment
- 5.2.1 Radiators and Cooling Panels
- 5.2.2 Cooling Fans and Blowers
- 5.2.3 Oil Pumps and Valves
- 5.2.4 Oil-to-Air Heat Exchangers
- 5.2.5 Oil-to-Water Heat Exchangers
- 5.2.6 Cooling Control Panels and Monitoring Units
- 5.2.7 Other Cooling Equipment
- 5.3 By End User
- 5.3.1 Utilities
- 5.3.2 Independent Power Producers
- 5.3.3 Industrial and Mining
- 5.3.4 Commercial Infrastructure and Data Centers
- 5.3.5 Renewable Energy Operators
- 5.3.6 Rail and Traction Operators
- 5.3.7 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Alfa Laval AB
- 6.4.3 Bharat Heavy Electricals Limited
- 6.4.4 CG Power and Industrial Solutions Limited
- 6.4.5 GE Vernova Inc.
- 6.4.6 Hitachi Energy Ltd.
- 6.4.7 Hyosung Heavy Industries Corporation
- 6.4.8 Kelvion Holding GmbH
- 6.4.9 Luvata Soderkoping AB
- 6.4.10 M&I Materials Limited
- 6.4.11 Modine Manufacturing Company
- 6.4.12 Radiator Manufacturing Company
- 6.4.13 Siemens Energy AG
- 6.4.14 SPX Technologies, Inc.
- 6.4.15 Sterling Thermal Technology
- 6.4.16 Tada Electric Co., Ltd.
- 6.4.17 Thermofin GmbH
- 6.4.18 Toshiba Energy Systems & Solutions Corporation
- 6.4.19 Trantech Radiator Products, Inc.
- 6.4.20 United Heat Exchanger
- 6.4.21 WEG S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

(주말 및 공휴일 제외)


