|
시장보고서
상품코드
2119675
자동차 페시아 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Fascia - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
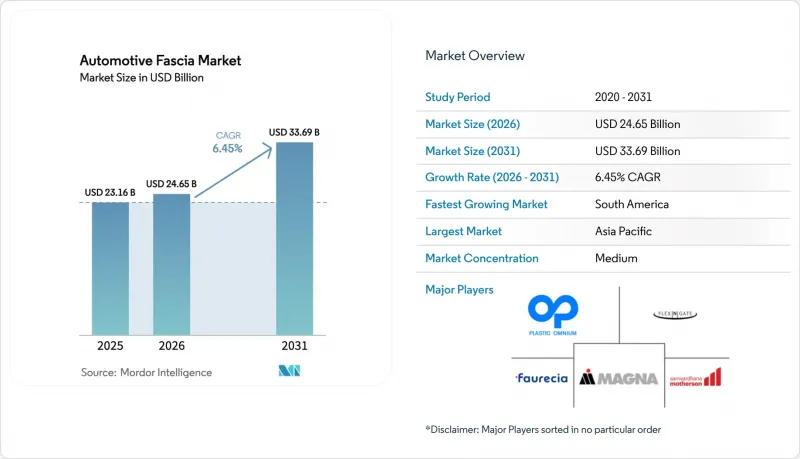
에 따르면 자동차 페시아 시장 규모는 2025년에 231억 6,000만 달러로 평가되며, 2026년 246억 5,000만 달러에서 2031년까지 336억 9,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 6.45%가 될 전망입니다.
본 보고서는 위치 유형(프론트 페시아, 리어 페시아), 소재(플라스틱 코팅 발포 스티로폼, 플라스틱 코팅 알루미늄 등), 차량 유형(승용차 등), 판매 채널(OEM, 애프터마켓) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 자동차 페시아 시장의 동향 및 인사이트
전기자동차(EV) 및 자율주행차 플랫폼의 성장
전기자동차(EV)의 보급으로 냉각 부하가 변화하여 그릴이 없는 오픈 디자인이 가능해진 반면, 공급업체들은 공기 저항을 증가시키지 않으면서 LiDAR, 4D 레이더, 고해상도 카메라를 탑재할 수 있는 페시아 모듈의 재설계를 요구받고 있습니다. 현대모비스는 액티브 셔터, 밀리미터파 레이더, 카메라 세척 시스템을 단일 하위 어셈블리로 통합한 전기자동차용 통합형 프론트 페시아 유닛을 발표했습니다. 또한, 마렐리(Marelli)는 헤사이(Hesai)와의 제휴를 발표하고, 헤드램프 하우징에 LiDAR를 통합함으로써 센싱 하드웨어를 범퍼 스킨에서 조명 클러스터로 이전했습니다. 또한, 프리미엄 800V 전기자동차의 경우 고주파 스위칭을 위한 전자기 차폐가 필요하기 때문에 대시보드 패널에는 EMI 대책으로 알루미늄 필름과 플라스틱 탑코트를 조합한 소재가 채택되고 있습니다.
경량화 및 배기가스 규제 대응
EU의 CO₂ 배출량 상한선 강화와 북미의 CAFE 목표에 따라, 각 OEM 업체들은 FMVSS 충돌 시험을 통과하면서도 경량 구조를 실현해야 하는 압박을 받고 있습니다. 탄소섬유 강화 플라스틱(CFRP)은 강재에 비해 최대 60%의 경량화를 실현하면서도 동등한 충돌 에너지 흡수 성능을 발휘합니다. Constellium의 M-LightEn 컨소시엄은 재활용률 80%의 초고강도 알루미늄 소재를 상품화하여 부품의 탄소 강도를 절반으로 줄였습니다. Toyoda Gosei는 경량화와 전체 수명주기 동안의 배출량 감축을 목표로, 셀룰로오스 나노섬유 강화 폴리프로필렌의 검증을 진행하고 있습니다. 센서 추가로 인해 무게가 증가하기 때문에 엔지니어들은 LiDAR 하우징 및 레이더 레돔 설계 시 경량화와 무게 증가의 균형을 조정하고 있습니다.
높은 유지보수 및 교체 비용
주차 중 발생한 경미한 긁힘 후 수행하는 레이더 및 카메라 모듈의 보정은 수리 비용을 37%까지 끌어올릴 가능성이 있어, 보험사의 수익성과 소비자의 지불 의지에 문제를 야기하고 있습니다. OEM 인증 범퍼용 도료는 레이더 투과성을 유지해야 하므로, 수리용 도료의 선택지가 좁아지고, 고가의 정렬 장비를 갖춘 인증 정비 공장에 의뢰해야 하는 상황이 조성되고 있습니다. 독립 정비 공장은 ADAS 보정 베이에 5자리 수의 투자를 강요받고 있으며, 이는 시장 통합을 가속화하고 있습니다. 또한 부품의 복잡화로 인해 작업 중단 시간도 길어지고 렌터카 이용 일수가 증가함에 따라, 보험사는 Tier 1 공급업체와 더 큰 폭의 부품 할인 협상을 해야 하는 상황에 처해 있습니다.
부문 분석
2025년, 프론트 페시아 어셈블리는 자동차용 페시아 시장 점유율의 63.78%를 차지하며, 공기 저항 감소 및 보행자 보호에 있어 그 핵심적인 역할을 부각시켰습니다. 이 부문은 전면 면적을 확대하지 않고도 고해상도 카메라, 장거리 레이더, 세척 노즐을 장착해야 할 필요성에 힘입어 연평균 성장률(CAGR) 6.66%로 성장할 것으로 예측됩니다. 일련의 설계 주기에 걸쳐, 결빙된 기후에서도 센서의 가동 시간을 확보하기 위해 워셔액 유로와 발열체가 범퍼 빔 내에 직접 통합되도록 설계되었습니다. 리어 페이시아 시스템의 매출은 이에 미치지 못하지만, 자동 주차 소프트웨어를 지원하는 스마트 조명 어레이와 주차용 레이더에 대응하기 위해 마찬가지로 진화를 거듭하고 있습니다.
Valeo는 동적 방향 지시등이나 자전거 이용자에게 경고를 표시하는 내장형 마이크로 LED 매트릭스를 인쇄한 페이시아 스킨의 검증을 시작했으며, 이는 커뮤니케이션을 중시하는 외관의 선구자가 되고 있습니다. 향후 시행될 NHTSA의 FMVSS 제228호 규정 개정에 따라, 두부 손상 기준을 1,000 HIC 이하로 유지하는 규격에 부합하는 충돌 테스트용 캔 및 변형성 폼의 필요성이 높아지고 있으며, 이에 따라 고분자 화학자와 충돌 시뮬레이션 엔지니어 간의 협력이 더욱 깊어지고 있습니다. 세포 구조를 최적화한 바이오 폴리프로필렌 폼은 에너지 흡수성과 재활용성을 모두 갖춘 소재로 주목받고 있습니다.
플라스틱 코팅 발포 스티로폼은 성형 비용의 안정화와 전 세계적인 금형 확보 가능성으로 인해 2025년 자동차용 페시아 시장에서 46.10%의 점유율을 유지했습니다. 그러나 전기자동차 제조사들이 인버터의 열을 방출하기 위해 알루미늄의 열전도율을 활용하고 있기 때문에 플라스틱 코팅 알루미늄 패널은 2031년까지 연평균 성장률(CAGR) 5.96%로 성장할 전망입니다. 충격 개질 PP 외피를 적층한 두께 1mm의 알루미늄 기판은 동등한 PP/EPP 발포체보다 15% 가벼우면서도 보행자 충돌 시험을 통과했습니다. 새롭게 등장한 복합 외피는 바이오 폴리우레탄 백폼과 재생 알루미늄 필름을 결합한 것으로, OEM 각사는 크래들-투-게이트(cradle-to-gate) CO₂ 배출량 감축을 어필할 수 있게 됩니다.
MacDermid Enthone은 저온에서 플라스틱 오버몰딩이 가능하고 블리스터링(기포 발생)이 발생하지 않는 양극 산화 처리용 약제를 출시하여, 금속과 폴리머 외피 간의 접합을 합리화했습니다. 음료 캔에서 회수된 알루미늄 스크랩이 Constellium의 제품 등급에 활용되고 있어, 자동차용 페시아 업계에서 순환 경제로의 진전이 입증되고 있습니다. 강철과 고무의 혼합 소재는 중량 문제보다 돌 튀김에 대한 내성이 우선시되는 대형 트럭 시장에서 틈새 시장을 구축하고 있습니다.
지역별 분석
2025년, 아시아태평양은 매출 점유율의 47.96%를 차지하며 자동차 페시아 시장의 제조 거점으로서의 입지를 공고히 했습니다. 중국은 2024년 기준 세계 최대 규모의 자동차 생산국 중 하나이며, 페이시아, 크래시 빔, 배터리 트레이를 한 번의 알루미늄 주조로 성형할 수 있는 기가 캐스팅(Giga Casting) 시범 프로젝트를 지속적으로 확대하고 있어, 이를 통해 부품 수를 줄이는 데 주력하고 있습니다. 인도의 자동차 부품 로드맵은 2026 회계연도까지 2,000억 달러의 매출을 목표로 하고 있으며, 현지 부가가치의 최대 13%를 환급하는 생산 연계형 인센티브에 의해 뒷받침되고 있습니다. 혼다가 캐나다의 전기자동차(EV) 밸류체인 구축에 150억 캐나다 달러(110억 달러)를 투자함에 따라, 아시아의 1차 금형 제조업체들에게 북미로 향하는 새로운 수출 경로가 열리게 될 것입니다.
남미는 연평균 성장률(CAGR) 6.98%로 가장 빠르게 성장하는 지역이며, 스텔란티스는 브라질과 아르헨티나에서 구축될 바이오 하이브리드 구동 시스템 플랫폼에 56억 유로를 투자하고 있습니다. 바이오에탄올을 사용하는 범퍼에는 당류 기반 연료의 비말에 내성이 있는 코팅이 필요하며, 이로 인해 현지 배합 제조업체들은 수지의 화학 성분을 조정해야 하는 상황에 처해 있습니다. 콜롬비아는 이 지역에서 세 번째로 큰 조립 거점이 되었지만, 페루는 자유무역협정을 활용하여 플라스틱 인서트와 크롬 트림을 관세 없이 미국으로 수출하고 있습니다. 환율 변동은 여전히 비용 계획상의 장벽으로 작용하고 있어, 공급업체들은 수지 계약을 달러로 헤지하는 경향이 강해지고 있습니다.
북미와 유럽은 규제 동향을 주도하는 주체로 여전히 전략적으로 중요한 위치를 차지하고 있습니다. NHTSA(미국 도로교통안전국)가 검토 중인 보행자 보호 규제는 이미 2026년형 북미용 프론트 페시아 디자인에 반영되었습니다. EU의 순환 경제 행동 계획은 트림 부품에 재생 플라스틱 사용을 촉진함과 동시에, 수지의 원산지를 기록하는 디지털 여권 도입을 장려하고 있습니다. 홍해 항로의 전쟁 리스크 프리미엄 급등으로 인해, 각 OEM 기업들은 멕시코나 동유럽에서 프론트 패널 금형의 니어쇼어링을 추진하고 있습니다. 유럽 내 전기자동차(EV) 보급 속도는 그릴리스 디자인의 신속한 사이클을 요구하고 있습니다. 한편, 미국의 수요는 충전 인프라 구축 상황에 좌우되기 때문에 위험을 줄이기 위해 동일한 생산 라인에서 내연기관 차량(ICE)과 전기자동차용 전면 패널을 혼용하는 단계적 금형 계획이 채택되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the automotive fascia market size was valued at USD 23.16 billion in 2025 and estimated to grow from USD 24.65 billion in 2026 to reach USD 33.69 billion by 2031, at a CAGR of 6.45% during the forecast period (2026-2031).
This report is Segmented by Position Type (Front Fascia and Rear Fascia), Material (Plastic Covered Styrofoam, Plastic Covered Aluminum, and More), Vehicle Type (Passenger Cars and More), Sales Channel (OEM and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Fascia Market Trends and Insights
Growth of EV and Autonomous Vehicle Platforms
Electric vehicles change cooling loads and open grille-less design options, forcing suppliers to redesign fascia modules that can mount LiDAR, 4D radar, and high-resolution cameras without raising drag. Hyundai Mobis has introduced integrated front-face units for battery cars that package active shutters, millimeter-wave radar, and camera cleaning systems into a single sub-assembly. Additionally, Marelli announced a partnership with Hesai to embed LiDAR into headlamp housings, shifting sensing hardware from bumper skins to lighting clusters. Moreover, premium 800-volt EVs need electromagnetic shielding for high-frequency switching, so fascia panels blend aluminum films with plastic topcoats for EMI control.
Light-weighting and Emission-Regulation Compliance
Stricter CO2 caps in the EU and CAFE targets in North America push OEMs toward lighter structures that still pass FMVSS impact tests. Carbon-fiber reinforced plastics cut as much as 60% mass versus steel yet deliver the same crush-energy absorption. Constellium's M-LightEn consortium commercializes ultra-high-strength aluminum grades with 80% recycled content, reducing component carbon intensity by half. Toyoda Gosei is validating cellulose-nanofiber reinforced polypropylene to trim weight and cradle-to-grave emissions. Sensor additions add weight back in, so engineers juggle mass savings with LiDAR housings and radar radomes.
High Maintenance and Replacement Cost
Calibration of radar and camera modules after a minor parking scrape can lift repair bills by 37%, challenging insurer economics and consumer willingness to pay. OEM-approved bumper paints must remain radar-transparent, narrowing repair-paint options and steering work to certified centers with costly alignment rigs. Independent shops face five-figure investments in ADAS calibration bays, prompting market consolidation. The higher part complexity also boosts idle time, raising rental-car days and pushing insurers to negotiate deeper part discounts with Tier 1 vendors.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Advanced Sensing (LiDAR/Radar) into Fascia
- Modular Front-End Modules Adoption by OEMs
- ADAS-Led Fall in Collision Frequency
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Front fascia assemblies represented 63.78% automotive fascia market share in 2025, underscoring their central role in aerodynamic drag reduction and pedestrian protection. This segment is forecast to progress at a 6.66% CAGR, fuelled by the need to mount high-definition cameras, long-range radar and cleaning nozzles without enlarging frontal area. Successive design cycles now route washer-fluid channels and heating elements directly into the bumper beam to guarantee sensor uptime in icy climates. Rear fascia systems trail in revenue but are also evolving to accommodate smart-lighting arrays and parking radars that help automated-parking software.
Valeo has begun validating fascia skins printed with embedded micro-LED matrices that deliver dynamic turn signals and cyclist alerts, a preview of communication-centric exteriors. The upcoming NHTSA FMVSS No. 228 rule changes amplify the need for compliant crush cans and deformable foams that maintain head-injury criteria below 1,000 HIC, driving deeper collaboration between polymer chemists and crash-simulation engineers. Bio-polypropylene foams with tuned cell geometry have emerged as candidates to balance energy absorption with recyclability.
Plastic-covered styrofoam retained a 46.10% slice of the automotive fascia market in 2025 due to mature molding economics and global tooling availability. Yet plastic-covered aluminum panels are on track for a 5.96% CAGR to 2031 as EV makers exploit aluminum's thermal conductivity to dissipate inverter heat. Thin 1 mm aluminum substrates laminated with impact-modified PP outer skins weigh 15% less than comparable PP/EPP foams while passing pedestrian impact. Emerging composite skins blend bio-polyurethane back-foams with recycled aluminum films, allowing OEMs to advertise lower cradle-to-gate CO2.
MacDermid Enthone has released anodizing chemistries that accept low-temperature plastics over-molding without blistering, streamlining joins between metal and polymer skins. Recycled aluminum scrap flows from beverage cans into Constellium grades, proving automotive fascia industry progress toward circularity. Steel and rubber blends hold niche beachheads in heavy-duty trucks where stone-chip resistance outweighs weight concerns.
Complete Report Scope:
- By Position Type
- Front Fascia
- Rear Fascia
- By Material
- Plastic-covered Styrofoam
- Plastic-covered Aluminum
- Other Materials (Steel, Rubber, etc.)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- By Sales Channel
- OEM
- Aftermarket
- By Region
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
In 2025, Asia Pacific secured 47.96% of the revenue share, solidifying its position as the manufacturing epicenter of the automotive fascia market. China is one of the largest producers of vehicles in 2024 and keeps scaling gigacasting pilots that could roll fascia, crash beam, and battery tray into one aluminum shot, reducing part counts. India's auto-components roadmap targets a USD 200 billion turnover by FY26, supported by production-linked incentives that reimburse up to 13% of local value addition. Honda's CAD 15 billion (USD 11 billion) commitment to develop a Canadian EV supply chain will open new North American export routes for Asian Tier 1 tooling firms.
South America is the fastest-growing region, with a 6.98% CAGR as Stellantis channels EUR 5.6 billion into Bio-Hybrid drivetrain platforms built in Brazil and Argentina. Bio-ethanol-compatible bumpers require coatings resistant to sugar-based fuel sprays, prompting local formulators to adapt resin chemistries. Colombia has become the region's third-largest assembler, while Peru leverages free-trade agreements to ship plastic inserts and chrome trims into the United States duty-free. Exchange-rate volatility remains a cost-planning hurdle, so suppliers increasingly hedge resin contracts in USD.
North America and Europe retain strategic importance as regulation trend-setters. NHTSA's pending pedestrian rule is already embedded in 2026 model-year North American fascia designs. The EU Circular Economy Action Plan pushes recyclates into trim components and incentivizes digital passports that log resin genealogy. War-risk premiums on Red Sea freight lanes have nudged OEMs toward near-shoring fascia tool builds in Mexico and Eastern Europe. Europe's EV adoption pace demands fast cycles on grille-less styling; conversely, US demand is tied to charging-infrastructure roll-outs, leading to phased tooling plans that mix ICE and EV fascias on the same line for risk mitigation.
- Plastic Omnium
- Magna International
- Faurecia SE
- Flex-N-Gate Corporation
- Samvardhana Motherson Group
- Gestamp Automocion
- Toyoda Gosei
- Dongfeng Electronic Technology
- Aisin Corporation
- Benteler Automotive
- Denso Corporation
- Yanfeng Automotive Trim
- Sanko Gosei
- Chiyoda Manufacturing
- Dakkota Integrated Systems
- Revere Plastics Systems
- Inhance Technologies
- Eakas Corporation
- MRC Manufacturing
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of EV and Autonomous Vehicle Platforms
- 4.2.2 Light-weighting and Emission-Regulation Compliance
- 4.2.3 Integration of Advanced Sensing (LiDAR/Radar) into Fascia
- 4.2.4 Increasing Vehicle Production and Sales
- 4.2.5 Modular Front-End Modules Adoption by OEMs
- 4.2.6 Shift to Recycled & Bio-Based Polymers
- 4.3 Market Restraints
- 4.3.1 Raw-Material Price Volatility
- 4.3.2 High Maintenance and Replacement Cost
- 4.3.3 ADAS-Led Fall in Collision Frequency
- 4.3.4 OEM Vertical Integration Curbing Aftermarket
- 4.4 Value / Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Position Type
- 5.1.1 Front Fascia
- 5.1.2 Rear Fascia
- 5.2 By Material
- 5.2.1 Plastic-covered Styrofoam
- 5.2.2 Plastic-covered Aluminum
- 5.2.3 Other Materials (Steel, Rubber, etc.)
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.4 By Sales Channel
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Egypt
- 5.5.5.4 South Africa
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Plastic Omnium
- 6.4.2 Magna International
- 6.4.3 Faurecia SE
- 6.4.4 Flex-N-Gate Corporation
- 6.4.5 Samvardhana Motherson Group
- 6.4.6 Gestamp Automocion
- 6.4.7 Toyoda Gosei
- 6.4.8 Dongfeng Electronic Technology
- 6.4.9 Aisin Corporation
- 6.4.10 Benteler Automotive
- 6.4.11 Denso Corporation
- 6.4.12 Yanfeng Automotive Trim
- 6.4.13 Sanko Gosei
- 6.4.14 Chiyoda Manufacturing
- 6.4.15 Dakkota Integrated Systems
- 6.4.16 Revere Plastics Systems
- 6.4.17 Inhance Technologies
- 6.4.18 Eakas Corporation
- 6.4.19 MRC Manufacturing
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment