

|
시장보고서
상품코드
2120254
수용성 폴리머 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Water-soluble Polymer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 수용성 폴리머 시장 규모는 2026년에 392억 2,000만 달러로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 4.57%로 성장을 지속하여, 2031년에는 490억 4,000만 달러에 이를 전망입니다.
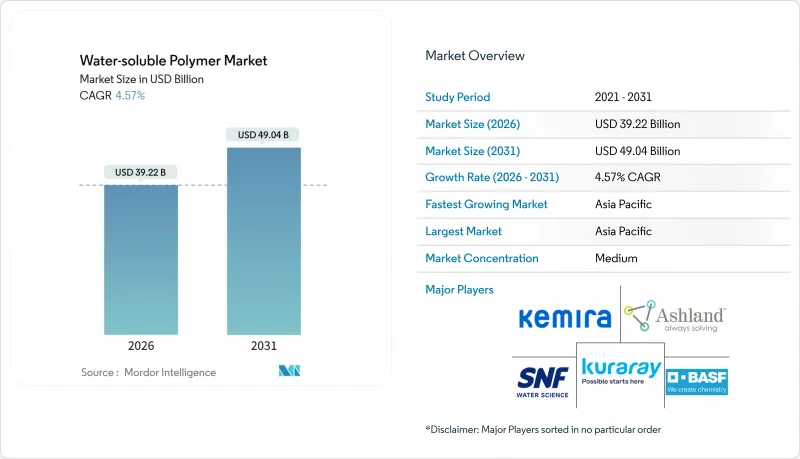
본 보고서는 유형별(폴리아크릴아미드, 폴리비닐알코올, 구아검, 젤라틴, 잔탄검, 폴리아크릴산, 폴리에틸렌글리콜, 기타),최종 사용자 산업별(수처리, 식품 및 음료, 퍼스널케어 및 위생, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(미화) 기준으로 제시되어 있습니다.
전 세계 수용성 폴리머 시장 동향 및 인사이트
전 세계 도시 및 산업 폐수 처리에 대한 투자 급증
2025년, 전 세계 폐수 처리에 대한 지출은 상당한 수준에 도달했습니다. 이러한 투자의 급증으로 인해, 슬러지 부피를 줄이고 처리 비용을 절감하는 능력으로 알려진 초고분자량 음이온성 폴리아크릴아미드 수요가 증가했습니다. 2025년 말까지 중국은 전국적으로 ‘클래스 1A’ 폐수 배출 기준을 도입했으며, 이로 인해 폴리아크릴아미드 소비량이 증가했습니다. 한편, 인도의 ‘깨끗한 갠지스강 국가 미션’에서는 새로운 하수 처리장 건설에 막대한 자금이 배정되었습니다. 이러한 처리장에는 각각 폴리머 응집제가 필요합니다. 중동에서는 2025년에 새로 가동을 시작한 해수 담수화 프로젝트에서 폴리아크릴산 및 폴리에틸렌글리콜계 스케일 방지제가 채택되었습니다. 이들은 새로운 처리 용량에서 막을 보호하는 데 필수적인 요소입니다. 이러한 노력들이 어우러져, 지자체 및 산업 분야 관계자들이 수용성 폴리머 시장의 리더로서의 입지를 확고히 하고 있습니다.
북미의 셰일가스용 폴리머 수요 회복
2025년, 북미의 사업자들은 원유 가격 안정화와 동시에 수용성 폴리머를 대량으로 소비했습니다. 폴리머 플러딩의 주력 제품인 부분 가수분해 폴리아크릴아미드는 기존의 수압 주입에 비해 회수량 증가라는 장점이 있습니다. 한편, 잔탄검은 2024년부터 2025년까지 가동을 시작한 미국의 새로운 생산 능력에 힘입어, 고염분 저류층에서 시장 점유율을 확대되고 있습니다. 또한, 연방 정부의 보조금을 통해 지층 손상을 완화하기 위한 열안정성·생분해성 공중합체에 대한 연구가 촉진되고 있습니다. 이러한 동향은 전반적으로, 수용성 폴리머 시장을 견인하는 데 있어 유전이 수행하는 지극히 중요한 역할을 부각시키고 있습니다.
원자재 가격 변동
2024년부터 2025년까지 중국의 프로파일렌 공급 차질로 인해 아크릴로니트릴 가격이 크게 변동했습니다. 이러한 변동으로 인해 폴리아크릴아미드의 이익률이 압박을 받았습니다. 마찬가지로, 같은 기간 동안 비닐아세테이트 모노머 가격도 현저히 급등했습니다. 한편, 인도의 가뭄으로 인해 수확량이 급감하면서 구아검 가격도 급등했습니다. 이러한 가격 변동은 수용성 폴리머 시장에서 비용 예측의 어려움을 여실히 보여주고 있습니다.
부문 분석
폴리아크릴아미드는 2025년 매출의 24.48%를 차지하며, 2031년까지 연평균 성장률(CAGR) 4.75%로 성장할 전망입니다. 이러한 성장은 주로 새로 시행된 인(P) 배출 규제에 기인한 것으로, 해당 규제로 인해 초고분자량 등급의 폴리아크릴아미드가 선호되고 있습니다. 이러한 등급은 슬러지 처리 비용을 대폭 절감할 수 있습니다. 그 결과, 폴리아크릴아미드는 수용성 폴리머 시장, 특히 수처리용 화학약품 분야에서 매우 중요한 역할을 할 것으로 전망됩니다. 한편, 일회용 세제에 널리 사용되는 PVA 필름은 강력한 성장세를 보이고 있습니다. 그러나 미세 플라스틱에 대한 규제 가능성이 시급한 과제로 대두되고 있습니다. 구아검은 인도의 수확 부진에 기인한 원자재 리스크에 직면해 있으며, 파쇄액 분야에서는 크산탄검으로의 뚜렷한 전환이 관찰되었습니다. 젤라틴은 아시아태평양의 수탁 제조 기업(CMO)에 의한 고블룸 제품 생산 증가에 힘입어 소프트젤 캡슐 시장에서 계속해서 지배적인 위치를 유지하고 있습니다. 폴리아크릴산 및 폴리아크릴산나트륨은 위생용품 및 냉각수 스케일 방지 용도에서 수요가 증가하고 있습니다. 이러한 수요 급증은 캘리포니아주의 엄격한 소비자 제품 규정을 준수하는 잔류 모노머 함량이 낮은 신제품 등급의 도입에 의해 더욱 가속화되고 있습니다. PEG는 주사제 및 화장품 분야에서 여전히 수요가 높은 성분이지만, 이에 대한 규제가 강화됨에 따라 연구 개발은 생물 유래 대체재로 중심을 옮겨가고 있습니다. 또한, 셀룰로오스 에테르, 펙틴 및 변성 전분은 ‘일반적으로 안전하다고 인정되는(GRAS)’ 지위와 천연 유래를 강조한 브랜딩 전략에 힘입어 시장에서 틈새 역할을 계속해서 확립하고 있습니다.
폴리아크릴아미드가 시장에서 주도적인 위치를 차지하고 있는 것은 기술력뿐만 아니라 중국의 후방 통합형 비용 구조 덕분이기도 합니다. 이러한 구조로 인해 수용성 폴리머 시장 전체에서 해당 부문의 점유율은 크게 확대되었습니다. 한편, 소비자용 포드 시장에서 PVA의 인기가 높아지고 있는 것은 수익원의 다각화를 시사하지만, 공급업체들은 2027년까지 신뢰할 수 있는 생분해성 관련 문서를 작성하여 시장 점유율을 유지해야 하는 시급한 과제에 직면해 있습니다. 구아검의 가격 변동, 특히 인도의 작황 문제를 감안하여, 유전 사용자들은 폴리머 선택의 폭을 넓혀 예측 불가능한 기상 상황으로 인한 공급 차질로부터 이익률을 보호하려 하고 있습니다. 바이오의약품 성장의 물결을 타고 있는 젤라틴 공급업체들은 소해면상뇌증(BSE) 등의 위험에 대한 경계를 늦추지 않고, 엄격한 추적성 조치의 필요성을 강조해야 합니다. 폴리아크릴산 제조업체들은 현재 초저모노머 함유 제품을 추진하고 있으며, 특히 규제 당국의 감시가 강화되는 가운데 위생용품 및 가정용품 시장에서 입지를 다지고 있습니다. 시장이 진화함에 따라 PEG 및 틈새 특수 제품들은 수익성이 더 높은 의약품 및 의료기기 분야에 집중해 나갈 것으로 예측됩니다. 대조적으로, 천연 하이드로콜로이드 제조업체들은 합성 대체품과의 경쟁력을 유지하기 위해 발효 공정의 효율화를 적극적으로 도모하고 있습니다.
지역별 분석
아시아태평양은 2025년에 세계 시장 규모의 50.17%를 차지하며, 2031년까지 연평균 성장률(CAGR) 4.74%로 성장할 전망입니다. 이러한 성장은 중국의 폐수 관리에 대한 막대한 투자와 인도의 종합적인 농촌 용수 공급 이니셔티브에 힘입은 것입니다. 일본, 한국 및 동남아시아 국가 등은 의약품 첨가제의 생산 능력과 폐수 처리 인프라 확충을 통해 수요를 확대되고 있습니다. 수용성 폴리머의 생산과 소비 양면에서 주도적인 역할을 수행하고 있는 만큼, 아시아태평양은 시장에서 지배적인 지위를 공고히 하고 있습니다.
북미에서는 셰일 가스 사업의 안정화와, 석탄 화력 발전소에 대해 첨단 폴리머로의 전환을 강제했던 EPA(미국 환경보호청)의 엄격한 제로 배출 규제에 힘입어 시장 회복세가 나타나고 있습니다. 캐나다는 최전선에 서서 오일샌드 광미 처리를 위한 양성 폴리아크릴아미드 실험을 진행하고 있습니다. 한편, 멕시코는 주요 도시권의 폐수 처리 시스템 개보수에 자금을 투입하고 있습니다. 이러한 다양한 노력은 수용성 폴리머 시장에서 북미의 중요한 위상을 부각시키고 있습니다.
유럽에서는 인을 포함하지 않는 방류수 실현을 위한 노력과 엄격한 미세 플라스틱 규제에 대응하여 제품 라인업 재편이 진행되고 있습니다. 이러한 변화로 인해 시장은 고전하 밀도의 폴리아크릴아미드 및 친환경 대체재로 방향을 전환하고 있습니다. 많은 지자체 처리 시설에서 3차 처리로 업그레이드가 필요함에 따라, 폴리머 수요가 급증할 것으로 예측됩니다. 북유럽 국가들에서는 생분해성 관련 규제로 인해 천연 하이드로콜로이드가 주류를 이루고 있는 반면, 러시아 볼가강 유역의 프로젝트가 동유럽의 성장을 뒷받침하고 있습니다.
남미에서는 브라질의 야심 찬 위생 개선 이니셔티브, 아르헨티나의 실험적인 폴리머 종자 코팅 기술, 그리고 안데스 산맥의 광업 사업이 지역 전체의 소비 확대에 기여하고 있습니다. 중동 및 아프리카에서는 남아프리카공화국의 해수 담수화 능력 확대와 폐수 처리 시설 현대화를 위한 노력이 스케일 방지제 및 응집제 수요를 끌어올리고 있어, 전 세계 수용성 폴리머 시장을 더욱 다각화하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the water-soluble polymer market size is estimated at USD 39.22 billion in 2026, and is expected to reach USD 49.04 billion by 2031, at a CAGR of 4.57% during the forecast period (2026-2031).
This report is Segmented by Type (Polyacrylamide, Polyvinyl Alcohol, Guar Gum, Gelatin, Xanthan Gum, Polyacrylic Acid, Polyethylene Glycol, and Other Types), End-User Industry (Water Treatment, Food and Beverage, Personal Care and Hygiene, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Water-soluble Polymer Market Trends and Insights
Surging Global Municipal and Industrial Wastewater Treatment Investment
In 2025, global spending on wastewater treatment reached significant levels. This surge in investment has driven up the demand for ultra-high-molecular-weight anionic polyacrylamides, known for their ability to reduce sludge volumes and cut disposal costs. By the end of 2025, China implemented nationwide Class 1A effluent limits, leading to increased polyacrylamide consumption. Meanwhile, India's National Mission for Clean Ganga allocated substantial funds for the establishment of new sewage plants. Each of these plants will require polymer flocculants. In the Middle East, newly commissioned desalination projects in 2025 are utilizing polyacrylic acid and polyethylene glycol antiscalants. These are essential for safeguarding membranes in a new capacity. Collectively, these initiatives position municipal and industrial players as leaders in the water-soluble polymer market.
Shale-Gas Polymer Demand Rebound in North America
In 2025, North American operators consumed significant volumes of water-soluble polymers, coinciding with crude prices stabilizing. Partially hydrolyzed polyacrylamide, a key player in polymer flooding, boasts an incremental recovery advantage over traditional waterflooding. Meanwhile, xanthan gum is carving out a larger share in high-salinity reservoirs, bolstered by new U.S. capacity that became operational in 2024-2025. Additionally, federal grants are fueling research into thermally stable, degradable copolymers aimed at mitigating formation damage. Collectively, these developments underscore the oilfield's pivotal role in bolstering the water-soluble polymer market.
Raw-Material Price Volatility
In 2024-2025, acrylonitrile prices fluctuated significantly following propylene disruptions in China. This volatility compressed polyacrylamide margins. Similarly, vinyl acetate monomer prices experienced a notable surge during the same timeframe. Meanwhile, guar gum prices increased sharply as drought conditions in India slashed the harvest. Such fluctuations challenge cost predictability in the water-soluble polymer market.
Other drivers and restraints analyzed in the detailed report include:
- Personal-Care Formulators Accelerating Shift Toward Water-Soluble Rheology Modifiers
- European Union and Asian Phosphorus-Free Discharge Rules Boosting Advanced Polyacrylamides
- Escalating End-of-Life and Toxicity Regulations on Non-Biodegradable Polymers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyacrylamide delivered 24.48% of 2025 revenue and will expand at a 4.75% CAGR to 2031. This growth is largely attributed to newly implemented phosphorous discharge regulations, which favor ultra-high-molecular-weight grades of polyacrylamide. These grades can significantly reduce sludge disposal costs. As a result, polyacrylamide is poised to play a pivotal role in the water-soluble polymer market, especially in treatment chemistries. Meanwhile, PVA films, commonly used in unit-dose detergents, are witnessing strong growth. However, potential restrictions on microplastics present a looming challenge. Guar gum faced challenges due to raw material risks stemming from a crop shortfall in India, leading to a notable shift towards xanthan gum in fracturing fluids. Gelatin continues to dominate the soft-gel capsule market, bolstered by an increase in high-bloom output from contract manufacturing organizations (CMOs) in the Asia-Pacific region. Both polyacrylic acid and sodium polyacrylate are seeing heightened demand in hygiene products and for inhibiting scale in cooling water. This demand surge is further supported by the introduction of new low-residual-monomer grades, which are in line with California's stringent consumer-product regulations. While PEG remains a sought-after ingredient in injectables and cosmetics, it is under increasing scrutiny, prompting research and development to pivot towards bio-based alternatives. Additionally, cellulose ethers, pectin, and modified starches continue to carve out niche roles in the market, bolstered by their Generally Recognized As Safe (GRAS) status and a natural branding approach.
Polyacrylamide's leading position in the market is not just a testament to its technical prowess but also to China's backward-integrated cost structures. These structures have significantly bolstered the segment's share in the broader water-soluble polymer market. While PVA's rising popularity in consumer pods signals a diversification of revenue streams, suppliers face a pressing challenge: to produce credible biodegradation documentation by 2027 to maintain their market volume. The volatility of guar gum, especially in light of India's crop challenges, has prompted oilfield users to broaden their polymer selections, safeguarding their profit margins from unpredictable weather-related supply disruptions. Suppliers of gelatin, riding the wave of growth in biologics, must remain vigilant against risks like bovine spongiform encephalopathy, emphasizing the need for stringent traceability measures. Producers of polyacrylic acid are now promoting ultra-low-monomer variants, solidifying their foothold in hygiene and household markets, especially as regulatory scrutiny intensifies. As the market evolves, PEG and niche specialty types are expected to shift focus towards the more lucrative pharmaceutical and medical-device sectors. In contrast, natural hydrocolloids are actively seeking efficiencies in fermentation processes to stay competitive against synthetic alternatives.
Complete Report Scope:
- By Type
- Polyacrylamide
- Polyvinyl Alcohol
- Guar Gum
- Gelatin
- Xanthan Gum
- Polyacrylic Acid
- Polyethylene Glycol
- Other Types (Cellulose Ethers, Pectin, and Starch)
- By End-User Industry
- Water Treatment
- Food and Beverage
- Personal Care and Hygiene
- Oil and Gas
- Pulp and Paper
- Pharmaceutical
- Other End-user Industries (Agrochemicals)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordic Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 50.17% of global value in 2025 and will advance at a 4.74% CAGR through 2031. This growth is bolstered by substantial investments in wastewater management in China and India's comprehensive rural water initiative. Countries like Japan, South Korea, and various Southeast Asian nations are amplifying demand by enhancing their pharmaceutical excipient capacities and wastewater infrastructures. Given its leading role in both the production and consumption of water-soluble polymers, the Asia-Pacific region solidifies its dominance in the market.
North America is witnessing a resurgence, driven by stabilizing shale-gas activities and the EPA's stringent zero-discharge regulations, which have compelled coal plants to transition to advanced polymers. Canada is at the forefront, experimenting with amphoteric polyacrylamides for oil-sands tailings. Meanwhile, Mexico is channeling funds into upgrading wastewater systems in its major metropolitan areas. These diverse initiatives underscore North America's significant standing in the water-soluble polymer market.
Europe is reshaping its product offerings in response to its push for phosphorus-free effluents and stringent microplastic regulations. This shift is steering the market towards high-charge-density polyacrylamides and eco-friendly alternatives. With numerous municipal plants in need of tertiary upgrades, there's an anticipated demand surge for polymers. While Nordic countries champion natural hydrocolloids due to biodegradability mandates, projects in Russia's Volga Basin are spurring growth in Eastern Europe.
South America is capitalizing on Brazil's ambitious sanitation initiative, Argentina's experimental polymer seed-coating, and mining endeavors in the Andes to boost regional consumption. In the Middle-East and Africa, efforts to expand desalination capacities and modernize wastewater facilities in South Africa are bolstering the demand for scale inhibitors and flocculants, further diversifying the global water-soluble polymer landscape.
- Arkema
- Ashland
- BASF SE
- CP Kelco U.S. Inc.
- Dow
- DuPont
- Evonik Industries
- Gantrade Corporation
- Kemira
- Kuraray Co. Ltd
- LG Chem
- Merck KGaA
- Mitsubishi Chemical Corporation
- Nouryon
- Polysciences Inc.
- SNF Group
- Solvay S.A.
- Sumitomo Seika Chemicals Co. Ltd
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging global municipal and industrial wastewater-treatment investment
- 4.2.2 Shale-gas EOR polymer demand rebound in North America
- 4.2.3 Personal-care formulators accelerating shift toward water-soluble rheology modifiers
- 4.2.4 European Union and Asian phosphorus-free discharge rules boosting advanced polyacrylamides
- 4.2.5 Rapid growth of unit-dose e-commerce packaging using PVA films
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility
- 4.3.2 Escalating end-of-life and toxicity regulations on non-biodegradable polymers
- 4.3.3 Forthcoming micro-plastic limits on soluble/dispersible chemistries
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Polyacrylamide
- 5.1.2 Polyvinyl Alcohol
- 5.1.3 Guar Gum
- 5.1.4 Gelatin
- 5.1.5 Xanthan Gum
- 5.1.6 Polyacrylic Acid
- 5.1.7 Polyethylene Glycol
- 5.1.8 Other Types (Cellulose Ethers, Pectin, and Starch)
- 5.2 By End-User Industry
- 5.2.1 Water Treatment
- 5.2.2 Food and Beverage
- 5.2.3 Personal Care and Hygiene
- 5.2.4 Oil and Gas
- 5.2.5 Pulp and Paper
- 5.2.6 Pharmaceutical
- 5.2.7 Other End-user Industries (Agrochemicals)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Indonesia
- 5.3.1.6 Malaysia
- 5.3.1.7 Thailand
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Nordic Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Arkema
- 6.4.2 Ashland
- 6.4.3 BASF SE
- 6.4.4 CP Kelco U.S. Inc.
- 6.4.5 Dow
- 6.4.6 DuPont
- 6.4.7 Evonik Industries
- 6.4.8 Gantrade Corporation
- 6.4.9 Kemira
- 6.4.10 Kuraray Co. Ltd
- 6.4.11 LG Chem
- 6.4.12 Merck KGaA
- 6.4.13 Mitsubishi Chemical Corporation
- 6.4.14 Nouryon
- 6.4.15 Polysciences Inc.
- 6.4.16 SNF Group
- 6.4.17 Solvay S.A.
- 6.4.18 Sumitomo Seika Chemicals Co. Ltd
- 6.4.19 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


