|
시장보고서
상품코드
2120305
하이엔드 동박 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)High-End Copper Foil - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 하이엔드 동박 시장 규모는 2026년에 11억 6,000만 달러로 추계되고 있으며, 예측 기간(2026-2031년) CAGR 6.38%로 추이하며, 2031년에는 15억 8,000만 달러에 달할 것으로 전망되고 있습니다.
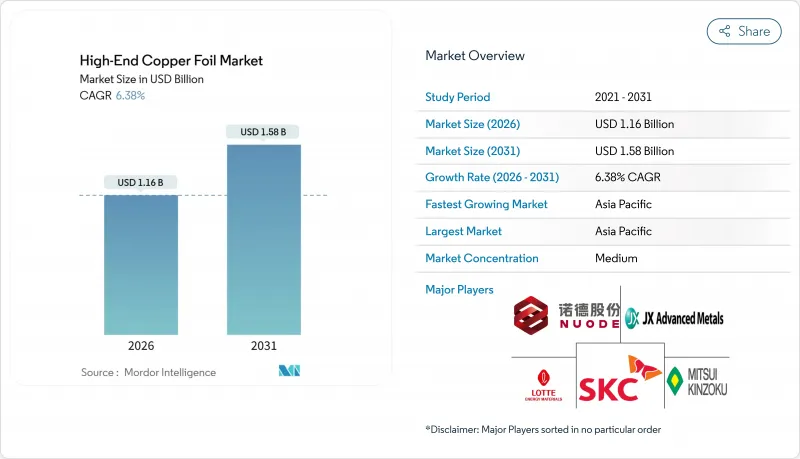
이 보고서는 제품 유형(압연 동박 및 전해 동박), 용도(회로 기판, 배터리, 태양광 및 대체 에너지, 가전, 의료, 기타), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 하이엔드 동박 시장의 동향 및 인사이트
전기자동차(EV) 배터리용 초박형 고순도 박의 수요
박의 두께가 2µm 얇아질 때마다 질량 에너지 밀도가 5-6% 향상되므로, 각 OEM 업체들은 6µm 및 4µm 음극 집전박의 채택을 가속화하고 있습니다. 중국은 2025년에 1,334GWh의 리튬 배터리를 출하하고, 2026년에는 1,622GWh에 달할 전망이지만, 2026년 7월에 시행될 순도 규제로 인해 경쟁력이 낮은 제조업체들은 하이엔드 동박 시장에서 철수할 수밖에 없을 것입니다. 유럽과 미국의 기가팩토리에서는 순도 99.99% 및 신장률 편차 1% 미만을 요구하고 있으며, 이에 따라 수주는 일본 및 한국의 공급업체에 집중되는 경향이 있습니다. 국제에너지기구(IEA)는 2035년까지 1차 구리가 30% 부족할 것이라고 경고하고 있으며, 박판의 수율 관리의 중요성이 더욱 커지고 있습니다. 고품질 전해 도금 등급은 1kg당 22-28달러에 거래되는 반면, 표준 8µm 두께의 동박은 15-18달러로, 6µm 미만의 도금 기술을 확보한 제조사에게는 큰 이익이 발생합니다.
5G/HPC에 따른 고주파 PCB 수요 확대
800G 및 1.6T 이더넷으로 업그레이드하는 하이퍼스케일 데이터센터에서는 유전율 3.5 미만이 요구되므로, 라미네이트 제조업체는 표면 거칠기가 0.4µm 미만인 초저두께 롤 포일을 사용할 수밖에 없습니다. 로저스 코퍼레이션의 RO4000 라미네이트 리드타임은 동박 공급이 부족해짐에 따라 2025년에 16주에서 26주로 연장되었습니다. AI 가속기 보드는 삽입 손실이 1인치당 1dB를 초과하면 경쟁력을 잃게 되므로, 구매자들은 1년 전부터 포일 확보에 나서고 있습니다. IPC-6018D 설계 규칙에서는 현재 밀리파 보드용 압연 포일이 지정되어 있으며, 스팟 프리미엄이 계약 가격보다 15-20% 가산되고 있습니다. 압연기와 라미네이트 라인을 모두 보유한 통합 공급업체가 이러한 가치를 확보하고 있습니다.
구리 가격 변동과 이익률 압박
2025년 10월, 런던 금속 거래소(LME)의 현물 가격은 톤당 1만 1,200달러까지 상승했으며, 2026년 2분기 전망치는 톤당 1만 2,500달러에 육박하고 있습니다. 가격 전가 조항의 적용에는 60-90일의 지연이 발생하므로 이로 인해 박막 제조업체의 EBITDA는 2-3퍼센트 포인트 하락했습니다. 헤지 프로그램이 없는 남아시아의 소규모 제련소는 2025년 3분기에 프리미엄이 톤당 280달러로 확대되었을 때 마이너스 마진을 기록했습니다. 국제에너지기구(IEA)는 2035년까지 구리 공급이 구조적으로 30% 부족할 것으로 예측하고 있으며, 가격 변동은 지속될 전망입니다. 생산자들은 수년 단위의 정광 판매 계약을 체결하고 스크랩 재활용에 투자하고 있지만, 그 혜택을 누릴 수 있는 것은 18-36개월 후가 될 것입니다.
부문별 분석
압연 구리는 2025년 시장 가치의 59.67%를 차지했습니다. 이는 0.35µm 수준의 제곱평균제곱근 거칠기(RMS)와 30-300 GHz 기판에서 표피 효과로 인한 손실을 경감시키는 독보적인 기계적 강도에 힘입은 결과입니다. 전해박은 배터리 제조업체들이 6µmm 및 4µm 두께로 전환하고 있는 추세를 반영하여, 1,350mm 폭 전체에 걸쳐 균일한 두께를 전해 도금으로 구현할 수 있다는 점에 힘입어 연평균 성장률(CAGR) 8.44%로 성장할 것으로 예측됩니다. 다단식 압연기 1대당 자본 집약도는 1억 달러를 초과하며, 이로 인해 초평활 제품에 대해 1kg당 28-35달러를 청구할 수 있는 일본 및 유럽 생산자들에 의한 과점 상태가 촉진되고 있습니다. 한편, 중국의 전해 도금 생산 능력은 2024년까지 연간 60만 톤으로 급증하여, 표준 8µm 등급의 가격 경쟁을 유발하고 있습니다.
전해 도금 공정에서는 두께 5µm 미만에서 높은 처리 능력과 미세 균열 위험 감축이 가능하며, 하이엔드 동박 시장이 고에너지 밀도 배터리로 전환되는 가운데 이는 강점으로 작용하고 있습니다. 한편, 5G 및 AI용 기판 수요로 인해 압연박의 할당량은 12개월 앞까지 사전 예약되는 상황이 되어, 이중 공급망이 형성되고 있습니다. 통합형 압연 동박 제조업체는 라미네이트 사업으로 상류 통합을 추진하고 있는 반면, 전해 도금 전문 제조업체는 기가팩토리 근처에 거점을 두고 적시 납품을 실현하고 있습니다. 이러한 상이한 비즈니스 모델은 하이엔드 동박 시장이 얼마나 양극화를 지속하고 있는지를 보여줍니다.
지역별 분석
아시아태평양은 2025년 매출의 69.60%를 차지하며, 중국의 막대한 생산 점유율과 한국의 6µm 미만의 기술력에 힘입어 2031년까지 연평균 성장률(CAGR) 6.72%를 기록할 것으로 예측됩니다. 중국이 2026년 7월에 도입한 GB 규격에 따라 기술적 업그레이드나 시장 철수가 요구되고 있으며, 일반 상품 생산자들은 압박을 받는 반면 프리미엄 가격 실현이 지원되고 있습니다. 한국의 SKC, Solus Advanced Materials, LS MTRON은 EU 및 ASEAN의 기가팩토리를 위해 폴란드와 말레이시아에서 생산 능력을 확대하고 있는 반면, 일본 기업은 고순도 및 압연이라는 틈새 분야에서 품질을 최우선으로 하고 있습니다.
북미와 유럽은 현지 생산으로의 전환을 추진하고 있습니다. ‘인플레이션 감축법(Inflation Reduction Act)’이 기가팩토리 투자를 지원하는 가운데, 북미의 하이엔드 동박 시장 규모는 확대될 전망입니다. 그러나 2025년 현재 해당 지역의 전해 동박 생산 능력은 연간 1만 8,000톤에 그치고 있으며, 멕시코와 헝가리의 신규 생산 라인이 가동되기 전까지는 12-15%의 비용 프리미엄을 감수하고 수입할 수밖에 없는 상황입니다. 유럽의 배터리 규제에는 재활용 함유율 의무화가 포함되어 있으며, 이는 동일 부지내 재활용을 촉진하는 것으로, 레드우드 매트리얼즈와 유미코아의 투자를 유치하고 있습니다.
남미, 중동 및 아프리카는 여전히 수입에 의존하고 있습니다. 브라질에서는 소비자 가전를 위해 연간 약 1만 톤의 동박을 수입하고 있는 반면, 사우디아라비아의 ‘비전 2030’은 고주파 라미네이트가 필요한 데이터센터 건설을 촉진하고 있습니다. 남아프리카의 광업 기반에서 정광이 공급되고 있지만, 해당 지역에는 동박 제조 능력이 부족하여, 남부 아프리카에 배터리 클러스터가 형성된다면 향후 반제품을 수출하는 모델이 확립될 가능성이 시사되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.02According to Mordor Intelligence, the high-End copper foil market size is estimated at USD 1.16 billion in 2026, and is expected to reach USD 1.58 billion by 2031, at a CAGR of 6.38% during the forecast period (2026-2031).
This report is Segmented by Product Type (Rolled Copper Foil and Electrodeposited Copper Foil), Application (Circuit Boards, Batteries, Solar and Alternative Energy, Appliances, Medical, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global High-End Copper Foil Market Trends and Insights
EV Battery Demand for Ultra-Thin High-Purity Foils
Every 2 µm reduction in foil thickness lifts gravimetric energy density by 5-6%, spurring OEMs to adopt 6 µm and 4 µm anode collectors. China shipped 1,334 GWh of lithium batteries in 2025 and is on track for 1,622 GWh in 2026, but July 2026 purity mandates will push marginal mills out of the high-end copper foil market. Western gigafactories demand 99.99% purity and sub-1% elongation variance, tilting awards toward Japanese and Korean suppliers. The International Energy Agency warns of a 30% primary-copper shortfall by 2035, intensifying the importance of thin-foil yield management. Premium electrodeposited grades command USD 22-28 per kg versus USD 15-18 for standard 8 µm foils, rewarding mills that master sub-6 µm deposition.
5G / HPC Push for High-Frequency PCBs
Hyperscale data centers upgrading to 800G and 1.6T Ethernet require dielectric constants below 3.5, forcing laminate makers to use ultra-low-profile rolled foils with surface roughness under 0.4 µm. Rogers Corporation's RO4000 laminate lead times lengthened from 16 to 26 weeks in 2025 because copper-foil supply was constrained. AI accelerator boards lose competitiveness when insertion loss exceeds 1 dB per inch, encouraging buyers to secure foil allocations a year in advance. IPC-6018D design rules now carve out rolled foil for mmWave boards, lifting spot premiums 15-20% above contracts. Integrated suppliers that own both rolling mills and laminate lines capture the value.
Copper Price Volatility and Margin Squeeze
London Metal Exchange spot rose to USD 11,200/t in October 2025, with Q2 2026 forecasts near USD 12,500/t, slashing foil-maker EBITDA by 2-3 percentage points because pass-through clauses lag 60-90 days. Smaller South Asian mills lacking hedge programs posted negative margins in Q3 2025 when premiums widened to USD 280/t. The IEA foresees a structural 30% copper supply deficit by 2035, preserving volatility. Producers are locking multi-year concentrate offtakes and investing in scrap recycling, but benefits accrue only after 18-36 months.
Other drivers and restraints analyzed in the detailed report include:
- Regional Gigafactory Localisation Wave
- Closed-Loop Battery-Grade Foil Recycling Initiatives
- Chinese Over-Capacity-Led Price Wars in Li-Battery Foil
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rolled copper accounted for 59.67% of 2025 value, supported by root-mean-square roughness near 0.35 µm and unrivaled mechanical strength that mitigates skin-effect losses on 30-300 GHz boards. Electrodeposited foil is projected to grow at 8.44% CAGR, driven by battery makers migrating toward 6 µm and 4 µm gauges that electrodeposition can deliver uniformly across 1,350 mm widths. Capital intensity runs above USD 100 million per multi-stage rolling mill, fostering an oligopoly among Japanese and European producers who can charge USD 28-35 / kg for ultra-smooth variants. Conversely, Chinese electrodeposition capacity surged to 600,000 tpa by 2024, sparking price wars in standard 8 µm grades.
Electrodeposited processes allow higher throughput and lower micro-crack risk below 5 µm thickness, an edge as the high-end copper foil market pivots to energy-dense cells. Meanwhile, 5G and AI boards drive pre-booking of rolled-foil allocations 12 months ahead, creating dual supply chains. Integrated rolled-foil mills are forward-integrating into laminates, while electrodeposited specialists co-locate near gigafactories to offer just-in-time delivery. These divergent models illustrate how the high-end copper foil market continues to bifurcate.
Complete Report Scope:
- By Product Type
- Rolled Copper Foil
- Electrodeposited (ED) Copper Foil
- By Application
- Circuit Boards
- Batteries
- Solar and Alternative Energy
- Appliances
- Medical
- Others
- By Geography
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 69.60% of 2025 revenue and is forecast at a 6.72% CAGR through 2031, bolstered by China's large production share and South Korea's sub-6 µm expertise. China's July 2026 GB standard is forcing technical upgrades or exits, squeezing commodity producers but supporting premium price realization. South Korea's SKC, Solus Advanced Materials, and LS MTRON are scaling capacity in Poland and Malaysia to serve EU and ASEAN gigafactories, while Japanese players prioritize quality in high-purity and rolled niches.
North America and Europe are pivoting toward localization. The high-end copper foil market size for North America is set to expand as the Inflation Reduction Act primes gigafactory investment. Yet only 18,000 tpa of regional electrodeposited capacity existed in 2025, necessitating imports at 12-15% cost premiums until greenfield lines in Mexico and Hungary come online. Europe's Battery Regulation layers recycled-content mandates that favor co-located recycling, attracting investments from Redwood Materials and Umicore.
South America, the Middle East, and Africa remain import-dependent. Brazil buys about 10,000 t of copper foil yearly for consumer electronics, while Saudi Arabia's Vision 2030 stimulates data-center builds that demand high-frequency laminates. South Africa's mining base offers concentrates, but the region lacks foil fabrication, hinting at future semi-finished export models if Southern African battery clusters emerge.
- Chang Chun Petrochemical Co. Ltd
- Co-Tech Development Corporation
- Doosan Corporation Electro-Materials.
- FUKUDA METAL FOIL & POWDER CO., LTD.
- Furukawa Electric Co., Ltd
- JX Advanced Metals Corporation
- Kingboard Holdings
- Londian Wason (Shenzhen) Holdings Group Co., Ltd.
- Lotte Energy Materials
- LS MTRON LTD.
- Mitsui Kinzoku Co., Ltd.
- NAN YA PLASTICS CORPORATION
- Nuode New Materials Co Ltd
- SKC
- Solus Advanced Materials
- Sumitomo Metal Mining Co., Ltd.
- Targray Technology International
- UACJ Foil Corporation
- Wieland
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV Battery Demand for Ultra-Thin High-Purity Foils
- 4.2.2 5G / HPC Push for High-Frequency PCBs
- 4.2.3 Regional Gigafactory Localisation Wave (North America and European Union)
- 4.2.4 Closed-Loop Battery-Grade Foil Recycling Initiatives
- 4.2.5 Tight Supply of HF PCB Substrates Drives Premium Foil Demand
- 4.3 Market Restraints
- 4.3.1 Copper Price Volatility and Margin Squeeze
- 4.3.2 Chinese Over-Capacity-Led Price Wars in Li-Battery Foil
- 4.3.3 Sodium-Ion Shift (Al Current Collectors) Cannibalises Copper
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts(Value)
- 5.1 By Product Type
- 5.1.1 Rolled Copper Foil
- 5.1.2 Electrodeposited (ED) Copper Foil
- 5.2 By Application
- 5.2.1 Circuit Boards
- 5.2.2 Batteries
- 5.2.3 Solar and Alternative Energy
- 5.2.4 Appliances
- 5.2.5 Medical
- 5.2.6 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 Japan
- 5.3.1.3 South Korea
- 5.3.1.4 India
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 NORDIC Countries
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Chang Chun Petrochemical Co. Ltd
- 6.4.2 Co-Tech Development Corporation
- 6.4.3 Doosan Corporation Electro-Materials.
- 6.4.4 FUKUDA METAL FOIL & POWDER CO., LTD.
- 6.4.5 Furukawa Electric Co., Ltd
- 6.4.6 JX Advanced Metals Corporation
- 6.4.7 Kingboard Holdings
- 6.4.8 Londian Wason (Shenzhen) Holdings Group Co., Ltd.
- 6.4.9 Lotte Energy Materials
- 6.4.10 LS MTRON LTD.
- 6.4.11 Mitsui Kinzoku Co., Ltd.
- 6.4.12 NAN YA PLASTICS CORPORATION
- 6.4.13 Nuode New Materials Co Ltd
- 6.4.14 SKC
- 6.4.15 Solus Advanced Materials
- 6.4.16 Sumitomo Metal Mining Co., Ltd.
- 6.4.17 Targray Technology International
- 6.4.18 UACJ Foil Corporation
- 6.4.19 Wieland
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment