

|
시장보고서
상품코드
2120501
의약품 첨가제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Pharmaceutical Excipients - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
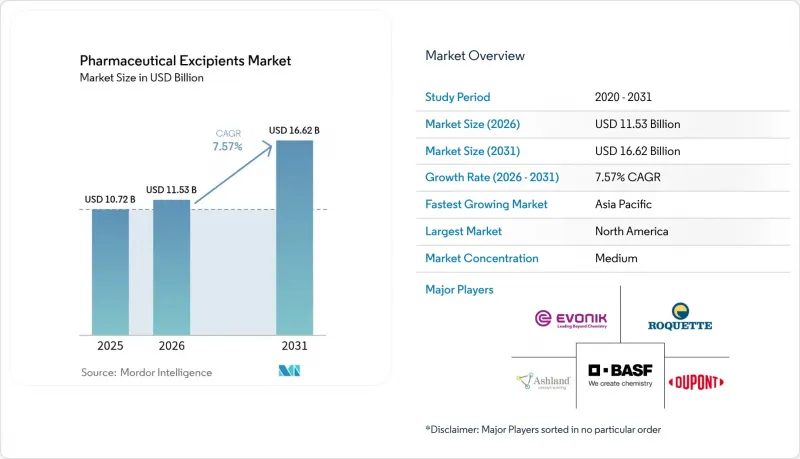
에 의하면, 의약품 첨가제 시장 규모는 2025년 107억 2,000만 달러로 평가되었습니다. 2026년에는 115억 3,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 7.57%로 성장을 지속하여, 2031년에는 166억 2,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 제품별(유기 화학 물질 및 무기 화학 물질), 기능별(충전제·희석제 등), 제형별(경구 고형 제제 등), 원료별(식물 유래 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의약품 첨가제 시장 동향 및 인사이트
고효능 API를 위한 다기능 신규 첨가제의 부상
고효능 항암제나 면역학 분야의 의약품을 다루는 제제 개발자들은 현재 결합, 분해, 유동성 향상 역할을 하나의 재료로 겸비한 부형제를 찾고 있습니다. 공동 처리 플랫폼은 단위 공정을 줄이고, 분진 노출을 감소시키며, 균일한 함량을 실현하기 때문에 연속 생산 라인에서 매력적입니다. 안전성 데이터가 복합적인 기능을 포괄해야 하기 때문에 규제 관련 문서 작성은 여전히 과제로 남아 있으며, 이로 인해 승인 주기가 장기화되고 있습니다. 북미의 혁신 기업들이 초기 노하우를 보유하고 있지만, 유럽 제조업체들도 수요를 확보하기 위해 파일럿 플랜트를 급속히 확장하고 있습니다. 중기적으로는 개발 중인 분자의 유효성 임계값 상승으로 인해 다기능 등급이 구매 결정의 핵심 요소로 남아 있을 것입니다.
바이오시밀러 확대를 뒷받침하는 바이오의약품 부형제 수요 급증
단일클론 항체의 특허 만료에 따른 바이오시밀러 출시로 인해, 제조 공정에서 단백질 구조를 보호하는 고순도 당류, 아미노산, 계면활성제에 대한 전 세계적 수요가 증가하고 있습니다. 공급업체들은 서로 다른 조성이라도 생물학적 동등성을 입증하면서, 참조 생물학적 제제프로파일에 부합하도록 안정제를 공동 개발하는 경우가 많습니다. 가정용 자동 주사기용 액상 제제의 경우, 안정성에 대한 요구가 더욱 높아지고 있어 엔도톡신 및 응집물이 적은 첨가제가 필수적입니다. 다중 컬럼 크로마토그래피 및 무균 여과로 인해 공정이 복잡해지면서 비용은 여전히 높은 수준을 유지하고 있지만, 아시아태평양의 대규모 생산 능력 확대로 인해 가격 차이는 점차 줄어들고 있습니다. 생산량 확대에 따라 엄격한 미생물 규격을 유지할 수 있는지 여부가 장기적인 성장의 열쇠가 될 것입니다.
지역 간 규제 차이로 인해 전 세계적인 출시 조화가 저해되고 있습니다.
FDA, EMA, 그리고 인도, 브라질, 중국의 규제 당국 간에 신청 서류 양식이나 첨가제 기재 규칙이 다르기 때문에 개발 기간이 장기화되고 있습니다. 국제조화회의(ICH)는 계속해서 Q14 및 Q2(R2) 가이드라인 초안 작성을 진행하고 있지만, 특히 다기능성 물질의 경우 위험 평가 접근 방식에 차이가 보입니다. 각 기업은 지역별로 마스터 파일을 유지하고 있으며, 이로 인해 관리상의 부담이 증가하고 전 세계적인 사업 확장이 지연되고 있습니다. 이러한 차이는 전담 규제 대응 팀을 갖추지 못한 중소규모의 혁신 기업에게 특히 큰 부담이 되고 있습니다. 조화 작업의 진전은 여전히 더딘 편이며, 이러한 제약은 향후 10년 동안도 지속될 것으로 보입니다.
부문 분석
2025년, 의약품 부형제 시장 점유율의 74.97%를 유기 화학 물질이 차지했으며, 정제 제조의 효율화 측면에서 셀룰로오스, 유당 및 전분 유도체에 대한 의존이 지속되고 있음이 부각되었습니다. 셀룰로오스계 소재는 ‘클린 라벨’에 대한 선호와 부합하며, 약전에 의한 강력한 뒷받침도 유지되고 있기 때문에 유기 카테고리와 관련된 의약품 부형제 시장 규모는 꾸준히 확대되고 있습니다. 연속 제조 기술의 보급으로 인해 전단력이나 습도 변동에 견딜 수 있도록 설계된 폴리머 등급에 대한 수요가 더욱 높아지고 있습니다. 대조적으로, 염화나트륨 및 염화칼륨과 같은 무기 할로겐화물은 삼투압 펌프 및 서방형 코어에서의 역할로 인해 2031년까지 연평균 성장률(CAGR)이 7.41%로 가장 높은 성장세를 보이고 있습니다. 이러한 광물성 염은 특수 제형에서 고함량 활성 성분(API)에 필수적인 안정적인 이온 강도 프로파일을 제공합니다.
혁신을 통해 카테고리를 초월한 시너지 효과가 발생하고 있습니다. 지방산 유래의 오일 케미컬은 낮은 면역원성뿐만 아니라 윤활성이라는 장점도 겸비하고 있어, 비경구 투여와 경구 투여를 연결하는 가교 역할을 하고 있습니다. 단백질 유래 안정제는 취급량이 적을 뿐만 아니라, 바이오의약품의 응집을 방지하기 위해 고가대로 거래되고 있습니다. 제제 개발자들은 용매 잔류물의 관점에서 석유화학제품을 면밀히 검토하고 있으며, 동등한 유동 특성을 지닌 바이오 유래 대체품으로의 전환이 진행되고 있습니다. 연속 생산 라인이 보급됨에 따라 입도 분포(PSD)가 엄격하게 관리되고, 내독소 함량이 낮은 첨가제가 조달 목록의 주류를 이루게 될 것입니다.
2025년, 충진제는 의약품 부형제 시장에서 32.12%의 점유율을 유지했습니다. 이는 목표하는 정제 중량 및 기계적 강도를 달성하는 데 있어 충진제가 필수적인 역할을 하고 있음을 반영합니다. 유당 일수화물 및 미결정 셀룰로오스는 여전히 표준적인 선택지이지만, 습기에 대한 민감성이 문제가 되는 분야에서는 DMF 등급의 만니톨과 이소말토가 주목받고 있습니다. 서방형 치료법의 부상과 함께 지속 방출성 폴리머에 대한 수요가 증가하고 있으며, 2031년까지 연평균 성장률(CAGR) 7.12%를 나타낼 것으로 예측됩니다. 이는 환자 중심의 복약 순응도 목표가 중요시되고 있음을 나타냅니다. 이러한 친수성 매트릭스는 혈장 내 최고 농도를 완화하여 만성 질환의 치료 계획을 지원합니다.
이축 스크류식 습식 과립화를 위해 설계된 결합제는 높은 전단력 하에서도 일관된 점도를 유지하여 연속 처리 사양을 충족합니다. 초분해제는 단순한 팽윤제에서 속용성 제제의 중요한 성능 결정 요인으로 진화하고 있습니다. 한편, 코팅은 기본적인 보호막에서 장용성, 맛 마스킹, 브랜드 차별화를 제공하는 다기능 층으로 진화하고 있습니다. 공동 처리된 부형제는 결합과 분해 기능을 융합함으로써 기능의 경계를 모호하게 하고, 부품 목록을 단순화하는 동시에 규제상의 변경 관리를 용이하게 합니다.
지역별 분석
북미는 2025년 의약품 부형제 시장에서 36.88%의 점유율을 유지했습니다. 이는 혁신적인 기업의 밀집, 엄격한 규제 감독, 그리고 연속 공정의 조기 도입에 힘입은 결과입니다. 공급업체들은 생물학적 제제에 사용되는 주사제 등급의 폴리솔베이트, 사이클로덱스트린 및 맞춤형 셀룰로오스에서 높은 이익률을 확보하고 있습니다. 시장을 선도하고 있음에도 불구하고, 제조업체들은 최근공급 충격으로 드러난 물류상의 취약성에 직면해 있으며, 이에 따라 비상 시 조달 대책이 추진되고 있습니다.
아시아태평양은 인도의 제제 아웃소싱 급증과 중국의 국내 바이오의약품 생산 라인 확대를 견인력으로 삼아 2031년까지 연평균 성장률(CAGR) 6.18%를 나타낼 것으로 예측됩니다. 하이데라바드와 쑤저우의 위탁 개발·제조 기관(CDMO)은 세계 품질 기준에 따라 현지에서 부형제를 공급하도록 의무화하는 다국적 기업과의 계약을 수주하고 있습니다. 분무 건조 만니톨, HPMC, 폴록사머 제조 공장에 대한 투자가 이 지역의 자립을 뒷받침하고 있습니다. 동시에 각국 정부는 규정 준수 향상을 위한 인센티브를 마련하여, 오랫동안 지속되어 온 품질 격차 해소를 도모하고 있습니다.
유럽은 성숙해 가면서도 혁신적인 시장으로, 클린 라벨 정책과 생분해성 폴리머 연구를 선도하고 있으며, 그 영향은 세계 표준에도 파급되고 있습니다. 규제의 명확화로 인해 식물 유래 운반체와 비석유화학계 윤활제의 신속한 보급이 가능해졌습니다. 라틴아메리카, 중동 및 아프리카에서는 각국의 약전이 수입 규제를 강화함에 따라 수요가 서서히 증가하고 있으며, 전분이나 인산칼슘의 현지 생산 사업이 촉진되고 있습니다. 환율 리스크 완화와 리드타임 단축으로 인해 국내 조달의 매력이 높아지면서, 무역 흐름이 서서히 재편되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the pharmaceutical excipients market size is expected to grow from USD 10.72 billion in 2025 to USD 11.53 billion in 2026 and is forecast to reach USD 16.62 billion by 2031 at 7.57% CAGR over 2026-2031.
This report is Segmented by Product (Organic Chemicals and Inorganic Chemicals), Functionality (Fillers & Diluents, and More), Formulation (Oral Solid Dosage Forms, and More), Source (Plant-Based, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Pharmaceutical Excipients Market Trends and Insights
Rise of Multifunctional Novel Excipients for High-Potency APIs
Formulators working with potent oncology and immunology drugs now demand excipients that combine binding, disintegration, and flow-enhancing roles in one material. Co-processed platforms reduce unit operations, lower dust exposure, and deliver uniform content, making them attractive for continuous lines. Regulatory dossiers remain challenging because safety data must cover combined functionalities, which lengthens approval cycles. North American innovators hold early know-how, yet European manufacturers are rapidly scaling pilot plants to capture demand. Over the medium term, rising potency thresholds in pipeline molecules will keep multifunctional grades at the center of purchasing decisions.
Surging Demand for Biopharmaceutical Excipients Supporting Biosimilars Expansion
Biosimilar launches following monoclonal antibody patent cliffs have lifted global requirements for high-purity sugars, amino acids, and surfactants that guard protein structure during processing. Suppliers often co-develop stabilizers to match reference biologics' profiles while demonstrating bioequivalence with different compositions. Liquid formulations for at-home autoinjectors further magnify stability demands, making low-endotoxin and low-aggregate excipients critical. Costs remain high because multi-column chromatography and aseptic filtration add complexity, yet large-scale capacity in Asia-Pacific is narrowing price gaps. Long-term growth hinges on maintaining stringent microbial specs as volumes ramp.
Regulatory Variability Across Regions Limiting Global Launch Harmonization
Differing dossier formats and excipient listing rules among the FDA, EMA, and regulators in India, Brazil, and China prolong development timelines. The International Council for Harmonisation continues to draft Q14 and Q2(R2) guidelines, yet risk-assessment philosophies vary, especially for multifunctional materials. Companies maintain region-specific master files, inflating administrative overhead and delaying worldwide rollouts. Variability is especially burdensome for small and midsize innovators that lack dedicated regulatory teams. Harmonization progress remains slow, suggesting the restraint will linger into the next decade.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Orally Disintegrating Tablets Driving Superdisintegrants Consumption
- Shift Toward Continuous Manufacturing Requiring Polymer-Based Processing Aids
- Toxicological Concerns Over Residual Solvents in Petrochemical Excipients
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Organic chemicals made up 74.97% of pharmaceutical excipients market share in 2025, underscoring continued reliance on cellulose, lactose, and starch derivatives for tableting efficiency. The pharmaceutical excipients market size linked to organic categories is expanding steadily because cellulosics match clean-label preferences and retain robust compendial support. Continuous manufacturing further elevates demand for polymer grades engineered to withstand shear and moisture variability. In contrast, inorganic halites such as sodium chloride and potassium chloride display the quickest 7.41% CAGR through 2031, owing to their role in osmotic pumps and modified-release cores. These mineral salts offer stable ionic strength profiles critical for high-load APIs in specialized dosage forms.
Innovation is creating cross-category synergies: oleochemicals derived from fatty acids bridge parenteral and oral use by offering low immunogenicity alongside lubricity advantages. Protein-based stabilizers, though smaller by volume, command premium pricing because they avert aggregation in biologics. Formulators scrutinize petrochemicals for solvent residues, nudging them toward bio-based analogs with equivalent flow properties. As continuous lines proliferate, excipients with tight PSD controls and low endotoxin profiles will dominate procurement lists.
Fillers retained 32.12% share of the pharmaceutical excipients market in 2025, reflective of their indispensable role in achieving target tablet weights and mechanical strength. Lactose monohydrate and microcrystalline cellulose remain default options, yet DMF-graded mannitol and isomalt gain traction where moisture sensitivity persists. The rise of controlled-release therapies elevates sustained-release polymers, which are forecast to grow at 7.12% CAGR to 2031, highlighting patient-centric adherence objectives. These hydrophilic matrices moderate plasma peaks, supporting chronic disease regimens.
Binders designed for twin-screw wet granulation deliver consistent viscosity under elevated shear, meeting continuous-processing specs. Superdisintegrants graduate from simple swelling agents to critical performance determinants in fast-dissolve formats. Meanwhile, coatings evolve from basic protective films to multifunctional layers providing enteric resistance, taste masking, and brand differentiation. Co-processed excipients blur functionality boundaries by merging binding and disintegration, simplifying bill-of-materials while easing regulatory change control.
Complete Report Scope:
- By Product
- Organic Chemicals
- Carbohydrates
- Petrochemicals
- Oleochemicals
- Proteins
- Other Organic Chemicals
- Inorganic Chemicals
- Halites
- Metal Oxides
- Silicates
- Other Inorganic Chemicals
- Organic Chemicals
- By Functionality
- Fillers & Diluents
- Binders
- Suspension and Viscosity Agents
- Coatings (Film & Enteric)
- Flavoring Agents
- Disintegrants
- Colorants
- Preservatives
- Other Functionalities
- By Formulation
- Oral Solid Dosage Forms
- Parenteral Formulations
- Topical & Transdermal
- Pulmonary/Inhalation
- Ophthalmic
- Others (Sublingual, Buccal, etc.)
- By Source
- Plant-based
- Animal-based
- Synthetic
- Mineral-based
- Marine-based
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America maintained 36.88% share of the pharmaceutical excipients market in 2025, boosted by a dense cluster of innovators, rigorous regulatory oversight, and early adoption of continuous processing. Suppliers capture premium margins on parenteral-grade polysorbates, cyclodextrins, and tailored celluloses used in biologics. Despite leadership, manufacturers face logistics vulnerabilities highlighted by recent supply shocks, prompting contingency sourcing initiatives.
Asia-Pacific is forecast to log a 6.18% CAGR through 2031, spearheaded by India's formulation outsourcing surge and China's scale-up of domestic biologic lines. Contract development and manufacturing organizations in Hyderabad and Suzhou secure multinational contracts that mandate local excipient supply under global quality standards. Investments in spray-dried mannitol, HPMC, and poloxamer plants support regional autonomy. Simultaneously, governments direct incentives toward compliance upgrades, closing historical quality gaps.
Europe represents a mature yet innovative territory, pioneering clean-label policies and biodegradable polymer research that ripple through global standards. Regulatory clarity enables swift uptake of plant-derived carriers and non-petrochemical lubricants. Latin America and the Middle East & Africa show incremental demand as national pharmacopeias toughen import regulations, catalyzing local production ventures for starches and calcium phosphates. Currency-risk mitigation and shorter lead times make domestic sourcing attractive, gradually reshaping trade flows.
- BASF
- Ashland Global
- DuPont
- Roquette Freres SA
- Evonik Industries
- Archer Daniels Midland Co.
- Kerry Group plc
- Lubrizol
- Air Liquide SA
- Croda International plc
- Innophos Holdings Inc.
- Colorcon
- DFE Pharma GmbH & Co. KG
- JRS Pharma GmbH & Co. KG
- Eastman Chemical Company
- International Flavors & Fragrances
- Merck
- Dow Inc.
- Gattefosse SA
- Shin-Etsu Chemical Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise of Multifunctional Novel Excipients for High-Potency APIs
- 4.2.2 Surging Demand for Biopharmaceutical Excipients Supporting Biosimilars Expansion
- 4.2.3 Growth in Orally Disintegrating Tablets Driving Superdisintegrants Consumption
- 4.2.4 Shift Toward Continuous Manufacturing Requiring Polymer-Based Processing Aids
- 4.2.5 Regional Relocation of Formulation Outsourcing to India Favors Local Excipient Suppliers
- 4.2.6 Preference for Plant-Derived Excipients to Meet Clean-Label Requirements
- 4.3 Market Restraints
- 4.3.1 Regulatory Variability Across Regions Limiting Global Launch Harmonization
- 4.3.2 High Purity Requirements Escalating Production Costs for Novel Grades
- 4.3.3 Supply-Chain Exposure to Agricultural Commodity Price Volatility (e.g., Sorbitol)
- 4.3.4 Toxicological Concerns Over Residual Solvents in Petrochemical Excipients
- 4.4 Regulatory Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Organic Chemicals
- 5.1.1.1 Carbohydrates
- 5.1.1.2 Petrochemicals
- 5.1.1.3 Oleochemicals
- 5.1.1.4 Proteins
- 5.1.1.5 Other Organic Chemicals
- 5.1.2 Inorganic Chemicals
- 5.1.2.1 Halites
- 5.1.2.2 Metal Oxides
- 5.1.2.3 Silicates
- 5.1.2.4 Other Inorganic Chemicals
- 5.1.1 Organic Chemicals
- 5.2 By Functionality
- 5.2.1 Fillers & Diluents
- 5.2.2 Binders
- 5.2.3 Suspension and Viscosity Agents
- 5.2.4 Coatings (Film & Enteric)
- 5.2.5 Flavoring Agents
- 5.2.6 Disintegrants
- 5.2.7 Colorants
- 5.2.8 Preservatives
- 5.2.9 Other Functionalities
- 5.3 By Formulation
- 5.3.1 Oral Solid Dosage Forms
- 5.3.2 Parenteral Formulations
- 5.3.3 Topical & Transdermal
- 5.3.4 Pulmonary/Inhalation
- 5.3.5 Ophthalmic
- 5.3.6 Others (Sublingual, Buccal, etc.)
- 5.4 By Source
- 5.4.1 Plant-based
- 5.4.2 Animal-based
- 5.4.3 Synthetic
- 5.4.4 Mineral-based
- 5.4.5 Marine-based
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 BASF SE
- 6.3.2 Ashland Global Holdings Inc.
- 6.3.3 DuPont de Nemours Inc.
- 6.3.4 Roquette Freres SA
- 6.3.5 Evonik Industries AG
- 6.3.6 Archer Daniels Midland Co.
- 6.3.7 Kerry Group plc
- 6.3.8 The Lubrizol Corporation
- 6.3.9 Air Liquide SA
- 6.3.10 Croda International plc
- 6.3.11 Innophos Holdings Inc.
- 6.3.12 Colorcon Inc.
- 6.3.13 DFE Pharma GmbH & Co. KG
- 6.3.14 JRS Pharma GmbH & Co. KG
- 6.3.15 Eastman Chemical Company
- 6.3.16 International Flavors & Fragrances
- 6.3.17 Merck KGaA
- 6.3.18 Dow Inc.
- 6.3.19 Gattefosse SA
- 6.3.20 Shin-Etsu Chemical Co. Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


