

|
시장보고서
상품코드
2120525
태아 및 신생아 모니터링 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Fetal And Neonatal Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
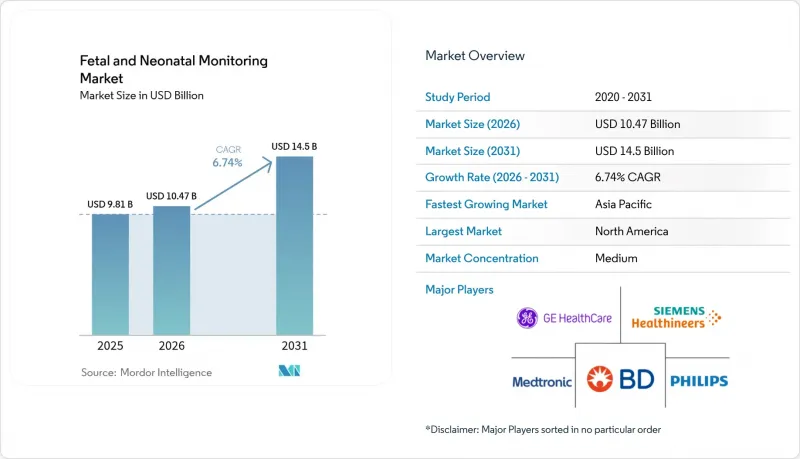
에 의하면, 태아 및 신생아 모니터링 시장 규모는 2025년에 98억 1,000만 달러로 평가되었습니다. 2026년에 104억 7,000만 달러에 달하고, 2031년까지 145억 달러에 이를 것으로 예측되며, 2026-2031년에 걸쳐 CAGR 6.74%로 성장할 전망입니다.
본 보고서는 제품별(태아 모니터링 장치, 신생아 모니터링 장치), 방법별(침습적, 비침습적), 휴대성별(휴대형, 비휴대형), 최종 사용자별(병원, 신생아 케어 센터, 재택치료, 기타),지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 태아 및 신생아 모니터링 시장 동향 및 인사이트
조산 및 저체중아 출생 건수 증가
2024년, 미국의 조산율은 10.41%로 상승했습니다. 이에 대응하여 병원에서는 분만실에 연속 전자 태아 모니터링 시스템을 도입하고, 레벨 III 신생아 중환자실(NICU)에는 심박수, 산소 포화도, 경피 이산화탄소 농도를 추적하는 다중 매개변수 측정 장치를 도입하고 있습니다. 또한, 가정에서 관리되는 고위험 임신을 위한 무선 도플러 패치에 대한 수요도 증가하고 있습니다. 이 부문은 미국의 영구적인 원격의료 규정에 의해 가능해졌습니다. ISO 80601-2-85를 준수하는 휴대용 모니터는 전력 공급이 불안정한 아프리카 및 남아시아의 농촌 지역에서 여전히 필수적인 존재입니다. 이러한 동향들이 맞물려 판매 대수 증가율이 인구 증가율을 상회하고 있으며, 출산율이 낮은 경제권에서도 태아 및 신생아 모니터링 시장은 견조한 추세를 보이고 있습니다.
신흥국의 정부 산전·산후 관리 정책
2020년부터 2025년에 걸쳐 인도의 ‘자나니 수라크샤 요자나(Janani Suraksha Yojana)’는 3,000만 명의 산모에게 현금 지원을 제공하며, 태아 모니터가 구비된 인증 시설에서의 출산을 장려했습니다. 중국에서는 각 성이 ‘세 자녀 정책’의 일환으로, 2024년에 NICU(신생아 집중 치료실) 설비 갱신에 20억 위안(2억 8,000만 달러) 이상을 배정했습니다. 에티오피아에서는 500곳의 보건소에 휴대용 도플러 장비를 도입한 결과, 2년 동안 사산율이 18% 감소했습니다. 이러한 정책은 저비용의 비침습적 의료기기에 초점을 맞추고 있어, 외용 도플러 및 휴대용 초음파 장비의 판매를 가속화하고 있습니다. 많은 정부 부처가 국내 임상시험을 생략하고 FDA 또는 CE 승인을 그대로 수용하는 등 규제 승인이 신속해짐에 따라, 공급업체 시장 진입 기간이 9개월 이하로 단축되었고, 태아 및 신생아 모니터링 시장의 지리적 범위가 확대되고 있습니다.
저·중소득 국가(LMIC) 지방 지역 의료시설에서의 의료기기 이용 가능성 제한
2024년 세계은행의 조사에 따르면, 케냐, 탄자니아, 우간다의 1차 의료 센터 중 43%가 하루 4시간 이상의 정전에 직면하고 있어, 전원에 의존하는 CTG 도입을 저해하고 있습니다. 열대 기후에서는 소모품의 열화율이 15%를 초과하여 1회당 사용 비용을 상승시키고 있습니다. 그 결과, 300달러 이하의 휴대용 도플러가 주류를 이루고 있지만, 품질 감사에 필요한 연속 파형 기능을 갖추고 있지 않습니다. 사산율은 여전히 높은 수준을 유지하고 있으며(사하라 이남 아프리카의 경우 1,000명당 21명), 하드웨어만으로는 인력과 인프라의 부족을 보완할 수 없습니다는 점이 부각되고 있습니다. 이러한 요인들이 복합적으로 작용하여 태아 및 신생아 모니터링 시장의 장기 연평균 성장률(CAGR)을 0.7포인트 하락시키고 있습니다.
부문별 분석
신생아 모니터는 태아 모니터를 바짝 추격하고 있으며, 태아 및 신생아 모니터링 시장 전체의 연평균 성장률(CAGR) 6.74%에 비해 연간 7.43%의 성장률을 보이고 있습니다. 태아 CTG와 외부 도플러 장치는 여전히 매출의 61.45%를 차지하고 있지만, PeriGen Cerebro와 같은 AI 탑재 소프트웨어의 구독 서비스로 인해 하드웨어의 경계가 모호해지고 있습니다. Mindray BeneVision이나 Drager Infinity Delta로 대표되는 다중 매개변수 신생아용 플랫폼은 현재 카프노그래피, 맥박 산소 포화도 측정, 침습적 혈압 측정을 하나의 본체에 통합하여 업그레이드 주기를 촉진하고 있습니다. Masimo의 2024년 Stork 인수는 퇴원 후에도 신생아 모니터링을 지속시키는 것으로, 태아 및 신생아 모니터링 시장 규모에 새로운 수요를 가져올 급성기 이후의 이용 사례를 시사합니다.
단일 기능 모니터가 제한된 NICU의 헤드월 슬롯을 차지하고 있기 때문에 수요는 통합형 모듈로 이동하고 있습니다. 2024년에는 극저체중아를 대상으로 한 폐 보호 전략이 추진됨에 따라 카프노그래프 수요가 현저히 증가했습니다. 다음으로는 패혈증 위험을 예측하는 AI 기능의 등장이 예상되며, 현재 머신러닝을 통한 신호 처리에 관한 특허 출원은 태아 모니터링 관련 특허 출원 총수의 38%를 차지하고 있습니다. 이러한 변화들이 맞물리면서 성능에 대한 기준이 높아지고 기존 기업 간의 경쟁이 치열해지는 한편, 클라우드 네이티브 신규 진출기업들에게는 틈새 시장이 남아 있습니다.
비침습적 방식은 2025년 매출의 69.98%를 차지했으며, 예측 기간 동안에도 연평균 성장률(CAGR) 7.65%로 가장 빠른 성장을 기록할 것으로 전망됩니다. 경피적 CO₂ 모니터는 신생아의 발뒤꿈치 채혈을 30% 줄여 간호 효율을 향상시킵니다. 한편, ICE 80601 표준은 기기 간 경보 프로토콜을 통일하여 임상의의 업무 흐름을 효율화하고 있습니다. 대조적으로, 침습적 기기(태아 두피 전극, 자궁 내압 카테터, 기타)는 비만 환자나 신호 품질이 저하된 경우에 계속해서 사용되고 있습니다. Goldtrace가 2025년에 출시할 예정인 무선 두피 전극은 케이블의 복잡함을 줄여주지만, 도입은 여전히 제한적이며 소량·고수익률의 틈새 시장을 형성하고 있습니다.
침습적 착용에는 고도의 훈련이 필요하며, 미국의 의료 과실 보험사는 종종 자격 인증을 의무화하고 있어 보급에 걸림돌이 되고 있습니다. 그럼에도 불구하고, 복잡한 분만 상황에서 이러한 기기의 진단 정확도는 지속적인 조달을 보장하며, 더 광범위한 태아 및 신생아 모니터링 시장 내에서 규모는 작지만 매우 중요한 인접 부문을 확보하고 있습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 45.3%를 차지했으며, 이를 주도한 것은 네트워크화된 CTG를 도입한 미국의 병원 3,000곳과 레벨 III/IV NICU(신생아 집중 치료실) 800곳이었습니다. 영구적인 원격 모니터링 코드의 도입으로 웨어러블 태아 패치의 판매가 확대되고 있는 반면, 2024년에 발효된 FDA의 사이버 보안 규제로 인해 저비용 수입업체에 대한 진입 장벽이 높아지고 있습니다. 캐나다 각 주의 의료 서비스에서는 표준 5년 주기로 약 10년 정도 사용된 콘솔을 갱신하고 있지만, 멕시코에서는 공공 예산이 디지털 네트워크보다 기본적인 산과 키트를 우선시하고 있어 도입이 지연되고 있습니다.
아시아태평양은 연평균 8.11%의 성장률을 기록하며 가장 빠르게 성장하는 시장입니다. 중국은 현급 모자병원에 20억 위안 이상을 투자한 결과, 2023년에 산모 사망률을 출생 10만 명당 15.1명으로 낮추었습니다. Mindray는 2024년에 1만 8,000대의 신생아 모니터를 출하하여 전년 대비 22% 증가를 기록했습니다. 인도의 ‘LaQshya’ 프로그램은 5,000개 시설의 분만실 개보수에 320억 루피(3억 8,500만 달러)를 투자하여 휴대용 도플러 기기의 광범위한 보급을 뒷받침하고 있습니다. 일본은 인력 부족을 보완하기 위해 AI 탑재 모니터에 막대한 투자를 하고 있어, 저출산 추세와는 반대되는 양상을 보이고 있습니다. 한편, 호주와 한국은 정기적인 장비 교체에 따른 수요로 인해 한 자릿수 중반대의 성장률을 유지하고 있습니다.
유럽은 2025년 매출에서 큰 비중을 차지했으나, MDR 관련 CE(의료기기) 지연 및 GDPR(EU 개인정보보호규정)의 암호화 규정으로 인해 클라우드 기반 도입이 주춤하고 있습니다. 독일, 프랑스, 영국은 병원 네트워크가 밀집되어 있어 여전히 지역 매출의 대부분을 차지하고 있습니다. 중동 및 아프리카를 합치면 상당한 점유율을 차지하고 있습니다. 걸프 국가들은 모자 의료를 전문으로 하는 대규모 병원에 대한 투자를 추진하고 있지만, 사하라 이남 아프리카에서는 정전이 디지털 기술 도입을 저해하는 요인으로 작용하고 있습니다. 남미에서는 통화 변동의 영향으로 자본 설비 예산이 제한되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the fetal and neonatal monitoring market size is projected to be USD 9.81 billion in 2025, USD 10.47 billion in 2026, and reach USD 14.5 billion by 2031, growing at a CAGR of 6.74% from 2026 to 2031.
This report is Segmented by Product (Fetal Monitoring Devices, and Neonatal Monitoring Devices), Method (Invasive, Non-Invasive), Portability (Portable, Non-Portable), End User (Hospitals, Neonatal Care Centers, Home-Care Settings, Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Fetal And Neonatal Monitoring Market Trends and Insights
Rising Pre-Term & Low-Birth-Weight Deliveries
The U.S. pre-term rate climbed to 10.41% in 2024 . Hospitals respond by deploying continuous electronic fetal monitoring in labor suites and stocking Level III NICUs with multiparameter devices that track heart rate, oxygen saturation, and transcutaneous carbon dioxide. Demand is also shifting to wireless Doppler patches for high-risk pregnancies managed at home, a segment enabled by permanent U.S. telehealth codes. Portable monitors compliant with ISO 80601-2-85 remain essential in rural Africa and South Asia, where mains power is unreliable. Collectively, these dynamics lift unit volumes faster than population growth, sustaining the fetal and neonatal monitoring market even in low-birth-rate economies.
Government Maternity-Care Initiatives in Emerging Economies
Between 2020 and 2025, India's Janani Suraksha Yojana distributed cash incentives to 30 million mothers, channeling deliveries toward accredited facilities equipped with fetal monitors. China's provinces have earmarked more than CNY 2 billion (USD 280 million) in 2024 for NICU upgrades under the three-child policy . Ethiopia, after equipping 500 health centers with handheld Dopplers, recorded an 18% stillbirth reduction in two years. These policies converge on low-cost, non-invasive devices, accelerating external Doppler and handheld ultrasound sales. Faster regulatory acceptance, with many ministries accepting FDA or CE clearances without in-country trials, condenses vendor entry times to under nine months, widening geographic reach for the fetal and neonatal monitoring market.
Limited Device Accessibility in Rural LMIC Facilities
A 2024 World Bank audit revealed that 43% of primary health centers in Kenya, Tanzania and Uganda face daily power outages over four hours, hampering mains-powered CTG deployment. Consumable spoilage rates exceed 15% in tropical climates, inflating per-use costs. As a result, handheld Dopplers priced below USD 300 dominate, yet lack continuous waveforms needed for quality audits. Stillbirth rates remain stubbornly high-21 per 1,000 in sub-Saharan Africa-highlighting that hardware alone cannot offset workforce and infrastructure gaps. These factors collectively subtract 0.7 percentage points from the long-term CAGR of the fetal and neonatal monitoring market.
Other drivers and restraints analyzed in the detailed report include:
- Expanding NICU Capacity Across Private Hospital Chains
- Increasing Adoption of Advanced CTG & Ultrasound Systems
- Lengthy 510(k)/CE Approval Timelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Neonatal monitors are closing on fetal systems, expanding 7.43% annually against the broader fetal and neonatal monitoring market CAGR of 6.74%. Fetal CTG and external Doppler devices still anchor 61.45% of revenue, but AI-enabled software subscriptions, such as PeriGen Cerebro, blur hardware boundaries. Multiparameter neonatal platforms, exemplified by Mindray BeneVision and Drager Infinity Delta, now bundle capnography, pulse oximetry, and invasive blood pressure in one chassis, driving upgrade cycles. Masimo's 2024 acquisition of Stork extends neonatal surveillance beyond discharge, hinting at post-acute use cases that add fresh volume to the fetal and neonatal monitoring market size.
Demand migrates toward integrated modules because single-function monitors crowd limited NICU head-wall slots. Capnograph volumes rose notably in 2024 as lung-protective strategies targeted extremely low-birth-weight infants. AI layers that predict sepsis risk are next, with patent filings for machine-learning signal processing now 38% of total fetal-monitoring patent applications. Collectively, these shifts set a taller performance bar, tightening competition among incumbents while leaving niche space for cloud-native entrants.
Non-invasive techniques command 69.98% of 2025 revenue and are also expected to register the fastest growth in the forecast period, with a CAGR of 7.65%. Transcutaneous CO2 monitors slash neonatal heel sticks by 30%, improving nursing efficiency. Meanwhile, the ICE 80601 standard aligns alarm protocols across devices, streamlining clinician workflows. Conversely, invasive tools-fetal scalp electrodes, intrauterine pressure catheters-retain use in obese patients or when signal quality degrades. Goldtrace's 2025 wireless scalp electrode mitigates cable clutter, but adoption remains selective, anchoring a low-volume, high-margin niche.
Training requirements are higher for invasive placements, and malpractice insurers in the United States often mandate credentialing, dampening uptake. Still, the devices' diagnostic precision in complex labor ensures continued procurement, safeguarding a small but critical adjacency inside the larger fetal and neonatal monitoring market.
Complete Report Scope:
- By Product
- Fetal Monitoring Devices
- External Doppler HR Monitors
- Cardiotocography (CTG) Systems
- Uterine Contraction Monitors
- Fetal Pulse Oximeters
- Wireless/Wearable Fetal Patches
- AI-Enabled Predictive Platforms
- Other Fetal Monitoring Devices
- Neonatal Monitoring Devices
- Cardiac Monitors
- Capnographs
- Blood-Pressure Monitors
- Pulse Oximeters
- Integrated Multiparameter Monitors
- Respiratory Monitors
- Other Neonatal Monitoring Devices
- Fetal Monitoring Devices
- By Method
- Invasive
- Non-Invasive
- By Poribility
- Portable
- Non Portable
- By End User
- Hospitals
- Neonatal Care Centres
- Home-Care Settings
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 45.3% of global revenue in 2025, led by 3,000 U.S. hospitals with networked CTG and 800 Level III/IV NICUs. Permanent remote-monitoring codes amplify sales of wearable fetal patches, while the FDA's cybersecurity mandate, activated in 2024, raises entry barriers for low-cost importers. Canada's provincial health services replace decade-old consoles on standard five-year cycles, whereas Mexico lags because public budgets favor basic obstetric kits over digital networks.
Asia-Pacific is the fastest-growing theatre at 8.11% per year. China cut maternal mortality to 15.1 per 100,000 births in 2023 after pouring CNY 2+ billion into county-level maternal-child hospitals. Mindray shipped 18,000 neonatal monitors in 2024, up 22% year-on-year. India's LaQshya program funnels INR 3,200 crore (USD 385 million) into labor-room upgrades across 5,000 facilities, supporting broad diffusion of portable Dopplers. Japan bucks the low-birth trend by spending heavily on AI-enabled monitors to offset staffing gaps, while Australia and South Korea grow at mid-single-digit levels tied to routine replacement.
Europe contributed significant share of 2025 revenue, but MDR-related CE delays and GDPR encryption rules dampen cloud-based deployments. Germany, France and the U.K. still account for majority of regional sales thanks to dense hospital networks. The Middle East and Africa combine for notable share; Gulf states invest in maternal-child megahospitals, but sub-Saharan Africa struggles with power outages that curtail digital uptake. South America faces currency swings that cap capital-equipment budgets.
- Analogic
- Arjo AB
- Atom Medical
- Beckton Dickinson
- Cardinal Health
- The Cooper Companies
- Dragerwerk
- EDAN Instruments Inc.
- Fisher & Paykel Healthcare
- FUJIFILM
- GE Healthcare
- Getinge
- Huntleigh Healthcare Ltd.
- International Biomedical
- Koninklijke Philips
- Masimo
- Medtronic
- Mindray Bio-Medical Electronics
- Natus Medical
- Nihon Kohden
- Phoenix Medical Systems Pvt Ltd.
- Siemens Healthineers
- Spacelabs Healthcare
- Vyaire Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Pre-Term & Low-Birth-Weight Deliveries
- 4.2.2 Government Maternity-Care Initiatives in Emerging Economies
- 4.2.3 Expanding NICU Capacity Across Private Hospital Chains
- 4.2.4 Increasing Adoption of Advanced CTG & Ultrasound Systems
- 4.2.5 Integration of Maternal-Fetal Big-Data Platforms with Hospital Command Centers
- 4.2.6 Insurance-Reimbursement Shifts Favoring Remote Fetal Telemetry
- 4.3 Market Restraints
- 4.3.1 Limited Device Accessibility in Rural LMIC Facilities
- 4.3.2 Lengthy 510(K)/CE Approval Timelines
- 4.3.3 Rising Cyber-Security Insurance Premiums for Networked NICU Devices
- 4.3.4 Consumer Data-Privacy Concerns Curbing Home-Monitor Uptake
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Fetal Monitoring Devices
- 5.1.1.1 External Doppler HR Monitors
- 5.1.1.2 Cardiotocography (CTG) Systems
- 5.1.1.3 Uterine Contraction Monitors
- 5.1.1.4 Fetal Pulse Oximeters
- 5.1.1.5 Wireless/Wearable Fetal Patches
- 5.1.1.6 AI-Enabled Predictive Platforms
- 5.1.1.7 Other Fetal Monitoring Devices
- 5.1.2 Neonatal Monitoring Devices
- 5.1.2.1 Cardiac Monitors
- 5.1.2.2 Capnographs
- 5.1.2.3 Blood-Pressure Monitors
- 5.1.2.4 Pulse Oximeters
- 5.1.2.5 Integrated Multiparameter Monitors
- 5.1.2.6 Respiratory Monitors
- 5.1.2.7 Other Neonatal Monitoring Devices
- 5.1.1 Fetal Monitoring Devices
- 5.2 By Method
- 5.2.1 Invasive
- 5.2.2 Non-Invasive
- 5.3 By Poribility
- 5.3.1 Portable
- 5.3.2 Non Portable
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Neonatal Care Centres
- 5.4.3 Home-Care Settings
- 5.4.4 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Analogic Corporation
- 6.3.2 Arjo AB
- 6.3.3 Atom Medical Corporation
- 6.3.4 Becton, Dickinson and Company
- 6.3.5 Cardinal Health, Inc.
- 6.3.6 CooperSurgical Inc.
- 6.3.7 Dragerwerk AG & Co. KGaA
- 6.3.8 EDAN Instruments Inc.
- 6.3.9 Fisher & Paykel Healthcare
- 6.3.10 Fujifilm Holdings Corporation
- 6.3.11 GE Healthcare
- 6.3.12 Getinge AB
- 6.3.13 Huntleigh Healthcare Ltd.
- 6.3.14 International Biomedical
- 6.3.15 Koninklijke Philips N.V.
- 6.3.16 Masimo Corporation
- 6.3.17 Medtronic plc
- 6.3.18 Mindray Bio-Medical Electronics
- 6.3.19 Natus Medical Incorporated
- 6.3.20 Nihon Kohden Corporation
- 6.3.21 Phoenix Medical Systems Pvt Ltd.
- 6.3.22 Siemens Healthineers
- 6.3.23 Spacelabs Healthcare
- 6.3.24 Vyaire Medical Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


