|
시장보고서
상품코드
2120559
BPaaS(Business-Process-as-a-Service) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Business-Process-as-a-Service - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
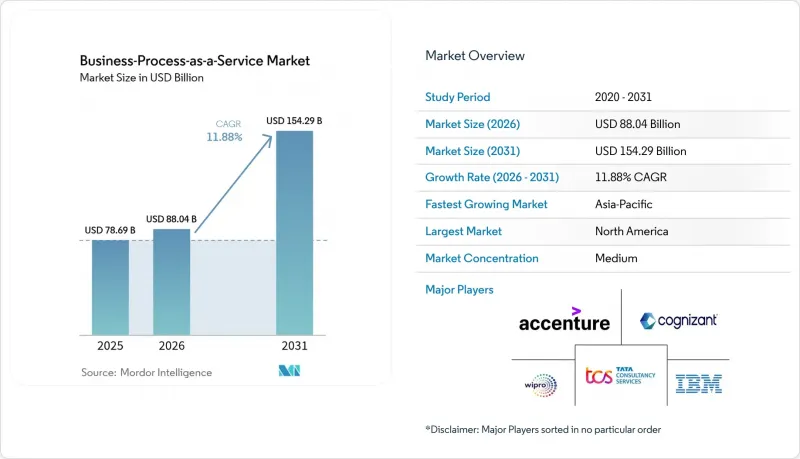
에 의하면, BPaaS(Business-Process-as-a-Service) 시장 규모는 2025년 786억 9,000만 달러로 평가되었습니다. 2026년에는 880억 4,000만 달러로 확대되어 2026-2031년에 걸쳐 CAGR 11.88%로 성장을 지속하여, 2031년에는 1,542억 9,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 조직 규모별(대기업, 중소기업(SME)), 프로세스별(인적자원관리(HRM), 회계·재무, 기타),구축 모델별(퍼블릭 클라우드 BPaaS, 프라이빗 클라우드 BPaaS, 하이브리드·멀티 클라우드 BPaaS), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), IT 및 통신, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 BPaaS(Business-Process-as-a-Service) 시장 동향 및 인사이트
클라우드 서비스에 대한 수요 증가와 프로세스 표준화
클라우드 플랫폼으로의 보편적인 전환이 대규모 프로세스 표준화를 뒷받침하고 있습니다. 현재 기업의 94%가 워크플로우 효율화, 도입 주기 단축, 일관된 거버넌스 확보를 위해 클라우드 솔루션을 활용하고 있습니다. 유연한 리소스 할당을 통해 새로운 자본 투자 결정을 강요받지 않고도 수요의 급격한 변화에 대응할 수 있게 됩니다. IBM에 따르면, 기업의 77%가 이미 하이브리드 아키텍처를 도입하여 전략적 워크로드를 우선시하는 관할 구역에 유지하면서, 여러 클라우드를 아우르는 핵심 프로세스를 통합할 수 있게 되었습니다. 표준화된 클라우드 네이티브 모듈은 통일된 감사 추적이 필수적인 은행 및 보험 산업의 규정 준수 업무를 가속화합니다. 그 결과, BPaaS(Business-Process-as-a-Service) 시장은 속도, 회복력, 세계 확장성을 추구하는 모든 산업에서 수년에 걸쳐 지속적인 성장 모멘텀을 유지하고 있습니다.
운영 비용 절감 및 생산성 향상의 필요성
경제적 역풍으로 인해 고정비를 종량제 과금 모델로 대체해야 한다는 압박이 커지고 있습니다. BPaaS는 다년간의 라이선스 계약, 데이터센터 감가상각비, 인건비 등의 간접비를 실제 이용 현황에 따른 변동 요금으로 전환합니다. DXC Technology의 보고서에 따르면, 조직이 기존 아웃소싱 방식에서 BPaaS 프레임워크로 전환함으로써 20-30%의 비용 절감을 실현하고 있습니다. 이러한 서비스에 내장된 프로세스 자동화를 통해 생산성이 더욱 향상되었으며, 일부 기업에서는 재무 백오피스 업무 효율이 40% 향상되었다고 보고되고 있습니다. 이러한 재무적·업무적 이점이 결합되어, BPaaS(Business-Process-as-a-Service) 시장은 단기적인 수익성과 장기적인 경쟁력을 높이기 위한 현실적인 수단으로서 확고한 입지를 다지고 있습니다.
데이터 보안 및 개인정보 보호에 대한 우려 고조
BPaaS 도입에는 분산형 인프라가 수반되며, 이는 위협의 표적이 되는 범위를 확대할 가능성이 있습니다. 남아프리카준비은행은 통제가 미흡할 경우 클라우드 컴퓨팅이 운영 위험 및 시스템적 위험을 증폭시킬 수 있다고 경고하고 있습니다. 유럽의 GDPR(EU 개인정보보호규정)이나 캘리포니아주의 CCPA와 같은 규제에서는 준수하지 않을 경우 엄격한 처벌이 부과되므로, 제공업체는 고도의 암호화, ID 관리, 지역별 데이터 상주 아키텍처 도입을 강요받고 있습니다. 모니터링 강화로 인해 의사결정 주기가 일시적으로 지연되고, BPaaS(Business-Process-as-a-Service) 시장에 대한 신뢰를 재구축하기 위한 보안 강화 플랫폼이 등장하고 있음에도 불구하고, 기밀성이 높은 산업 분야에서의 단기적인 도입은 제한되고 있습니다.
부문별 분석
2025년에는 대기업이 BPaaS(Business-Process-as-a-Service) 시장 점유율의 63.55%를 차지하며 시장을 주도했습니다. 이 기업들은 표준화된 세계 워크플로를 활용하여 감사를 간소화하고 중복되는 플랫폼을 줄이고 있습니다. 대부분의 경우 비핵심 재무 및 인사 업무를 아웃소싱하는 것부터 시작하여, 거버넌스 체제의 견고성이 확인된 단계에서 고객 경험 및 공급망 분석으로 적용 범위를 확대되고 있습니다. 통합은 여전히 최우선 과제이며, 많은 기업이 On-Premise ERP와 퍼블릭 클라우드 마이크로서비스를 통합하는 미들웨어 계층을 도입하여 전략적인 데이터 관리를 유지하면서 벤더의 혁신을 최대한 활용하고 있습니다. 이와 병행하여, 새로 구성된 전사적 거버넌스 위원회가 성과 기반 계약 하에 벤더의 성과를 모니터링하며, 전략적 목표와의 지속적인 부합성을 확보하고 있습니다.
중소기업은 그동안 존재감이 미미했으나, 현재는 연평균 성장률(CAGR) 12.97%로 예측되는 가장 강력한 성장세를 보이고 있습니다. ‘클라우드 퍼스트’ 솔루션은 설비 투자, 전문 인력 부족, 인프라 유지보수 등 기존의 장벽을 제거합니다. 일본의 쿠벨(Kuber)사에 따르면, 자사의 ‘Chatwork’ 플랫폼은 2024년 9월 기준 60만 5,000개 중소기업 고객사가 이용해, 이 부문의 잠재 수요가 높다는 점이 부각되었습니다. 중소기업은 일반적으로 급여 계산, 청구서 발행, 헬프데스크 자동화와 같은 단일 프로세스 모듈부터 도입을 시작하여, 신뢰성이 입증된 후 엔드투엔드 제품군으로 확대해 나갑니다. 탄력적인 요금 모델은 급성장기나 경기 침체기에 현금 흐름의 유연성을 확보하는 데 매우 중요합니다. 그 결과, 각 제공업체들이 산업별 규정 준수 요건에 맞춘 사전 설정된 번들을 제공함에 따라, 중소기업이 주도하는 BPaaS(Business-Process-as-a-Service) 시장 규모는 2031년까지 크게 확대될 것으로 예측됩니다.
인사 관리(HR)는 2025년 매출의 23.85%를 차지했으며, 이는 표준화된 채용, 급여 계산, 인재 참여 워크플로가 규정 준수 위험을 줄이고 직원 경험을 향상시킨다는 인식이 전 세계적으로 확산되고 있음을 반영합니다. 현재 많은 공급업체들이 이직률 예측, 기술 격차 파악, 학습 컨텐츠 추천을 수행하는 예측 분석 기능을 인사(HR) 모듈과 결합하고 있습니다. 또한, 회계 및 재무 프로세스에서도 로봇 기반 청구서 대조, 자동 대조, AI를 활용한 부정 감지를 통해 정확도가 향상되고 처리 시간이 단축됨에 따라 주목을 받고 있습니다. 공급망 및 조달 솔루션은 변동이 심한 물류 환경에서 매우 중요한 공급업체와의 협업 및 재고 가시성을 향상시킵니다.
고객 서비스 및 지원 부문은 연간 14.34%의 성장이 예상되며, 브랜드들이 옴니채널을 통한 고객 참여로 무게중심을 옮기면서 성장을 주도하고 있습니다. AI를 활용한 챗봇과 음성 분석을 통해 기존 콜센터보다 훨씬 낮은 비용으로 즉각적이고 개인화된 대응이 가능해집니다. 서덜랜드 세계(Sutherland Global)의 도입 사례에서는 평균 응답 시간을 단축하면서 첫 번째 대응 해결률 향상, NPS 점수 향상, 에스컬레이션 감소를 실현했습니다. 영업 및 마케팅용 BPaaS는 이러한 진전을 보완하고, 캠페인 데이터와 프론트오피스 분석을 연계함으로써 리드의 질을 향상시킵니다. 운영 모듈에서는 워크플로우 엔진을 현장 서비스 파견, 공장 유지보수 일정 관리, 품질 보증에 적용하고 있습니다. 이러한 혁신들이 결합되어 BPaaS(Business-Process-as-a-Service) 시장의 지속적인 성장을 뒷받침하고 있습니다.
지역별 분석
북미는 조기 클라우드 도입과 탄탄한 공급업체 생태계의 뒷받침을 받아 2025년 BPaaS(Business-Process-as-a-Service) 시장 매출의 40.85%를 차지했습니다. 금융 기관은 BPaaS를 활용하여 관할 구역을 초월한 규정 준수 문서의 통합을 도모하는 한편, 소매 그룹은 AI 주도의 고객 서비스 자동화를 추진하고 있습니다. 클라우드 인프라의 집중화가 두드러지며, 영국 경쟁·시장청(CMA)의 추정에 따르면 북미 인프라 시장에서 AWS가 40-50%, 마이크로소프트가 30-40%의 점유율을 차지하고 있는 것으로 나타났습니다. 이러한 지배적 지위에 힘입어 BPaaS 벤더들은 지연 시간 최적화 및 공동 시장 진출 프로그램을 목적으로 하이퍼스케일러와의 전략적 제휴를 추진하고 있습니다.
아시아태평양은 2026년부터 2031년까지 12.62%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 인도, 필리핀, 인도네시아 각국 정부는 운영 비용 절감과 시민 서비스 향상을 위해 ‘클라우드 퍼스트’ 정책을 추진하고 있습니다. 인도 데이터 보안 위원회에 따르면, 인도의 클라우드 시장은 2022년까지 77억 달러에 달했으며, 기반 인프라 구축이 진행되고 있음을 알 수 있습니다. 현지 제공업체들은 지역별 데이터 현지화 요건에 대응하기 위해 세계 기업들과 제휴하고 있습니다. 인력 부족에 직면한 일본 기업들은 정형화된 업무의 자동화를 위해 BPaaS를 활용하고 있으며, 이로 인해 제조업 및 소매업 전반에 걸쳐 수요가 촉진되고 있습니다.
유럽에서는 엄격한 개인정보 보호 규제가 도입 옵션을 좌우하고 있어 꾸준한 성장이 예상됩니다. GDPR(EU 개인정보보호규정) 준수가 계약 조건, 데이터 저장지 조항, 공동 책임 체계를 형성하고 있습니다. 2029년까지 213억 2,000만 달러에 달할 것으로 예상되는 독일의 BPO 시장에서는 이미 기업의 81%가 클라우드를 도입했습니다. 금융 기관들은 Eurofi가 정한 감독 지침을 충족하기 위해 현지 소버린 클라우드와 확장 가능한 퍼블릭 리소스를 결합한 하이브리드 모델을 선호하고 있습니다. 이 지역에서 활발히 추진되고 있는 ESG 움직임은 탄소 회계 및 사회적 영향 보고를 자동화하는 지속가능성을 중시하는 BPaaS 솔루션에 대한 수요를 촉진하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 동향
KTH 26.09.04According to Mordor Intelligence, the business-Process-as-a-Service market size is expected to grow from USD 78.69 billion in 2025 to USD 88.04 billion in 2026 and is forecast to reach USD 154.29 billion by 2031 at 11.88% CAGR over 2026-2031.
This report is Segmented by Organization Size (Large Enterprises and Small and Medium Enterprises), Process (Human Resource Management, Accounting and Finance, and More), Deployment Model (Public Cloud BPaaS, Private Cloud BPaaS, and Hybrid/Multi-Cloud BPaaS), End-User Industry (BFSI, IT and Telecommunications, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Business-Process-as-a-Service Market Trends and Insights
Growing Demand for Cloud Services and Standardized Processes
Universal migration toward cloud platforms underpins large-scale process standardization. Ninety-four percent of enterprises now leverage cloud solutions to streamline workflows, shorten deployment cycles, and ensure consistent governance. Elastic resource allocation supports rapid pivots in demand without forcing new capital decisions. IBM notes that 77% of firms already run hybrid architectures, enabling them to unify core processes over multiple clouds while keeping strategic workloads in preferred jurisdictions. Standardized, cloud-native modules accelerate compliance tasks in banking and insurance, where uniform audit trails are essential. As a result, the Business-Process-as-a-Service market experiences sustained multi-year momentum across sectors that demand speed, resilience, and global reach.
Need to Reduce Operational Cost and Boost Productivity
Economic headwinds intensify pressure to replace fixed costs with consumption-based models. BPaaS converts multi-year license contracts, data-center depreciation, and labor overhead into variable fees that align with actual usage. DXC Technology reports savings of 20-30% when organizations shift from traditional outsourcing to BPaaS frameworks. Process automation embedded in these services delivers additional productivity gains, with some enterprises citing 40% efficiency improvements in finance back-office tasks. These combined financial and operational benefits reinforce the Business-Process-as-a-Service market as a pragmatic lever for near-term profitability and long-term competitiveness.
Heightened Data-Security and Privacy Concerns
BPaaS deployments involve a distributed infrastructure that can enlarge the threat surface. The South African Reserve Bank cautions that cloud computing amplifies operational and systemic risks when controls are weak. European GDPR and California CCPA regulations impose severe penalties for non-compliance, compelling providers to implement sophisticated encryption, identity management, and regional data-residency architectures. Heightened scrutiny temporarily slows decision cycles, limiting short-term adoption in sensitive verticals even as security-enhanced platforms emerge to rebuild trust in the Business-Process-as-a-Service market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of AI / Hyper-automation in BPaaS
- Expansion of Outcome-based (Gain-share) BPaaS Pricing Models
- Integration Complexity with Legacy Core Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large Enterprises dominated 2025 with 63.55% of the Business-Process-as-a-Service market share, leveraging standardized global workflows to simplify audits and cut duplicative platforms. They often start by outsourcing non-core finance and HR tasks, then extend coverage to customer experience and supply-chain analytics once governance structures prove resilient. Integration remains a priority; many deploy middleware layers that blend on-premise ERPs with public-cloud microservices, preserving strategic data control while maximizing vendor innovation. In parallel, fresh enterprise-wide governance councils monitor vendor performance under outcome-based contracts, ensuring continuous alignment with strategic objectives.
SMEs, though historically under-represented, now display the strongest momentum with a forecast 12.97% CAGR. Cloud-first solutions remove traditional barriers such as capital outlay, specialist talent shortages, and infrastructure maintenance. Japan's Kubell Co. reports that its Chatwork platform served 605,000 SME clients by September 2024, underscoring the segment's pent-up demand. SMEs typically begin with single-process modules-payroll, invoicing, or help-desk automation-before scaling to end-to-end suites as reliability is proven. The elastic fee model offers crucial cash-flow flexibility during growth spurts or economic contractions. Consequently, the Business-Process-as-a-Service market size attributable to SMEs is projected to widen substantially through 2031 as providers release pre-configured bundles tailored for industry-specific compliance.
Human Resource Management retained 23.85% of 2025 revenue, reflecting global recognition that standardized recruitment, payroll, and talent-engagement workflows lower compliance risk and enhance employee experience. Many providers now pair HR modules with predictive analytics that forecast attrition, identify skill gaps, and recommend learning content. Accounting and Finance processes also gain traction as robotic invoice matching, automated reconciliations, and AI-driven fraud checks boost accuracy while shrinking cycle times. Supply Chain and Procurement solutions improve vendor collaboration and inventory visibility, critical in volatile logistics environments.
Customer Service and Support, forecast to rise 14.34% annually, leads growth as brands pivot to omnichannel engagement. AI-driven chatbots and voice analytics deliver instant, personalized responses at far lower cost than traditional call centers. Sutherland Global's deployments cut average response time while raising first-contact resolution, enhancing NPS scores, and reducing escalations. Sales and Marketing BPaaS complements these advances, synchronizing campaign data with front-office analytics to sharpen lead quality. Operations modules apply workflow engines to field-service dispatch, plant-maintenance scheduling, and quality assurance. Together, these innovations anchor sustained expansion of the Business-Process-as-a-Service market.
Complete Report Scope:
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Process
- Human Resource Management (HRM)
- Accounting and Finance
- Customer Service and Support
- Sales and Marketing
- Supply Chain and Procurement
- Operations and Other Horizontal Processes
- By Deployment Model
- Public Cloud BPaaS
- Private Cloud BPaaS
- Hybrid/Multi-Cloud BPaaS
- By End-user Industry
- BFSI
- IT and Telecommunications
- Healthcare and Life Sciences
- Retail and E-Commerce
- Manufacturing
- Government and Public Sector
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Singapore
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 40.85% of 2025 revenue for the Business-Process-as-a-Service market, buoyed by early cloud uptake and deep provider ecosystems. Financial institutions use BPaaS to consolidate compliance documentation across jurisdictions, while retail groups pursue AI-led customer-service automation. Cloud infrastructure concentration is notable; the UK Competition and Markets Authority estimates AWS and Microsoft hold 40-50% and 30-40% of North American infrastructure, respectively. This dominance encourages BPaaS vendors to forge strategic alliances with hyperscalers for latency optimization and joint go-to-market programs.
Asia-Pacific is projected to record the fastest 12.62% CAGR between 2026 and 2031. Governments in India, the Philippines, and Indonesia promote "cloud first" mandates to reduce operating costs and improve citizen services. The Data Security Council of India notes that the national cloud market reached USD 7.70 billion by 2022, underscoring the readiness of foundational infrastructure. Indigenous providers partner with global players to address regional data-localization requirements. Japanese enterprises, challenged by labor shortages, lean on BPaaS to automate routine functions, stimulating demand across manufacturing and retail sectors.
Europe exhibits measured growth as stringent privacy rules guide deployment choices. GDPR compliance shapes contract terms, data-residency clauses, and shared-responsibility frameworks. Germany's BPO market, forecast to hit USD 21.32 billion by 2029, already registers 81% cloud adoption among firms. Financial institutions prefer hybrid models, pairing local sovereign clouds with scalable public resources to satisfy supervisory guidance outlined by Eurofi. The region's strong ESG agenda fuels demand for sustainability-centric BPaaS solutions that automate carbon accounting and social-impact reporting.
- Accenture plc
- IBM Corporation
- Tata Consultancy Services (TCS)
- Cognizant Technology Solutions
- Wipro Limited
- HCL Technologies
- Capgemini SE
- Infosys Limited
- Genpact Ltd.
- Fujitsu Ltd.
- Oracle Corporation
- SAP SE
- Deloitte Touche Tohmatsu Limited
- NTT DATA
- CGI Inc.
- DXC Technology
- Tech Mahindra
- EXL Service Holdings
- ADP Inc.
- Alight Solutions
- Paychex Inc.
- UKG (Ultimate Kronos Group)
- TriNet Group
- Ceridian HCM
- WNS Global Services
- Sutherland Global Services
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for cloud services and standardized processes
- 4.2.2 Need to reduce operational cost and boost productivity
- 4.2.3 Rapid adoption of AI/hyper-automation in BPaaS
- 4.2.4 Expansion of outcome-based BPaaS pricing models
- 4.2.5 ESG-linked reporting mandates driving sustainability BPaaS
- 4.2.6 Demand for industry-specific BPaaS solutions
- 4.3 Market Restraints
- 4.3.1 Heightened data-security and privacy concerns
- 4.3.2 Integration complexity with legacy core systems
- 4.3.3 Vendor lock-in and interoperability limitations
- 4.3.4 Sovereign-cloud requirements restricting cross-border BPaaS
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Organization Size
- 5.1.1 Large Enterprises
- 5.1.2 Small and Medium Enterprises (SMEs)
- 5.2 By Process
- 5.2.1 Human Resource Management (HRM)
- 5.2.2 Accounting and Finance
- 5.2.3 Customer Service and Support
- 5.2.4 Sales and Marketing
- 5.2.5 Supply Chain and Procurement
- 5.2.6 Operations and Other Horizontal Processes
- 5.3 By Deployment Model
- 5.3.1 Public Cloud BPaaS
- 5.3.2 Private Cloud BPaaS
- 5.3.3 Hybrid/Multi-Cloud BPaaS
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 IT and Telecommunications
- 5.4.3 Healthcare and Life Sciences
- 5.4.4 Retail and E-Commerce
- 5.4.5 Manufacturing
- 5.4.6 Government and Public Sector
- 5.4.7 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Singapore
- 5.5.4.7 Malaysia
- 5.5.4.8 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 IBM Corporation
- 6.4.3 Tata Consultancy Services (TCS)
- 6.4.4 Cognizant Technology Solutions
- 6.4.5 Wipro Limited
- 6.4.6 HCL Technologies
- 6.4.7 Capgemini SE
- 6.4.8 Infosys Limited
- 6.4.9 Genpact Ltd.
- 6.4.10 Fujitsu Ltd.
- 6.4.11 Oracle Corporation
- 6.4.12 SAP SE
- 6.4.13 Deloitte Touche Tohmatsu Limited
- 6.4.14 NTT DATA
- 6.4.15 CGI Inc.
- 6.4.16 DXC Technology
- 6.4.17 Tech Mahindra
- 6.4.18 EXL Service Holdings
- 6.4.19 ADP Inc.
- 6.4.20 Alight Solutions
- 6.4.21 Paychex Inc.
- 6.4.22 UKG (Ultimate Kronos Group)
- 6.4.23 TriNet Group
- 6.4.24 Ceridian HCM
- 6.4.25 WNS Global Services
- 6.4.26 Sutherland Global Services
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment