|
시장보고서
상품코드
2120607
스마트 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Smart Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
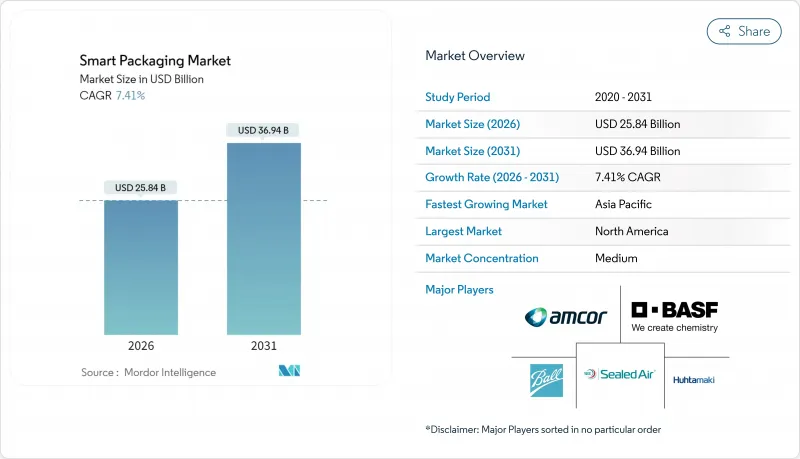
에 의하면, 스마트 포장 시장 규모는 2026년에 258억 4,000만 달러에 달하고, 2031년까지 369억 4,000만 달러에 이를 것으로 예상되며, 예측 기간 중 연평균 복합 성장률(CAGR)은 7.41%를 나타낼 전망입니다.
본 보고서는 기술별(활성 포장, 지능형 포장, 가스 치환 포장), 소재별(종이 및 판지, 플라스틱, 유리,금속, 생분해성 소재), 구성 부품별(센서, 표시기, 데이터 캐리어, 항균제), 최종 사용자 산업별(식품, 음료, 의약품 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 스마트 포장 시장 동향 및 인사이트
프린트 전자 기술의 발전으로 비용 효율적인 RFID 및 NFC 태그 구현이 가능해짐
연질 플라스틱에 전도성 잉크를 롤 투 롤 방식으로 인쇄함으로써, 2024년 이후, 태그 1장당 비용이 약 60% 절감되어, 패시브형 RFID의 비용은 소매업체가 품목 단위 추적에 실용적이라고 간주하는 0.05달러의 기준치를 밑돌았습니다. 그 결과, 의류,화장품, 나아가 중저가 소비재에 이르기까지 실시간 재고 대시보드에 정보를 제공하는 고유 식별자를 부여할 수 있게 되었습니다. 현재 인쇄 회로가 표준 플렉소 인쇄 온도를 견딜 수 있게 됨에 따라, 각 컨버터 업체는 그래픽을 인쇄하는 동일한 공정에서 안테나를 추가할 수 있게 되어 별도의 조립 공정이 필요 없어졌습니다. 스마트폰에서 전력을 공급받는 NFC 태그는 의약품 블리스터 팩에 내장되어 원산지를 인증하거나, 복약 알림 앱을 실행하는 용도로 활용되고 있으며, 이러한 움직임은 2025년에 EU의 여러 시장에서 확대되었습니다. 고급 증류주 제조업체들도 NFC 칩에 암호화된 로트 데이터를 내장하여 소비자에게 직접적인 검증 수단을 제공함으로써, 부정 유용을 방지하고 브랜드에 대한 충성도를 높이고 있습니다.
전자상거래 콜드체인에서 식품 품질의 실시간 모니터링에 대한 수요 증가
식료품 배달 서비스로 인해 라스트 마일 단계의 온도 관리 문제가 드러났습니다. 2025년 조사에 따르면, 냉장 운송 물품의 12%에서 30분 이상 4℃를 초과하는 상태가 지속되어 식품의 품질 저하 위험을 가속화하고 있었습니다. 현재 변색되는 시간·온도 라벨이 도입되어, 소비자는 품질이 저하된 상품을 거부할 수 있게 되었으며, 이는 소매업체의 책임 위험을 경감시키고 폐기물 감축으로도 이어지고 있습니다. 한 솔루션에서는 CO₂ 센서를 조절된 환경 트레이에 내장하여 창고 시스템에 경보를 전송함으로써, 운영자가 위험이 있는 재고를 인근 매장으로 재배치할 수 있게 되었습니다. 콜드체인 사업자들은 이러한 센서를 블록체인 원장과 연동하는 사례가 늘어나고 있으며, 규제 당국과 보험사를 지원하는 위조 불가능한 온도 기록을 생성하고 있습니다. 생물 제제 유통에서 이미 검증된 이 접근 방식은 고수익률의 단백질 제품 및 유기농 농산물로 확대되고 있습니다.
스마트 포장 생산 라인의 높은 초기 설비 투자 비용
압출 성형 라인에 센서 성형 및 칩 실장 스테이션을 사후 장착할 경우, 1개 거점당 1,500만 달러를 초과하는 경우가 많아, 이 비용이 중소규모 가공업체를 시장에서 배제하고 있습니다. 수주량이 계절적으로 변동하면 회수 기간이 길어지며, 일부 신흥 시장에서는 손익분기점이 6년을 넘기도 합니다. 급속한 기술 혁신은 기술 노후화의 위험도 초래합니다. 2024년에 도입된 설비라 하더라도 차세대 플렉서블 회로가 주류가 되면, 감가상각이 완료되기 전에 상각 처리를 해야 할 가능성이 있습니다. 기계 제조업체가 제공하는 ‘서비스형 설비(Equipment-as-a-Service)’ 계약은 초기 자금 수요를 줄여주지만, 상업 대출 인프라가 미비하고 환율 변동이 심한 지역에서는 그 도입이 여전히 제한적입니다.
부문 분석
2025년, 스마트 포장 시장 점유율의 46.54%를 능동형이 차지했으며, 그 중심에는 육류 및 제빵 분야의 부패를 방지하는 산소 흡수제 및 항균 필름이 있었습니다. 저비용 RFID 및 실시간 재고 현황 파악에 대한 수요에 힘입어, 지능형 솔루션은 연평균 성장률(CAGR) 9.23%를 나타낼 것으로 예측됩니다. 가스 치환 포장은 이러한 범주를 연결하는 존재로, 데이터 수집 기능 없이도 유통 기한 연장을 실현하기 때문에 설비의 전면적인 쇄신에 소극적인 중견 가공업체들에게 여전히 인기가 있습니다. 2025년에 출시된 산소 흡수 기능과 색상 변화를 통한 숙도 표시기를 융합한 이중 기능 필름은 컨버터가 복합적인 기능을 부가 판매할 수 있도록 하는 기술 융합을 상징합니다.
이러한 기술의 조합은 최종 사용자의 우선순위를 반영합니다. 의약품 운송업체는 규정 준수를 입증하는 건조제나 온도 라벨을 선호하는 반면, 소비재 제조업체는 레시피나 로열티 프로그램에 대한 접근을 가능하게 하는 NFC 태그를 요구하고 있습니다. 규제상의 장벽도 다릅니다. 항균제는 미국 FDA의 식품 접촉 승인이 필요하여 시장 출시 주기가 6-12개월 연장되지만, RFID에는 그러한 심사가 필요하지 않습니다. 그 결과, 규제 대상이 아닌 부문에서는 RFID 도입이 항균제 도입을 앞지르고 있습니다.
플라스틱은 유연한 가공 조건과 센서 라미네이트와의 호환성 덕분에 2025년에는 소재 매출의 42.43%를 차지했습니다. 바이오 폴리머는 유럽의 일회용 제품 규제로 인해 컨버터들이 폴리젖산(PLA) 및 폴리하이드록시아르카노에이트(PHA) 기판으로 전환함에 따라 연평균 성장률(CAGR) 8.43%로 성장할 전망입니다. 이러한 수지는 현재 방습성 면에서 폴리에틸렌과 동등하지만, 용융 지수가 높기 때문에 압출 라인의 업그레이드가 필요하며, 단위당 200만-400만 달러의 비용이 소요됩니다. 종이는 확립된 재활용 체계에 힘입어 여전히 건조 식품 포장의 주류를 차지하고 있습니다. 한 대형 섬유 제조업체는 2025년 골판지 제품의 회수율이 87%에 달했다고 보고했습니다.
유리와 금속은 여전히 틈새 시장으로 남아 있지만, 그 잠재력을 보여주고 있습니다. 예를 들어, 열변색 잉크를 사용한 알루미늄 캔 시범 제품은 금속 스크랩의 가치를 훼손하지 않으면서 음료의 이상적인 온도를 알려주는 기능을 갖추고 있습니다. 소재 전략은 공급망의 회복탄력성과도 밀접하게 관련되어 있습니다. 2024년 수지 공급 차질로 인해 가공업체들은 20-30%의 추가 비용이 발생함에도 불구하고 원료 다각화와 발효 유래 폴리머에 대한 투자를 할 수밖에 없었습니다.
지역별 분석
북미는 2025년 매출 점유율의 39.74%를 차지했습니다. 이는 대형 소매업체의 조기 RFID 도입 의무화와 모든 처방약 포장에 일련번호를 부여하는 DSCSA의 완전한 시행에 힘입은 결과입니다. 캐나다의 ‘캐나다인을 위한 식품 안전 규정(Safe Food for Canadians Regulations)’은 신선 식품의 추적성을 의무화함으로써 시간 및 온도 추적 시스템의 도입을 더욱 촉진했습니다. 멕시코는 니어쇼어링 거점으로서의 역할을 수행했으며, 다국적 소비재(FMCG) 기업들이 미국의 유통 경로에 대응하기 위해 스마트 라벨 생산 라인을 도입함에 따라 현지 라벨 생산 능력 확대가 가속화되었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 9.76%를 기록하며 가장 높은 성장률을 보일 것으로 예측됩니다. 중국의 ‘제14차 5개년 계획’에서는 냉장 물류에 5,000억 위안(人民元)을 배정하고, 백신에 대한 실시간 온도 모니터링을 의무화했습니다. 전 세계 제네릭 의약품 생산량의 40%를 차지하는 인도의 제약 업계에서는 새로운 국내 규정을 준수하기 위해 수출용 상자에 RFID 및 2차원 바코드를 도입하고 있습니다. 일본에서는 복용을 잊었을 경우 간병인에게 알리는 NFC 연동형 복약 관리 팩의 시범 도입이 진행되고 있으며, 한국에서는 건강기능식품에 대한 추적 및 추적 가능성 적용 범위가 확대되고 있습니다. 호주 및 뉴질랜드에서는 재활용 가능성을 필수 조건으로 삼고 있으며, 분류 시 깨끗하게 분리할 수 있는 단일 기질의 지능형 라벨을 권장하고 있습니다.
유럽에서는 지속가능성에 관한 의무와 엄격한 위조 방지 대책을 결합하고 있습니다. 곧 시행될 ‘포장 및 포장 폐기물 규정’은 2030년까지 모든 포장재의 재활용 가능성 또는 퇴비화 가능성을 목표로 하고 있으며, 수용성 접착제를 사용한 종이 기반 RFID 라벨을 권장하고 있습니다. 독일의 ‘VerpackG’ 법은 재료의 복잡성에 따라 라이선스 비용을 단계적으로 설정하여 각 브랜드가 단일 기판 형태로 전환하도록 장려하고 있습니다. 영국의 플라스틱 포장세는 재생 수지 함유율이 30% 미만인 제품에 벌칙을 부과하고 있어, 인쇄된 센서가 탑재된 기계적 재생 필름에 대한 수요를 가속화하고 있습니다. 중동 및 아프리카는 여전히 규모는 작지만, 미래성이 기대되고 있습니다. 아랍에미리트의 스마트 시티 시범 사업과 사우디아라비아의 ‘비전 2030’ 다각화 계획에는 모두 수입 바이오의약품을 위한 콜드체인 대응 스마트 포장가 포함되어 있습니다. 남아프리카공화국에서는 현재 항레트로바이러스제에 대한 일련번호 부여가 의무화되어 있어, 스마트 라벨 도입의 발판이 되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the smart packaging market size stood at USD 25.84 billion in 2026 and is projected to reach USD 36.94 billion by 2031, reflecting a 7.41% CAGR over the forecast period.
This report is Segmented by Technology (Active Packaging, Intelligent Packaging, and Modified Atmosphere Packaging), Material (Paper and Paperboard, Plastic, Glass, Metal, and Biodegradable Materials), Component (Sensors, Indicators, Data Carriers, and Antimicrobial Agents), End-User Industry (Food, Beverage, Pharmaceuticals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Packaging Market Trends and Insights
Advancement in Printed Electronics Enabling Cost-effective RFID and NFC Tags
Roll-to-roll printing of conductive inks on flexible plastic has reduced the per-tag cost by roughly 60% since 2024, pushing passive RFID below the USD 0.05 threshold that retailers deem viable for item-level tracking. The resulting economics allow apparel, cosmetics, and even mid-priced fast-moving goods to carry unique identifiers that feed real-time inventory dashboards. Printed circuits now survive standard flexographic temperatures, so converters add antennas during the same press pass that applies graphics, eliminating a secondary assembly stage. NFC tags, which harvest power from smartphones, are being integrated into pharmaceutical blister packs to authenticate origin and trigger dose-reminder apps, an approach that will be scaled across several EU markets in 2025. Luxury spirits producers also embed encrypted batch data in NFC chips, providing consumers with a direct verification path that deters diversion and enhances brand engagement.
Growing Demand for Real-time Food Quality Monitoring in E-commerce Cold Chains
Doorstep grocery delivery revealed gaps in last-mile temperature control. A 2025 study showed 12% of refrigerated shipments exceeded 4 °C for more than 30 minutes, accelerating spoilage risks. Color-change time-temperature labels now let shoppers reject compromised items, curbing liability for retailers and cutting waste. One solution embeds CO2 sensors in modified-atmosphere trays and transmits alerts to warehouse systems, letting operators reroute at-risk inventory to nearby stores. Cold-chain providers increasingly back these sensors with blockchain ledgers, creating immutable temperature records that assist regulators and insurers. The approach, proven in biologics distribution, is migrating to high-margin proteins and organic produce.
High Initial Capital Expenditure for Smart Packaging Production Lines
Retrofitting extrusion lines with sensor deposition and chip-placement stations often exceeds USD 15 million per site, a cost that sidelines small and mid-size converters. Payback periods lengthen when order volumes fluctuate seasonally, pushing breakeven beyond six years in some emerging markets. Rapid innovation also triggers technology-obsolescence risk; equipment installed in 2024 may face write-offs before full depreciation if next-gen flexible circuits dominate. Equipment-as-a-service contracts from machinery makers reduce upfront cash demands, yet adoption remains limited where commercial-lending ecosystems are thin and currency volatility is high.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Anti-counterfeiting Regulations in Pharmaceutical Supply Chains
- Consumer Preference for Sustainable Packaging with Integrated Freshness Indicators
- Limited Recycling Infrastructure for Multi-material Active Packaging
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Active formats held 46.54% of smart packaging market share in 2025, anchored by oxygen scavengers and antimicrobial films that cut spoilage in meat and bakery channels. Intelligent solutions are expected to post a 9.23% CAGR, buoyed by low-cost RFID and demand for real-time inventory insight. Modified-atmosphere packaging bridges the categories, offering shelf-life gains without data capture, and remains popular with mid-tier processors hesitant to overhaul equipment. Dual-function films launched in 2025 that merge scavenging with color-changing ripeness indicators illustrate a convergence that lets converters upsell layered capabilities.
The technology mix reflects end-user priorities. Pharmaceutical shippers favor desiccants and temperature labels that document compliance, while consumer-goods producers chase NFC tags that unlock recipes or loyalty programs. Regulatory hurdles differ: antimicrobial agents require U.S. FDA food-contact clearance, adding six to twelve months to launch cycles, whereas RFID incurs no such review. As a result, RFID adoption outpaces antimicrobial roll-outs in non-regulated categories.
Plastic brought in 42.43% of material revenue in 2025 thanks to flexible processing windows and compatibility with sensor lamination. Biopolymers are set to expand at 8.43% CAGR, spurred by European single-use rules that steer converters toward polylactic acid and polyhydroxyalkanoate substrates. These resins now match polyethylene in moisture barrier, yet their higher melt index forces extrusion-line upgrades costing USD 2-4 million per unit. Paper still dominates dry-goods packs, backed by well-established recycling loops; one leading fiber company cited an 87% recovery rate for its corrugated formats in 2025.
Glass and metal remain niche but illustrate possibilities: a pilot aluminum can with thermochromic ink signals ideal drinking temperatures without compromising scrap-metal valorization. Material strategy also aligns with supply-chain resilience. Resin disruptions in 2024 pushed converters to diversify feedstocks and invest in fermentation-derived polymers despite a 20-30% cost premium.
Complete Report Scope:
- By Technology
- Active Packaging
- Intelligent Packaging
- Modified Atmosphere Packaging
- By Material
- Paper and Paperboard
- Plastic
- Glass
- Metal
- Biodegradable Polymers
- By Component
- Sensors
- Indicators
- Data Carriers
- Antimicrobial Agents
- By End-user Industry
- Food
- Beverage
- Pharmaceuticals
- Cosmetics and Personal Care
- Electronics
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held a 39.74% revenue share in 2025, underpinned by early RFID mandates from big-box retailers and full DSCSA enforcement, which serialized every prescription pack. Canada's Safe Food for Canadians Regulations further spurred the adoption of time-temperature tracking by requiring traceability for fresh produce. Mexico's role as a near-shoring hub accelerated local label capacity as multinational FMCG firms installed smart-label lines to serve U.S. distribution routes.
Asia-Pacific is projected to deliver the fastest 9.76% CAGR through 2031. China's 14th Five-Year Plan earmarked CNY 500 billion for refrigerated logistics and mandated real-time temperature monitoring for vaccines. India's pharmaceutical sector, which is responsible for 40% of global generic output, now utilizes RFID and 2D codes on export cartons to comply with new domestic regulations. Japan pilots NFC-linked adherence packs that alert caregivers to missed doses, while South Korea expands track-and-trace to health supplements. Australia and New Zealand make recyclability a prerequisite, favoring mono-substrate intelligent labels that separate cleanly during sortation.
Europe combines sustainability mandates with rigorous anti-counterfeiting measures. The upcoming Packaging and Packaging Waste Regulation aims for universal recyclability or compostability by 2030, encouraging paper-based RFID labels with water-soluble adhesives. Germany's VerpackG tiers license fees by material complexity, nudging brands toward single-substrate formats. The U.K. plastic-packaging tax penalizes content with under 30% recycled resin, accelerating demand for mechanically recycled films carrying printed sensors. The Middle East and Africa remain small but show promise; United Arab Emirates smart-city pilots and Saudi Arabia's Vision 2030 diversification plan both include cold-chain smart packs for imported biologics. South Africa now requires serialization on antiretrovirals, creating a beachhead for smart labels.
- Sealed Air Corporation
- Amcor PLC
- Ball Corporation
- BASF SE
- Huhtamaki Oyj
- Stora Enso
- Avery Dennison Corporation
- Zebra Technologies Corporation
- 3M Company
- International Paper Company
- Smurfit WestRock
- Tetra Pak International SA
- R.R. Donnelley and Sons Company
- Mondi Group
- Coveris Holdings S.A.
- Pragmatic Semiconductor
- Thin Film Electronics ASA
- Emerson Electric Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Advancement in Printed Electronics Enabling Cost-effective RFID and NFC Tags
- 4.2.2 Growing Demand for Real-time Food Quality Monitoring in E-commerce Cold Chains
- 4.2.3 Stringent Anti-counterfeiting Regulations in Pharmaceutical Supply Chains
- 4.2.4 Consumer Preference for Sustainable Packaging with Integrated Freshness Indicators
- 4.2.5 Adoption of IoT-enabled Packaging by CPG Brands for Direct-to-Consumer Engagement
- 4.2.6 Rapid Growth of Smart Retail Shelves Requiring Embedded Intelligent Packaging
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Expenditure for Smart Packaging Production Lines
- 4.3.2 Limited Recycling Infrastructure for Multi-material Active Packaging
- 4.3.3 Privacy Concerns Over Consumer Data Collected via Connected Packaging
- 4.3.4 Absence of Global Interoperability Standards for Sensor-based Packaging
- 4.4 Industry Value Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Active Packaging
- 5.1.2 Intelligent Packaging
- 5.1.3 Modified Atmosphere Packaging
- 5.2 By Material
- 5.2.1 Paper and Paperboard
- 5.2.2 Plastic
- 5.2.3 Glass
- 5.2.4 Metal
- 5.2.5 Biodegradable Polymers
- 5.3 By Component
- 5.3.1 Sensors
- 5.3.2 Indicators
- 5.3.3 Data Carriers
- 5.3.4 Antimicrobial Agents
- 5.4 By End-user Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceuticals
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Electronics
- 5.4.6 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Kenya
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sealed Air Corporation
- 6.4.2 Amcor PLC
- 6.4.3 Ball Corporation
- 6.4.4 BASF SE
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Stora Enso
- 6.4.7 Avery Dennison Corporation
- 6.4.8 Zebra Technologies Corporation
- 6.4.9 3M Company
- 6.4.10 International Paper Company
- 6.4.11 Smurfit WestRock
- 6.4.12 Tetra Pak International SA
- 6.4.13 R.R. Donnelley and Sons Company
- 6.4.14 Mondi Group
- 6.4.15 Coveris Holdings S.A.
- 6.4.16 Pragmatic Semiconductor
- 6.4.17 Thin Film Electronics ASA
- 6.4.18 Emerson Electric Co.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment