

|
시장보고서
상품코드
2120608
보안 로봇 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Security Robots - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
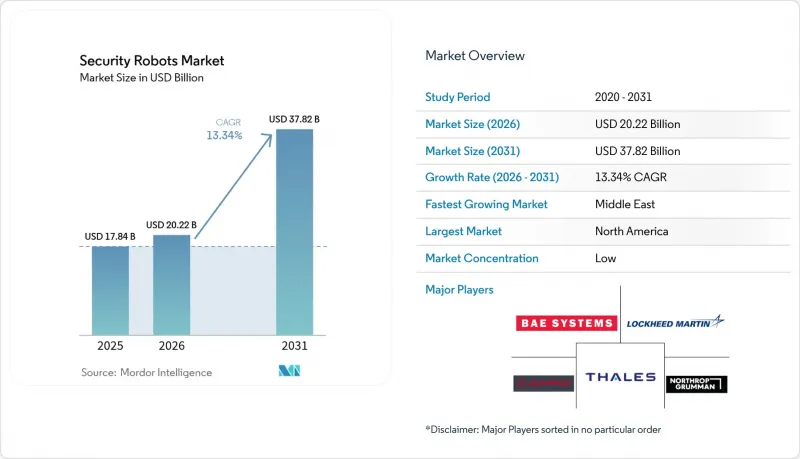
에 의하면, 보안 로봇 시장 규모는 2025년 178억 4,000만 달러로 평가되었습니다. 2026년에는 202억 2,000만 달러로 확대되어 2031년까지 378억 2,000만 달러에 이르며 2026-2031년에 걸쳐 CAGR 13.34%를 나타낼 것으로 예측됩니다.
본 보고서는 유형별(무인 지상 차량, 자율형 수중 차량, 하이브리드 수륙 양용 로봇), 구성 요소별(하드웨어, 소프트웨어 및 AI 스택, 서비스), 최종 사용자별(방위 및 군사, 주택·사유지, 기타), 용도별(순찰·모니터링,스파이 활동·정찰, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 보안 로봇 시장 동향 및 인사이트
AI를 활용한 지각 스택 도입을 통한 중요 인프라의 오경보율 감소
핵심 인프라 소유주들은 규칙 기반의 움직임 감지 시스템을 열화상, 가시광선, 레이더 입력을 융합한 다중 모드 지각 시스템으로 대체하고 있습니다. 유럽의 전력 변전소에서 실시된 MOBOTIX의 현장 테스트에서는 2024년에 오감지율을 70% 감소시켜, 제어실 직원이 검증된 경보 조사에 전념할 수 있게 되었습니다. NVIDIA Jetson 모듈을 활용한 엣지 추론은 클라우드 지연을 해소하고, 에어 갭 방식을 채택한 방위 시설을 지원합니다. 미국 에너지부가 2025년에 갱신한 지침에 따라, 카테고리 I 원자력 시설에서는 AI 기반 침입 감지 시스템 도입이 의무화되어 도입 주기가 가속화되고 있습니다. 보험사들도 현재 인증된 AI 지각 시스템을 도입한 시설에 대해 보험료 할인을 제공하고 있어, 운영 효율성 향상을 넘어서는 경제적 추진력이 생겨나고 있습니다.
경비 순찰용 민간 BVLOS 드론 비행 경로의 확대
미국 연방항공청(FAA)은 2024년에 일상적인 BVLOS 운항을 승인하여, 유틸리티자, 국경 경비 기관, 파이프라인 운영 사업자가 유인 추적기를 사용하지 않고도 선형 자산을 모니터링할 수 있게 되었습니다. 호주 민간항공안전청(CASA)도 2025년에 유사한 BVLOS 체계를 제정하여, 외딴 지역의 광산이나 해상 석유 플랫폼에서 드론 순찰의 적용 범위를 확대했습니다. ASTM 인터내셔널의 F3411 원격 식별 표준은 드론의 ID와 텔레메트리 데이터를 실시간으로 전송하도록 의무화함으로써 공공 안전에 대한 우려를 완화하고 있습니다. 2025년 미 육군으로부터 다년간의 주변 모니터링 계약을 수주한 Shield AI의 V-BAT 플랫폼은 군사 부문에서의 실적이 민간 조달로 파급되고 있는 좋은 사례입니다. 규제, 표준, 현장 검증된 기술이 조화를 이루면서 에너지, 운송, 국방 각 부문에서의 도입 기간이 단축되고 있습니다.
다중 로봇 함대의 배치를 제한하는 세분화된 무선 주파수 대역 규제
집단 지능에는 저지연 통신 링크가 필수적이지만, 무선 주파수 할당은 지역에 따라 크게 다릅니다. 국제전기통신연합(ITU)의 2023년 회의에서는 일부 지역에서 5.9GHz 대역을 차량 네트워크용으로 할당하는 반면, 다른 지역에서는 Wi-Fi용으로 할당하고 있어 보안 로봇 공급업체들은 여러 무선 구성을 설계할 수밖에 없는 상황입니다. 유럽연합(EU) 회원국들은 1GHz 이하의 산업용 주파수 대역에 대해 서로 다른 규정을 적용하고 있어, 이로 인해 인증 비용이 증가하고 국경을 넘는 사업 확장이 지연되고 있습니다. ETSI와 같은 기관이 주파수 대역의 조화를 완료할 때까지는 사업자들이 통합의 복잡성에 직면하게 되며, 규모의 경제도 훼손될 것입니다.
부문별 분석
자율형 수중정(AUV)은 현재로서는 시장의 일부에 불과하지만, 해군이 지속적인 수중 ISR 능력을 요구하고 있어 연평균 성장률(CAGR) 13.96%로 확대되고 있습니다. 2026 회계연도 미국 해군 예산에서는 초대형 AUV(자율형 수중 차량)에 2억 5,750만 달러가 배정되었으며, 호주의 ‘고스트 샤크’는 2027년까지 60일간의 연속 작동을 목표로 하고 있습니다. 그럼에도 불구하고 2025년 매출의 47.23%를 무인 지상 차량이 차지했으며, 이는 실내 순찰, 불발탄 처리(EOD) 임무, 주변 지역 수색 등 폭넓은 용도에서의 범용성을 반영하고 있습니다. 보스턴 다이내믹스의 ‘스팟’은 뉴욕시 경찰국 및 싱가포르 홈팀 과학기술청과 계약을 체결하며, 도시 및 산업 환경에 대한 적응력을 입증했습니다. 상륙 지점과 얕은 물 사이를 이동할 수 있는 하이브리드형 수륙 양용 로봇은 연안의 LNG 터미널이나 해상 풍력 발전소에서 활용되고 있지만, 60만 달러를 넘는 고가의 도입 비용이 과제로 남아 있습니다.
인도-태평양 지역 동맹국 해군들이 수중 센서망을 확대함에 따라, 수중 플랫폼용 보안 로봇 시장은 급성장할 것으로 예측됩니다. 대조적으로, 지상 차량의 성장은 도입 기반이 성숙해짐에 따라 둔화되고 있지만, 모듈식 센서 페이로드에 초점을 맞춘 업데이트 주기로 인해 견조한 교체 곡선이 유지되고 있습니다. 예측 기간 동안, 공동 영역 지휘 네트워크와의 플랫폼 간 상호 운용성은 계약 수주에서 결정적인 요인이 되어, 공급업체들이 개방형 아키텍처 표준을 채택하도록 유도할 것으로 보입니다.
2025년 매출에서 하드웨어가 차지하는 비중은 64.89%였으나, 지각, 매핑, 차량 군단 조정을 위한 소프트웨어는 연평균 성장률(CAGR) 13.91%라는 더 빠른 속도로 확대되고 있습니다. NVIDIA Jetson Orin 모듈은 현재 Shield AI, Knightscope, Anduril의 로봇에 탑재되어 있으며, 실시간 감지를 위해 200TOPS의 엣지 AI 연산 능력을 제공합니다. 정확도 향상 및 기능 추가를 목적으로 하는 무선 업그레이드에 대해 고객이 지속적인 이용료를 지불하게 됨에 따라, 보안 로봇 시장에서 소프트웨어 구독의 점유율은 상승하고 있습니다. Teledyne FLIR의 적외선 모듈은 여전히 널리 보급되어 있으며, 0럭스 환경에서도 킬로미터 단위의 감지가 가능합니다.
설치, 교육, 원격 모니터링과 같은 서비스는 여전히 시장 전체에서 차지하는 비중은 작지만 증가 추세에 있습니다. RaaS(Robot-as-a-Service)로의 전환에 따라 자산 리스크는 벤더 측으로 이전되었으며, 일회성 판매를 통한 수익보다 월정액 요금을 통한 수익이 증가하고 있습니다. ISO 13482와 같은 규정 준수 기준은 서비스 품질에 대한 기대에 영향을 미치고 있으며, 조기 도입 기업들은 자율 순찰과 사고 확인을 위한 연중무휴 24시간 체제의 인력에 의한 원격 조작을 융합할 수 있는 벤더를 높이 평가했습니다.
지역별 분석
북미는 2025년 보안 로봇 시장 점유율의 37.83%를 차지했습니다. 이는 성숙한 방위 조달, 소매 부문에서의 RaaS(Robot-as-a-Service) 전개 확대, 연방항공청(FAA)의 ‘시야 외(BVLOS)’ 운영 프레임워크에 힘입은 결과입니다. 이 지역의 지출은 초대형 자율 수중 차량을 위한 미 해군의 다년도 예산과, 외딴 지역에서 무인 지상 차량(UGV)을 활용하는 캐나다 광업 사업자들에 의해 뒷받침되고 있습니다. 멕시코는 양국 간 안보 협력을 통해 국경 지역의 드론 모니터링을 확대하고 있으며, 이로 인해 대륙 전체의 보안 로봇 시장 규모가 확대되고 있습니다. 미국 유틸리티 회사의 경쟁 실증 실험에서는 공중 로봇이 점검 비용을 40% 이상 절감할 수 있음이 입증되어, 지속적인 투자에 대한 강력한 경제적 근거가 되고 있습니다. 사이버 보안 강화 기준이 엄격해지는 가운데, 북미의 구매자들은 암호화된 명령 링크와 방해 대책 기능을 갖춘 플랫폼을 점점 더 선호하고 있습니다.
중동 시장은 2031년까지 연평균 성장률(CAGR) 14.39%를 나타낼 것으로 예측되며, 이는 모든 지역 중 가장 빠른 속도입니다. 사우디아라비아의 ‘비전 2030’은 정유시설 및 해수 담수화 플랜트의 면허 취득에 자율 순찰 요건 준수를 의무화하고 있으며, 이로 인해 내구성이 뛰어난 하이브리드 플랫폼에 대한 즉각적인 입찰이 촉발되고 있습니다. 아랍에미리트(UAE)에서는 군중 통제를 위한 무인 지상 차량과 항만 경비를 위한 해상 드론에 대한 실지 검사가 진행되고 있으며, 이는 정부의 지지를 보여주는 것으로, 민간 부문의 도입 위험을 완화하고 있습니다. 이스라엘은 수출 통제 심사가 있음에도 불구하고 인접 국가로의 정찰용 드론 수출을 계속하고 있으며, 국경 감시용 회전식 탄약 등 특수한 탑재체에 대한 수요를 높이고 있습니다.
유럽은 영국, 독일, 프랑스의 주도하에 중간 수준 시장 점유율을 유지하고 있으나, 유럽연합(EU)의 ‘인공지능법’에 따른 엄격한 생체 인식 및 개인정보 보호 규제로 인해 성장세가 둔화되고 있습니다. 독일의 보안 기술 지침에서는 지휘통제 링크에 대해 인증된 암호화를 의무화하고 있어, 이로 인해 공급업체의 자격 인증 주기가 장기화되고, 이미 입지를 다진 주요 방위 기업들이 우위를 점하고 있습니다. 아시아태평양에서는 각국 정부가 국경 경비 현대화 및 인력 부족 완화를 추진하는 가운데, 중국, 일본, 한국, 인도에서 급속한 보급이 이루어지고 있습니다. 중국만 해도 주요 지하철 시스템에 수천 대의 순찰 로봇이 배치되어 있습니다. 남미와 아프리카는 여전히 초기 단계이지만 성장의 조짐을 보이고 있으며, 브라질의 열대우림 모니터링 프로그램과 남아프리카공화국의 민간 경비 시범 사업이 초기 성장 동력을 보여주고 있습니다. 통화 제약과 수입 관세로 인해 이러한 신흥 지역에서의 당분간 도입량은 제한되고 있지만, 다자간 금융 지원과 하드웨어 가격 하락에 힘입어 예측 기간 동안 추가 수주가 예상됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the security robots market size is expected to increase from USD 17.84 billion in 2025 to USD 20.22 billion in 2026 and reach USD 37.82 billion by 2031, growing at a CAGR of 13.34% over 2026-2031.
This report is Segmented by Type (Unmanned Ground Vehicles, Autonomous Underwater Vehicles, Hybrid Amphibious Robots), Component (Hardware, Software and AI Stack, Services), End User (Defense and Military, Residential and Private Estates, and More), Application (Patrolling and Surveillance, Spying and Reconnaissance, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Security Robots Market Trends and Insights
Deployment of AI-Enabled Perception Stacks Lowering False-Alarm Rates in Critical Infrastructure
Critical-infrastructure owners are replacing rule-based motion detection with multimodal perception systems that fuse thermal, visible-light, and radar inputs. MOBOTIX field tests at European utility substations cut false positives by 70% in 2024, freeing control-room staff to investigate validated alerts. Edge inference on NVIDIA Jetson modules eliminates cloud latency and supports air-gapped defense sites. Updated 2025 guidelines from the United States Department of Energy mandate AI-verified intrusion detection at Category I nuclear facilities, accelerating purchase cycles. Insurance carriers now offer premium discounts to facilities that deploy certified AI perception, creating an economic catalyst beyond operational efficiency.
Expansion of Civilian BVLOS Drone Corridors for Security Patrols
The United States Federal Aviation Administration approved routine BVLOS operations in 2024, letting utilities, border agencies, and pipeline operators monitor linear assets without manned chase aircraft. Australia's Civil Aviation Safety Authority enacted a similar BVLOS framework in 2025, widening drone-patrol coverage for remote mining sites and offshore oil platforms. ASTM International's F3411 remote-identification standard calms public-safety concerns by requiring real-time broadcast of drone ID and telemetry. Shield AI's V-BAT platform, which won a multi-year United States Army perimeter-surveillance contract in 2025, exemplifies military validation spilling into civilian procurement. The alignment of regulation, standards, and field-proven technology is shrinking adoption timelines across energy, transportation, and defense sectors.
Fragmented Radio-Frequency Spectrum Regulations Limiting Multi-Robot Fleets
Swarm intelligence demands low-latency links, yet radio-frequency allocations vary widely. The International Telecommunication Union's 2023 conference earmarked 5.9 GHz for vehicle networking in some regions, while others dedicate it to Wi-Fi, forcing security-robot vendors to design multiple radio configurations. European Union members apply divergent rules to sub-1 GHz industrial bands, inflating certification costs and delaying cross-border rollouts. Until bodies such as ETSI finalize harmonized bands, operators will face greater integration complexity and reduced economies of scale.
Other drivers and restraints analyzed in the detailed report include:
- Mandates for Perimeter Intrusion Detection at Energy Assets
- Adoption of Robot-as-a-Service by Commercial Real-Estate Operators
- Public Backlash Against Face-Recognition Patrol Bots in Municipal Deployments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Autonomous underwater vehicles, while only a minority slice today, are expanding at a 13.96% CAGR as navies seek persistent subsurface ISR capabilities. The FY 2026 United States Navy budget earmarked USD 257.5 million for extra-large AUVs, and Australia's Ghost Shark aims for 60-day endurance by 2027. Unmanned ground vehicles nonetheless accounted for 47.23% of revenue in 2025, reflecting their versatility across indoor patrol, EOD missions, and perimeter sweeps. Boston Dynamics' Spot won contracts with the New York Police Department and Singapore's Home Team Science and Technology Agency, underscoring its adaptability to urban and industrial environments. Hybrid amphibious robots, capable of moving between beachheads and shallow waters, serve coastal LNG terminals and offshore wind farms yet face high acquisition costs exceeding USD 600,000.
The security robots market for underwater platforms is projected to grow sharply as allied Indo-Pacific navies expand undersea sensor grids. By contrast, ground-vehicle growth is moderating as installed bases mature, though refresh cycles focused on modular sensor payloads sustain a healthy replacement curve. Over the forecast period, platform interoperability with joint-domain command networks will become a decisive factor in contract awards, nudging vendors to adopt open-architecture standards.
Hardware accounted for 64.89% of 2025 revenue, but perception, mapping, and fleet-orchestration software are expanding faster at a 13.91% CAGR. NVIDIA Jetson Orin modules now ship with Shield AI, Knightscope, and Anduril robots, providing 200 TOPS of edge AI compute for real-time detection. The security robots market share held by software subscriptions is climbing as customers pay recurring fees for over-the-air upgrades that sharpen accuracy and add functionality. Teledyne FLIR's infrared modules remain ubiquitous, providing kilometer-scale detection in zero-lux environments.
Services installation, training, and remote monitoring remain a smaller but rising slice. The shift to robot-as-a-service shifts asset risk to vendors, increasing revenue from monthly fees rather than one-time sales. Compliance standards such as ISO 13482 influence service quality expectations, and early adopters reward vendors able to blend autonomous patrols with 24/7 human tele-ops for incident confirmation.
Complete Report Scope:
- By Type
- Unmanned Ground Vehicles
- Autonomous Underwater Vehicles
- Hybrid Amphibious Robots
- By Component
- Hardware
- Software and AI Stack
- Services
- By End User
- Defense and Military
- Government and Law-Enforcement
- Commercial and Industrial Facilities
- Residential and Private Estates
- By Application
- Patrolling and Surveillance
- Explosive Detection and Disposal
- Spying and Reconnaissance
- Search and Rescue Disaster Response
- Fire and Hazardous-Environment Response
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America commanded 37.83% of the security robots market share in 2025, supported by mature defense procurement, expanding retail robot-as-a-service rollouts, and the Federal Aviation Administration's beyond-visual-line-of-sight framework. Regional spending is reinforced by the United States Navy's multi-year budget for extra-large autonomous underwater vehicles and by Canadian mining operators that use unmanned ground vehicles at remote sites. Mexico is expanding drone surveillance along both borders through bilateral security assistance, broadening the addressable security robotics market across the continent. Competitive pilots at United States utility companies show that aerial robots can cut inspection costs by more than 40%, creating a strong economic case for continued investment. As cyber-hardening standards tighten, North American buyers increasingly favor platforms with encrypted command links and anti-jamming safeguards.
The Middle East is projected to grow at a 14.39% CAGR through 2031, the fastest pace among all regions. Saudi Arabia's Vision 2030 mandates tie refinery and desalination plant licenses to compliance with autonomous patrol requirements, triggering immediate tenders for rugged hybrid platforms. The United Arab Emirates has field-tested unmanned ground vehicles for crowd management and maritime drones for port security, signaling government endorsement that de-risks private-sector adoption. Israel continues to export reconnaissance drones to neighboring states despite export-control checks, adding specialized payload demand such as loitering munitions for border surveillance.
Europe maintains a mid-tier share, driven by the United Kingdom, Germany, and France, yet growth lags due to stringent biometric-privacy rules under the European Union Artificial Intelligence Act. Germany's security-technology guidelines require certified encryption for command-and-control links, extending vendor qualification cycles and favoring established defense primes. Asia Pacific shows rapid uptake in China, Japan, South Korea, and India as governments modernize border security and mitigate labor shortages; China alone has deployed thousands of patrol robots across major metro systems. South America and Africa remain nascent but rising, with Brazil's rainforest monitoring program and South Africa's private-security pilots illustrating early momentum. Currency constraints and import duties temper immediate volume in these emerging regions, but multilateral financing and falling hardware prices are expected to unlock additional orders over the forecast horizon.
- Lockheed Martin Corp.
- Northrop Grumman Corp.
- Thales SA
- BAE Systems plc
- Leonardo S.p.A.
- Elbit Systems Ltd.
- AeroVironment Inc.
- Knightscope Inc.
- SZ DJI Technology Co. Ltd.
- SMP Robotics Corp.
- Boston Dynamics Inc.
- Teledyne FLIR LLC
- Kongsberg Gruppen ASA
- QinetiQ Group plc
- RoboTex Inc.
- Recon Robotics Inc.
- Cobalt Robotics Inc.
- Shield AI, Inc.
- G4S plc
- Magos Systems
- DroneSense Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Deployment of AI-enabled perception stacks lowering false-alarm rates in critical infrastructure
- 4.2.2 Expansion of civilian BVLOS drone corridors for security patrols
- 4.2.3 Mandates for perimeter intrusion detection at energy assets
- 4.2.4 Adoption of robot-as-a-service (RaaS) by commercial real-estate operators
- 4.2.5 Accelerated demand for indoor UGVs triggered by retail shrink crisis
- 4.2.6 Growing naval budgets for autonomous underwater ISR
- 4.3 Market Restraints
- 4.3.1 Fragmented radio-frequency spectrum regulations limiting multi-robot fleets
- 4.3.2 Public backlash against face-recognition patrol bots in municipal deployments
- 4.3.3 High total cost of ruggedised all-terrain platforms for petro-chemical sites
- 4.3.4 Cyber-hardening gaps exposing C2 links to spoofing and jamming
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory and Standardisations Outlook
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Unmanned Ground Vehicles
- 5.1.2 Autonomous Underwater Vehicles
- 5.1.3 Hybrid Amphibious Robots
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software and AI Stack
- 5.2.3 Services
- 5.3 By End User
- 5.3.1 Defense and Military
- 5.3.2 Government and Law-Enforcement
- 5.3.3 Commercial and Industrial Facilities
- 5.3.4 Residential and Private Estates
- 5.4 By Application
- 5.4.1 Patrolling and Surveillance
- 5.4.2 Explosive Detection and Disposal
- 5.4.3 Spying and Reconnaissance
- 5.4.4 Search and Rescue Disaster Response
- 5.4.5 Fire and Hazardous-Environment Response
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Lockheed Martin Corp.
- 6.4.2 Northrop Grumman Corp.
- 6.4.3 Thales SA
- 6.4.4 BAE Systems plc
- 6.4.5 Leonardo S.p.A.
- 6.4.6 Elbit Systems Ltd.
- 6.4.7 AeroVironment Inc.
- 6.4.8 Knightscope Inc.
- 6.4.9 SZ DJI Technology Co. Ltd.
- 6.4.10 SMP Robotics Corp.
- 6.4.11 Boston Dynamics Inc.
- 6.4.12 Teledyne FLIR LLC
- 6.4.13 Kongsberg Gruppen ASA
- 6.4.14 QinetiQ Group plc
- 6.4.15 RoboTex Inc.
- 6.4.16 Recon Robotics Inc.
- 6.4.17 Cobalt Robotics Inc.
- 6.4.18 Shield AI, Inc.
- 6.4.19 G4S plc
- 6.4.20 Magos Systems
- 6.4.21 DroneSense Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


