

|
시장보고서
상품코드
2120637
지능형 파워 모듈(IPM) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Intelligent Power Module (IPM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
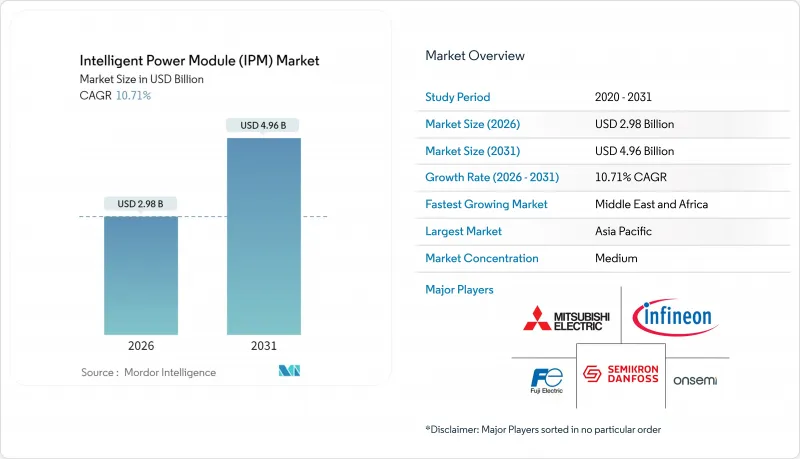
지능형 파워 모듈 시장 규모는 2026년에 29억 8,000만 달러에 이르고, 2031년까지 49억 6,000만 달러로 확대되어 CAGR은 10.71%를 나타낼 전망입니다.
본 보고서는 작동 전압(600V 이상), 파워 디바이스(IGBT 등), 기판 소재(IMS Al 등), 회로 구성(하프 브리지 등), 정격 전류(50A 이하, 기타),최종 이용 산업(소비자용 전자기기 및 가전제품, 기타), 판매 채널(OEM, 기타), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 지능형 파워 모듈(IPM) 시장 동향 및 인사이트
중국 내 고효율 전기차 인버터용 SiC 기반 IPM의 급증
2025년, 중국에서는 950만 대의 배터리 구동 전기차가 생산되었으며, 신형 모델의 약 40%가 주행 거리를 500킬로미터 이상으로 늘리기 위해 실리콘 카바이드(SiC) 모듈을 채택했습니다. BYD는 실리콘 IGBT를 기준으로 할 때와 비교해 인버터 손실을 32% 줄였다고 보고했으며, 이는 주행 거리를 25킬로미터 더 연장하는 것과 같습니다. 중국 공업정보화부가 도입한 보조금 제도에 따르면, 트랙션 인버터의 효율이 97%를 초과할 경우 차량 1대당 3,000위안이 추가로 지급됩니다. 이 목표는 현재로서는 SiC 모듈을 사용할 때만 달성 가능합니다. 1차 공급업체들은 이 인센티브를 확보하기 위해 모듈 생산 능력을 두 배로 늘렸으나, 웨이퍼 공급 부족으로 리드타임이 18주로 늘어남에 따라 SiC 수요 증가의 기세가 더욱 강해지고 있습니다.
유럽의 ‘인더스트리 4.0’ 개조에 따른 IPM 서보 드라이브의 급속한 보급
2025년, 유럽 제조업체들은 약 18만 대의 공작기계를 IPM 서보 드라이브로 업그레이드했습니다. 이는 2024년 대비 35% 증가한 수치로, 독일의 산업용 전력 평균 가격이 2020년 대비 2배로 상승한 것이 배경에 있습니다. EU 기계 규정 2023/1230에 따르면, 2026년 이후 모터의 효율이 IE4 수준을 충족해야 하며, IPM 서보 키트를 사용하면 설치 시간을 8시간에서 90분으로 단축할 수 있습니다. 지멘스는 2025년 3분기, SINAMICS 개조 패키지 수주가 전년 동기 대비 42% 급증했으며, 특히 자동차 부품 공급업체와 식품 가공업체 수요가 두드러졌습니다. 신속한 시운전과 내장형 보호 기능 덕분에 IPM 키트는 사내에 전력 전자 공학 전문 지식이 없는 소규모 기계 제조업체에게 매력적인 선택지가 되고 있습니다.
광대역 갭 웨이퍼공급 제약
2025년, 자동차 및 재생 에너지 분야의 고객들은 약 330만 장의 150mm 상당 SiC 웨이퍼를 필요로 했으나, 생산량은 280만 장에 그쳤습니다. Wolfspeed사의 새로운 200mm 생산 라인은 에피택셜 수율 문제로 인해 연말 시점에서 정격 생산 능력의 60%에 불과했습니다. ON Semiconductor사의 경우, 1200V 다이의 리드타임이 여전히 26주에 달하고, 실리콘 대체품에 비해 3배나 길어졌습니다. 이러한 공급 부족으로 인해 각 OEM 업체들은 플랫폼 출시를 최대 6개월까지 연기할 수밖에 없었으며, 일부 산업용 사용자들은 50kW 미만의 구동 시스템을 위해 다시 실리콘 IGBT로 회귀할 수밖에 없었습니다.
부문별 분석
정격 600V 이하 모듈은 지능형 전력 모듈 시장에서 2025년 42.53%라는 최고 점유율을 유지했습니다. 이 부문에서는 절연 요구 사항이 비교적 단순하기 때문에 가정용 가전, 마이크로 인버터 및 경공업용 드라이브가 주류를 이루고 있습니다. 1200V 등급은 프리미엄 전기차의 800V 배터리 팩에서 구리 사용량을 줄이기 위해 높은 DC 링크 전압이 요구됨에 따라, 연평균 성장률(CAGR) 11.26%로 가장 빠르게 성장하고 있습니다. 포르쉐의 2025년형 ‘타이칸’ 업데이트에서는 1200V SiC IPM을 채택하고 인버터의 부피를 11L에서 7.2L로 축소함으로써 전력 밀도를 48kW/L까지 향상시켰습니다. 2024년 IEC 62477-1 개정으로 인해 1,000V를 초과하는 경우의 표면 간격에 관한 비용이 증가했으나, 각 OEM 업체들은 주행 거리 및 급속 충전 성능과의 상충 관계에서 볼 때 그만한 가치가 있다고 판단하고 있습니다. 지역별로 보면, 북미의 태양광 발전 및 유럽의 옥상 태양광 발전 시스템 도입이 600V 모듈의 출하량을 견인하고 있는 반면, 중국의 EV 제조업체들은 1200V 기준으로 전환하고 있습니다.
전력망 규격과 안전 인증이 이러한 분화를 더욱 두드러지게 하고 있습니다. 미국에서는 ‘국가전기규정(NEC)’에 따라 주거용 태양광 발전 어레이의 상한이 600 V로 설정되어 있어, 저전압 IPM과 일치합니다. 반면, 유럽의 설치 업체들 사이에서는 1,200V 모듈 채택을 촉진하는 1,000V 스트링의 사용이 증가하고 있습니다. 일본의 철도 견인 시스템이나 인도의 지하철 프로젝트에서는 1,700V 및 3,300V 장치에 대한 틈새 시장이 유지되고 있지만, 그 출하량은 여전히 제한적입니다. 결과적으로, 자동차 생산 증가에 힘입어 2031년까지 1200V 부문이 지능형 전력 모듈 시장 규모에서 차지하는 비중이 확대될 것으로 확실시되고 있습니다.
IGBT 기반 IPM은 2025년에 지능형 전력 모듈 시장 점유율의 64.81%를 차지했으며, 비용이 여전히 중요한 요소인 산업용 모션 제어, HVAC 드라이브 및 가정용 가전 분야를 기반으로 하고 있습니다. 이 카테고리는 성숙한 세계 공급망을 보유하고 있으며, SiC에 비해 1암페어당 약 0.08달러의 가격 경쟁력을 누리고 있습니다. 반면, SiC MOSFET 모듈은 EV용 트랙션 인버터, 차량용 충전기, 에너지 저장용 컨버터 분야에서 스위칭 손실 및 도통 손실이 낮다는 특징을 활용하여 연평균 성장률(CAGR) 11.95%를 기록할 전망입니다. 200mm 웨이퍼의 수율이 향상됨에 따라, 2025년에는 Wolfspeed의 자동차용 매출에서 SiC IPM이 차지하는 비중이 68%에 달했습니다.
200V 미만 영역에서는 실리콘 MOSFET IPM이 서버용 전원 및 통신용 정류기 시장을 장악하고 있으며, 그 고속 역회복 특성이 높이 평가받고 있습니다. 아직 틈새 시장인 GaN FET 모듈은 노트북용 어댑터 및 48V 마일드 하이브리드 차량에 대한 수요로 인해 2025년에는 출하 대수가 두 배로 증가했습니다. 열적 여유는 플랫폼의 차별화 요소가 됩니다. SiC는 소결 은 부착을 통해 200°C의 접합부 온도를 견딜 수 있으며, 동일한 실적에서 20% 더 높은 전류를 흘릴 수 있는데, 이는 전기차(EV)의 엔진룸 내 인버터에 있어 매우 중요합니다. 기술의 추이를 보면, 실리콘 카바이드(SiC)는 프리미엄 및 자동차용 미들 티어 시장을 개척해 나가는 한편, IGBT는 비용을 중시하는 산업용 드라이브 분야에서 계속해서 확고한 입지를 유지할 것으로 예측됩니다.
직접 본딩 구리(DBC) 세라믹은 2025년 매출의 38.19%를 차지했으며, 그 내역은 Al2O3와 AlN으로 나뉩니다. Al2O3는 1제곱인치당 4.50달러로, 비용 효율을 중시하는 구동 장치용으로 사용되고 있습니다. 반면, AlN은 170 W/m-K의 열전도율 덕분에 자동차 및 철도용 모듈에서 12달러라는 가격 책정이 정당화됩니다. 실리콘 질화물(Si₃N₄) 세라믹은 AlN의 2배에 달하는 파괴 인성을 가지고 있어 열 사이클 중 기판 균열 위험을 줄여주므로, 연평균 성장률(CAGR) 11.46%로 시장을 확대되고 있습니다. 2025년 유럽 세라믹 학회의 연구에 따르면, Si3N4는 -40°C에서 150°C까지의 온도에서 1,000회의 열 사이클을 균열 없이 견딜 수 있음이 입증되었습니다.
절연 금속 기판은 중량이 중요한 100 A 미만의 모듈에 사용되며, 능동형 금속 브레이징 구리는 200 W/m-K의 열전도율이 필요한 1700 V 철도용 디바이스에 사용됩니다. 교세라의 2025년형 Si3N4 기판은 AlN보다 40% 저렴한 비용으로 90 W/m-K를 실현하여, 자동차 분야의 양산 채택을 목표로 하고 있습니다. 세라믹 기판의 기생 정전용량이 낮기 때문에 공통 모드 노이즈를 8 dB 저감할 수 있어, CISPR 25 준수가 용이해집니다. 일본과 독일 기업들이 첨단 세라믹 시장을 독점하고 있어 공급 안정성이 과제로 대두되고 있으며, 모듈 제조업체들은 장기 공급 계약을 체결하고 있습니다.
지역별 분석
아시아태평양은 중국의 BEV 생산 대수 950만 대 및 인도의 태양광 발전 설비 신규 도입량 18GW에 힘입어 2025년 매출의 46.74%를 차지했습니다. BYD나 NIO와 같은 중국 브랜드는 중국 공업정보화부(MIIT)의 효율 보조금 수혜 자격을 얻기 위해 SiC IPM에 의존하고 있는 반면, 일본의 미쓰비시전기, 후지전기, ROHM은 고전압 패키징 분야에서 기술적 리더십을 유지하고 있습니다. 한국의 반도체 팹에서는 2025년에 클린룸 자동화가 현대화되면서 고정밀 서보 드라이브에 대한 수요가 발생했습니다. 또한, 동남아시아의 가전제품 조립 공장에서는 수백만 개의 600V 모듈이 탑재되었습니다.
북미에서는 ‘인플레이션 감축법(IRA)’의 세액 공제 및 미국 에너지부(DOE)의 대기 전력 제한을 배경으로 꾸준한 성장 궤도를 유지하고 있습니다. 미국에서는 2025년에 32GW 규모의 유틸리티급 태양광 발전이 도입되었으며, 그중 60%가 텍사스주와 캘리포니아주에서 설치되었고, 1700V IPM을 핵심으로 한 1500V 스트링 인버터가 채택되었습니다. 캐나다에서는 각 주의 규제 조치에 힘입어 BEV 판매 대수가 전년 대비 48% 증가했습니다. 또한 멕시코에서 OEM의 파워트레인 현지화로 인해 새로운 공급망 거점이 생겨나고 있습니다. 전력 비용의 급등에 따라 HVAC 및 산업용 드라이브 분야의 개조 수요가 증가하고 있습니다.
유럽에서는 ‘기계 규정’ 및 800V EV 플랫폼으로의 전환이 진행되고 있습니다. 독일은 자동차 및 식품 가공 분야의 서보 드라이브 업그레이드를 통해 도입 대수에서 선두를 달리고 있습니다. 한편, 영국의 해상 풍력 발전용 터빈에서는 15MW 컨버터에 1700V IPM이 채택되고 있습니다. 프랑스와 이탈리아는 철도 견인 시스템의 현대화에 주력하고 있으며, 기존 사이리스터 시스템을 유지보수 주기를 단축할 수 있는 IGBT IPM으로 교체하고 있습니다. 스페인에서는 유리한 고정가격임베디드제도(FIT)에 힘입어 태양광 발전 설비의 증설이 촉진되고 있으며, 1,500V 인버터가 선호되고 있습니다.
중동은 2031년까지 12.45%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 사우디아라비아는 2025년에 8GW 규모의 태양광 발전 설비를 가동했습니다. 여기에는 1700V 모듈을 기반으로 한 중앙 인버터를 채택한 2GW 규모의 수다일 발전소가 포함됩니다. 또한 UAE는 1200V SiC IPM으로 구동되는 플래그십 태양광 발전 단지에 1.2GWh 규모의 에너지 저장 설비를 계획하고 있습니다. 튀르키예에서는 가전제품 수출이 서보 드라이브 수요를 견인하고 있으며, 리야드의 지하철망은 2030년 이후 수익성이 높은 교체 시장을 촉진할 것입니다.
남미와 아프리카는 여전히 비교적 소규모이지만 성장을 지속하고 있습니다. 브라질의 자동차 공장 및 식품 가공업체들은 현대화 촉진 조치의 일환으로 IPM 서보 드라이브를 도입하고 있으며, 아르헨티나의 신규 재생 에너지 입찰에서는 2027년부터 1,500V 스트링 인버터가 도입될 예정입니다. 또한, 남아프리카공화국의 광산에서는 디젤 연료 사용을 줄이기 위해 운반용 트럭의 구동 시스템을 개조하고 있습니다. 나이지리아의 태양광 발전과 디젤을 병용하는 상업시설은 600V 마이크로 인버터를 위한 틈새 시장을 창출하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the intelligent power module market size reached USD 2.98 billion in 2026 and is projected to climb to USD 4.96 billion by 2031, advancing at a 10.71% CAGR.
This report is Segmented by Operational Voltage (600 V, and More), Power Device (IGBT, and More), Substrate Material (IMS Al, and More), Circuit Configuration (Half-Bridge, and More), Current Rating (Up To 50 A, and More), End-Use Industry (Consumer Electronics and Home Appliances, and More), Sales Channel (OEM, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Intelligent Power Module (IPM) Market Trends and Insights
Surge in SiC-Based IPMs for High-Efficiency EV Inverters in China
China produced 9.5 million battery-electric vehicles in 2025, and roughly 40% of new models adopted silicon-carbide modules to boost range beyond 500 kilometers. BYD reported a 32% inverter-loss reduction against silicon IGBT baselines, translating to another 25 kilometers of driving range. Subsidies introduced by the Chinese Ministry of Industry and Information Technology pay an extra CNY 3,000 per vehicle when traction inverters exceed 97% efficiency, a target currently feasible only with SiC modules. Tier-one suppliers doubled module capacity to chase the incentive, yet wafer shortages stretched lead times to 18 weeks, reinforcing SiC's pull-through momentum.
Rapid Adoption of IPM Servo Drives in European Industry 4.0 Retrofits
European manufacturers upgraded about 180,000 machine tools with IPM servo drives in 2025, a 35% jump over 2024, as the average German industrial power price doubled versus 2020. The EU Machinery Regulation 2023/1230 obliges IE4-level motor efficiency from 2026 onward, and IPM servo kits slash installation time from eight hours to 90 minutes. Siemens recorded a 42% year-on-year order spike for its SINAMICS retrofit packages in Q3 2025, with strongest traction among automotive suppliers and food processors. Quick commissioning and embedded protections make IPM kits attractive for small machine builders lacking in-house power-electronics expertise.
Wide-Band-Gap Wafer Supply Constraints
Automotive and renewable-energy customers required about 3.3 million 150 mm-equivalent SiC wafers in 2025, yet output reached only 2.8 million. Wolfspeed's new 200 mm line hit 60% of nameplate capacity by year-end because of epitaxial yield challenges. ON Semiconductor still saw 26-week lead times for 1200 V dies, three times longer than silicon alternatives. The shortage forced OEMs to postpone platform launches by up to six months and pushed some industrial users back toward silicon IGBTs for sub-50 kW drives.
Other drivers and restraints analyzed in the detailed report include:
- On-Board Charger Integration Trend Among Tier-1 Automotive OEMs
- Regulatory Push for Ultra-Low-Standby Home Appliances in North America
- Thermal-Interface Reliability Beyond 1200 V Ratings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Modules rated up to 600 V maintained the highest 2025 share, at 42.53% of the intelligent power module market. Residential appliances, micro-inverters, and light industrial drives dominate this bracket, benefiting from simpler insulation needs. The 1200 V class is rising fastest, with an 11.26% CAGR, as 800 V battery packs in premium EVs call for higher DC-link voltage to cut copper mass. Porsche's 2025 Taycan update relies on 1200 V SiC IPMs to shrink inverter volume from 11 L to 7.2 L, boosting power density to 48 kW/L. IEC 62477-1 revisions in 2024 increased creepage-distance costs above 1000 V, yet OEMs find the trade-off worthwhile for range and fast-charge performance. In regional terms, North American solar and European rooftop PV installations guide 600 V module volumes, while Chinese EV makers shift towards 1200 V benchmarks.
Grid standards and safety certifications accentuate the split. The National Electrical Code caps U.S. residential PV arrays at 600 V, aligning with lower-voltage IPMs, whereas European installers increasingly use 1000 V strings that entice 1200 V module adoption. Japanese rail-traction and Indian metro projects preserve a niche for 1700 V and 3300 V devices, though these remain volume-limited. In net effect, rising automotive production ensures that the 1200 V segment captures a growing fraction of the intelligent power module market size through 2031.
IGBT-based IPMs supplied 64.81% of intelligent power module market share in 2025, anchored in industrial motion control, HVAC drives, and consumer appliances where cost remains pivotal. The class enjoys a mature, global supply chain and an approximate USD 0.08 per-ampere price edge over SiC. Yet SiC MOSFET modules will post an 11.95% CAGR, drawing on their lower switching and conduction losses in EV traction inverters, on-board chargers, and energy-storage converters. Wolfspeed's automotive revenue mix reached 68% for SiC IPMs in 2025 as 200 mm wafer yields improved.
Below 200 V, silicon MOSFET IPMs dominate server power supplies and telecom rectifiers, prized for fast reverse-recovery behaviour. GaN FET modules, still niche, doubled shipments in 2025 on laptop adapters and 48 V mild-hybrid vehicles. Thermal headroom differentiates platforms: SiC sustains 200 °C junction temperatures with sintered-silver attaches, enabling 20% higher current in the same footprint, critical for under-hood EV inverters. The technology trajectory suggests silicon-carbide will carve out the premium and automotive middle-tier, while IGBT remains entrenched in cost-sensitive industrial drives.
Direct-bonded-copper (DBC) ceramic commanded 38.19% of 2025 revenue, split between Al2O3 and AlN. Al2O3 serves cost-sensitive drives at USD 4.50 per sq in., whereas AlN's 170 W/m-K thermal conductivity justifies its USD 12.00 price in automotive and rail modules. Silicon-nitride (Si3N4) ceramic is advancing at an 11.46% CAGR because its fracture toughness doubles that of AlN, cutting substrate crack risk during thermal cycling. A 2025 European Ceramic Society study proved Si3N4 survives 1,000 cycles from -40 °C to 150 °C without cracking.
Insulated-metal substrates serve modules below 100 A where weight matters, and active-metal-brazed copper targets 1700 V rail devices demanding 200 W/m-K conductivity. Kyocera's 2025 Si3N4 substrate offers 90 W/m-K at 40% less cost than AlN, positioning it for volume automotive adoption. Lower parasitic capacitance on ceramic substrates trims common-mode noise by 8 dB, easing CISPR 25 compliance. Supply security is emerging as an issue because Japanese and German firms dominate advanced ceramics, prompting module makers to ink long-term offtake contracts.
Complete Report Scope:
- By Operational Voltage
- 600 V Modules
- 650-900 V Modules
- 1,200 V Modules
- 1,700 V and Above Modules
- By Power Device
- IGBT-Based IPMs
- Si MOSFET-Based IPMs
- SiC MOSFET-Based IPMs
- GaN FET-Based IPMs
- By Substrate Material
- Insulated Metal Substrate (Al)
- DBC Ceramic (AlN / Al?O?)
- AMB Copper
- Si3N4 Ceramic
- By Circuit Configuration
- Half-Bridge
- Six-Pack
- Seven-Pack and Others
- By Current Rating
- Up to 50 A
- 51-100 A
- Above 100 A
- By End-Use Industry
- Consumer Electronics and Home Appliances
- Industrial Automation and Servo Drives
- Electric and Hybrid Vehicles
- Renewable Energy and ESS
- Rail Traction and Infrastructure
- HVAC and Building Systems
- Others End-User Industry
- By Sales Channel
- OEM
- Aftermarket / Retrofit
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific generated 46.74% of 2025 revenue, buoyed by China's 9.5 million-unit BEV output and India's 18 GW solar additions. Chinese brands such as BYD and NIO rely on SiC IPMs to qualify for the MIIT efficiency subsidy, while Japan's Mitsubishi Electric, Fuji Electric, and ROHM maintain technology leadership in high-voltage packaging. South Korea's semiconductor fabs modernized cleanroom automation in 2025, generating demand for high-precision servo drives, and Southeast Asia's appliance assembly plants integrated millions of 600 V modules.
North America keeps a steady growth path on the back of Inflation Reduction Act credits and DOE standby-power limits. The United States installed 32 GW of utility-scale solar in 2025, 60% in Texas and California, using 1500 V string inverters built around 1700 V IPMs. Canadian BEV sales grew 48% year-on-year, aided by provincial mandates, and Mexico's OEM powertrain localization is opening new supply-chain nodes. Retrofit demand in HVAC and industrial drives intensifies as electricity costs escalate.
Europe advances under the Machinery Regulation and the shift to 800 V EV platforms. Germany leads volume, with servo-drive upgrades in automotive and food processing sectors, while the United Kingdom's offshore wind turbines employ 1700 V IPMs in 15 MW converters. France and Italy focus on rail-traction modernization, replacing legacy thyristor systems with IGBT IPMs that cut maintenance intervals. Spain's favourable feed-in tariffs stimulate PV capacity additions that favour 1500 V inverters.
The Middle East will log the quickest CAGR at 12.45% through 2031. Saudi Arabia commissioned 8 GW of solar in 2025, including the 2 GW Sudair plant that deploys central inverters based on 1700 V modules, and the UAE plans 1.2 GWh of storage at its flagship solar park to be supported by 1200 V SiC IPMs. Turkey's appliance exports drive servo-drive demand, and Riyadh's metro network will foster a lucrative replacement market starting in 2030.
South America and Africa remain comparatively small but rising. Brazil's automotive plants and food processors adopt IPM servo drives under modernization incentives, Argentina's new renewable auctions will deploy 1500 V string inverters from 2027, and South Africa's mines retrofit haul-truck drives to curb diesel usage. Nigeria's hybrid solar-diesel commercial installations create a niche market for 600 V micro-inverters.
- Mitsubishi Electric Corporation
- Infineon Technologies AG
- Fuji Electric Co., Ltd.
- ON Semiconductor Corporation
- Semikron Danfoss GmbH & Co. KG
- ROHM Co., Ltd.
- Vincotech GmbH
- STMicroelectronics N.V.
- Powerex Inc.
- Toshiba Electronic Devices & Storage Corp.
- Wolfspeed, Inc.
- Microchip Technology Inc. (Microsemi)
- Renesas Electronics Corporation
- Littelfuse, Inc. (IXYS)
- Dynex Semiconductor Ltd.
- CRRC Times Electric Co., Ltd.
- StarPower Semiconductor Ltd.
- Hitachi Energy Ltd.
- Navitas Semiconductor Corp.
- Alpha & Omega Semiconductor Ltd.
- Sanken Electric Co., Ltd.
- BYD Semiconductor Co., Ltd.
- Nanjing SilverMicro Electronics Co., Ltd.
- Vishay Intertechnology Inc.
- Danfoss Silicon Power GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in SiC-based IPMs for High-Efficiency EV Inverters in China
- 4.2.2 Rapid Adoption of IPM Servo Drives in European Industry 4.0 Retrofits
- 4.2.3 On-Board Charger Integration Trend among Tier-1 Automotive OEMs
- 4.2.4 Regulatory Push for Ultra-Low-Stand-By Home Appliances in North America
- 4.2.5 Solar Micro-/Nano-Inverter Build-Outs Boosting 600 V IPM Demand in the US
- 4.2.6 Digital-Twin-Enabled Predictive Thermal Management for High-Power IPMs
- 4.3 Market Restraints
- 4.3.1 Wide-Band-Gap Wafer Supply Constraints
- 4.3.2 Thermal-Interface Reliability Beyond 1 200 V Ratings
- 4.3.3 High Automotive AEC-Q101 Validation Costs for Module Makers
- 4.3.4 IP Infringement and Price Erosion by Low-End Asian Vendors
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Operational Voltage
- 5.1.1 600 V Modules
- 5.1.2 650-900 V Modules
- 5.1.3 1,200 V Modules
- 5.1.4 1,700 V and Above Modules
- 5.2 By Power Device
- 5.2.1 IGBT-Based IPMs
- 5.2.2 Si MOSFET-Based IPMs
- 5.2.3 SiC MOSFET-Based IPMs
- 5.2.4 GaN FET-Based IPMs
- 5.3 By Substrate Material
- 5.3.1 Insulated Metal Substrate (Al)
- 5.3.2 DBC Ceramic (AlN / Al?O?)
- 5.3.3 AMB Copper
- 5.3.4 Si3N4 Ceramic
- 5.4 By Circuit Configuration
- 5.4.1 Half-Bridge
- 5.4.2 Six-Pack
- 5.4.3 Seven-Pack and Others
- 5.5 By Current Rating
- 5.5.1 Up to 50 A
- 5.5.2 51-100 A
- 5.5.3 Above 100 A
- 5.6 By End-Use Industry
- 5.6.1 Consumer Electronics and Home Appliances
- 5.6.2 Industrial Automation and Servo Drives
- 5.6.3 Electric and Hybrid Vehicles
- 5.6.4 Renewable Energy and ESS
- 5.6.5 Rail Traction and Infrastructure
- 5.6.6 HVAC and Building Systems
- 5.6.7 Others End-User Industry
- 5.7 By Sales Channel
- 5.7.1 OEM
- 5.7.2 Aftermarket / Retrofit
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Russia
- 5.8.3.7 Rest of Europe
- 5.8.4 Asia Pacific
- 5.8.4.1 China
- 5.8.4.2 Japan
- 5.8.4.3 India
- 5.8.4.4 South Korea
- 5.8.4.5 South-East Asia
- 5.8.4.6 Rest of Asia Pacific
- 5.8.5 Middle East
- 5.8.5.1 Saudi Arabia
- 5.8.5.2 United Arab Emirates
- 5.8.5.3 Turkey
- 5.8.5.4 Rest of Middle East
- 5.8.6 Africa
- 5.8.6.1 South Africa
- 5.8.6.2 Nigeria
- 5.8.6.3 Rest of Africa
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share for Key Companies, Products and Services, Recent Developments)
- 6.4.1 Mitsubishi Electric Corporation
- 6.4.2 Infineon Technologies AG
- 6.4.3 Fuji Electric Co., Ltd.
- 6.4.4 ON Semiconductor Corporation
- 6.4.5 Semikron Danfoss GmbH & Co. KG
- 6.4.6 ROHM Co., Ltd.
- 6.4.7 Vincotech GmbH
- 6.4.8 STMicroelectronics N.V.
- 6.4.9 Powerex Inc.
- 6.4.10 Toshiba Electronic Devices & Storage Corp.
- 6.4.11 Wolfspeed, Inc.
- 6.4.12 Microchip Technology Inc. (Microsemi)
- 6.4.13 Renesas Electronics Corporation
- 6.4.14 Littelfuse, Inc. (IXYS)
- 6.4.15 Dynex Semiconductor Ltd.
- 6.4.16 CRRC Times Electric Co., Ltd.
- 6.4.17 StarPower Semiconductor Ltd.
- 6.4.18 Hitachi Energy Ltd.
- 6.4.19 Navitas Semiconductor Corp.
- 6.4.20 Alpha & Omega Semiconductor Ltd.
- 6.4.21 Sanken Electric Co., Ltd.
- 6.4.22 BYD Semiconductor Co., Ltd.
- 6.4.23 Nanjing SilverMicro Electronics Co., Ltd.
- 6.4.24 Vishay Intertechnology Inc.
- 6.4.25 Danfoss Silicon Power GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


