|
시장보고서
상품코드
2120640
염료 및 안료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Dyes And Pigments - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
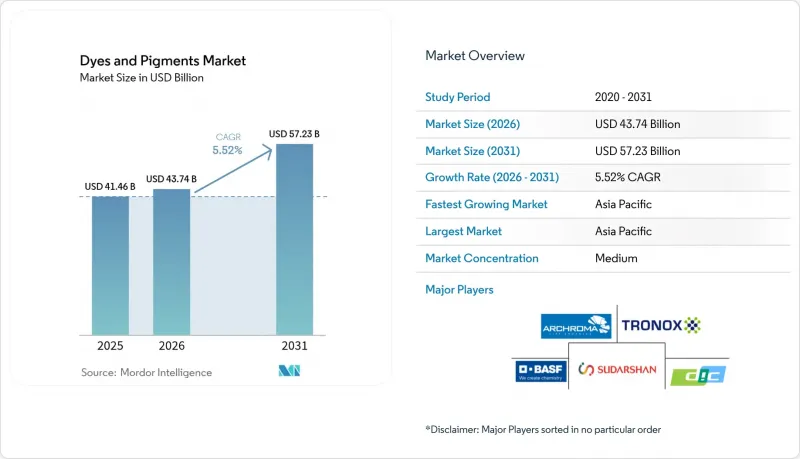
염료 및 안료 시장 규모는 2025년에 414억 6,000만 달러로 평가되었습니다. 2026년 437억 4,000만 달러에서 2031년까지 572억 3,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 5.52%를 나타낼 전망입니다.
본 보고서는 제품 유형(염료 및 안료), 원료(합성 및 천연/바이오 유래), 제형(분말, 과립, 액체 분산액), 최종 사용자 산업(페인트 및 코팅, 섬유, 인쇄 잉크 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 염료 및 안료 시장 동향 및 인사이트
아시아태평양의 페인트 및 코팅 분야 수요 증가
아시아태평양의 인프라 구축 계획이 건축용 및 보호용 코팅 분야의 이산화티타늄 및 산화철 안료 수요를 견인하고 있습니다. 중국의 ‘2035년 저탄소 가이드라인’ 등 수성 제제를 우선시하는 지역적 정책 이니셔티브에 따라 용제계 분산액으로부터의 대체가 가속화되고 있습니다. LANXESS는 산화철 생산 능력을 확대하고, 사양 수립자가 친환경 라벨 요건을 충족하는 데 도움이 되는 환경 제품 선언(EPD)을 발표했습니다. 다국적 도료 제조업체들은 지역 배합 제조업체와 제휴하여 색상 기준을 현지화함으로써 규제 준수와 시장 진입을 가속화하고 있습니다.
섬유 생산 확대
중국, 인도, 베트남에서의 섬유 생산 능력 확대는 반응성 염료 및 분산 염료에 대한 수요를 재편하고 있으며, 특히 흡습·항균 가공이 적용된 기능성 섬유에서 이러한 경향이 두드러집니다. 인도는 2025년까지 섬유 제품 수출액을 450억 달러로 늘리겠다는 목표를 세우고, 방적 공장에 물 소비량을 줄이고 색 영역을 확대하는 디지털 인쇄 플랫폼 도입을 장려했습니다. 아치로마(Archiroma)사의 헌츠맨 텍스타일 이펙츠(Huntsman Textile Effects)사 인수를 통해 42개국에 걸쳐 있는 5,000명의 직원이 통합되었으며, 고성능 염료와 지속가능성 인증을 겸비한 제품 포트폴리오가 구축되었습니다. 패스트 패션 브랜드들이 환경 발자국을 공개하는 가운데, 염료 회수 시스템이나 콜드 패드 배치 처리와 같은 순환형 이니셔티브가 주목을 받고 있습니다. 라미와 면 직물을 위한 에너지 절약형 염색법에 대한 연구를 통해 염색 균일성과 착색률이 지속적으로 향상되고 있습니다.
중금속 안료에 대한 REACH 및 EPA의 엄격한 규제
코팅 및 플라스틱 분야에서는 카드뮴, 6가 크롬, 납 화합물에 대해 사실상 제로 허용이 요구되고 있으며, REACH에서는 폴리머 매트릭스 내 카드뮴 함량을 0.01 wt%로 제한하고 있습니다. 2024년에 시행될 문신 잉크 관련 규제로 인해 프탈로시아닌 블루 15 및 그린 7을 포함한 4,000종 이상의 물질이 규제 대상에 추가됨에 따라, 배합 개발자들은 유기계 대체재를 찾아야 하는 상황에 직면해 있습니다. 미국의 ‘화장품 규제 현대화법’은 FDA에 안전성 데이터 제출을 요청하거나 안료 함유 제품의 리콜을 명령할 수 있는 권한을 부여하고 있어, 규정 준수 비용 증가를 초래하고 있습니다. 크롬이 함유되지 않은 황색 계열 안료나 바나듐산 비스무트 대체품을 제품 포트폴리오에 보유한 기업들은 규제 대상 시장에서 점유율을 확대되고 있습니다. 시장이 더 안전한 화학 물질로 전환되는 가운데, 중금속 안료 제조업체들은 판매량 감소와 이익률 압박에 직면하고 있습니다.
부문별 분석
염료는 2025년 전 세계 염료 및 안료 시장의 56.63%를 차지했으며, 분자 수준에서의 착색 분산이 필요한 섬유, 가죽, 종이 워크플로우로의 확산에 힘입어 2031년까지 연평균 성장률(CAGR) 5.76%로 성장할 전망입니다. 반응성 염료는 강한 공유 결합으로 인해 면 및 라미 용도에서 주류를 이루고 있으며, 선명한 색상의 의류 제품에 대한 전자상거래 수요를 뒷받침하고 있습니다. 아조 염료의 보급은 현재 아동복 분야에서 제한되고 있으며, 덴마크의 규제에 따라 방향족 아민 함유량이 중량비 0.003%로 제한되고 있습니다.
염료의 하위 부문에서는 형광 광학 증백제부터 레이저 마킹이 가능한 플라스틱용 근적외선 흡수제에 이르기까지 특수 용도 제품 범위가 확대되고 있습니다. 한편, 안료는 내식성 및 열 제어 기능이 요구되는 기능성 코팅 분야에서 지속적으로 시장 점유율을 확대되고 있습니다. 나노기술을 활용한 하이브리드 착색제가 수용성 염료와 같은 선명함과 안료에 버금가는 내광성을 겸비하게 됨에 따라, 이 두 카테고리 간의 기술적 경계는 점차 모호해지고 있습니다. ‘크래들 투 크래들(C2C)’ 인증을 목표로 하는 브랜드들은 금속을 포함하지 않는 배합을 선호하여 채택하고 있으며, 이는 학제 간 혁신을 촉진하고 있습니다.
합성 착색제는 2025년에 총 생산량의 84.55%를 차지했으며, 예측 가능한 색조 강도, 폭넓은 색역, 그리고 높은 비용 효율성 덕분에 계속해서 주도적인 위치를 유지하고 있습니다. 석유 유래 중간체는 패스트 패션 및 포장 가공업체를 위한 적시(JIT) 물류에 대응하는 대규모 생산을 뒷받침하고 있습니다. 천연 유래 대체품은 클린 라벨을 선호하는 소비자 경향과 규제상의 인센티브에 힘입어 연평균 성장률(CAGR) 6.74%로 성장하고 있습니다.
미생물 발효 기술의 발전으로 폐기 글리세롤로부터 베타레인 및 카로티노이드를 생산할 수 있게 되어 공급 안정성이 향상되고 있습니다. 합성 색소 제조업체들은 재생 가능 자원을 활용한 제조 공정에 투자하여 위험을 분산시키고 있으며, 리그노셀룰로오스 유래 바이오 방향족 화합물에 주력하고 있습니다. 바이오 인디고 및 안트라퀴논 중간체의 파일럿 라인은 현재 검증 단계에 접어들었습니다. 이해관계자들은 EU의 탄소 국경 조정 메커니즘 도입을 예상하고 있으며, 이에 따라 탄소 발자국이 큰 수입품에 벌금이 부과될 가능성이 있어 저탄소 합성 경로가 경제적으로 매력적일 것으로 전망됩니다.
지역별 분석
아시아태평양은 염료 및 안료 시장을 독점하고 있으며, 2025년에는 46.88%의 점유율을 차지했고 2031년까지 연평균 성장률(CAGR) 6.05%로 성장할 전망입니다. 2025년까지 섬유 산업의 자동화율을 70%로 끌어올리겠다는 중국의 계획이 배치 주기를 단축하고 물 사용량을 줄이는 디지털 대응형 액체 염료의 수주를 뒷받침하고 있습니다. VOXCO Pigments사의 크롬 옐로우 및 몰리브덴산 오렌지 생산 확대(6,000만 달러) 등, 이 지역의 안료 공급에 대한 투자는 수출 시장을 목표로 하며 전 세계 고객에 대한 리드타임 단축을 목표로 하고 있습니다.
유럽은 엄격한 규제가 있음에도 불구하고 전략적 중요성을 유지하고 있습니다. 중국의 이산화티타늄에 대한 반덤핑 관세로 인해 조달처가 재검토되면서 프랑스, 독일, 네덜란드의 국내 생산자들에게 비즈니스 기회가 생기고 있습니다. 독일은 여전히 산화철의 중요한 공급원, Tronox사가 네덜란드 공장을 가동 중단한 것은 에너지 집약적 공정에서 발생하는 비용 압박을 반영하고 있습니다.
북미 시장은 성숙기에 접어들었음에도 활기를 띠고 있으며, EPA의 VOC 기준이 수성 배합으로의 전환을 촉진하고 있습니다. 랑세스(LANXESS)는 리튬 철 인산염 양극재용 중간체인 인산철을 판매하며, 안료의 용도를 배터리 분야로 확대되고 있습니다.
남미는 브라질의 산화철 생산에 의존하고 있으며, 이는 국내 건설 수요를 뒷받침하고 있습니다. 중동 및 아프리카에서는 사우디아라비아의 NEOM과 같은 메가 프로젝트에 따른 안료 수요 증가 외에도, 기후 변화에 강한 파사드용 도료 수요도 나타나고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the dyes and Pigments Market size was valued at USD 41.46 billion in 2025 and estimated to grow from USD 43.74 billion in 2026 to reach USD 57.23 billion by 2031, at a CAGR of 5.52% during the forecast period (2026-2031).
This report is Segmented by Product Type (Dyes and Pigments), Source (Synthetic and Natural/Bio-based), Formulation (Powder, Granular, and Liquid Dispersion), End-User Industry (Paints and Coatings, Textiles, Printing Inks, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Dyes And Pigments Market Trends and Insights
Growing Demand from Paints and Coatings in APAC
Asia-Pacific infrastructure pipelines are propelling titanium dioxide and iron oxide pigment volumes in architectural and protective coatings. Regional policy initiatives that prioritize waterborne formulations, such as China's 2035 low-carbon guideline, accelerate substitutions away from solvent-borne dispersions. LANXESS expanded iron-oxide capacities and published Environmental Product Declarations that help specifiers meet ecolabel requirements. Multinational paint makers partner with regional formulators to localize color standards, ensuring regulatory alignment and faster market entry.
Expanding Textile Production
Textile capacity additions in China, India, and Vietnam are reshaping demand for reactive and disperse dyes, particularly for technical textiles with moisture-management and antimicrobial finishes. India targets USD 45 billion in textile exports by 2025, encouraging mills to adopt digital printing platforms that cut water consumption and broaden color gamut. Archroma's acquisition of Huntsman Textile Effects merged 5,000 employees across 42 countries, creating a portfolio that combines high-performance dyes with sustainability certifications. Circularity initiatives, including dye reclamation systems and Cold Pad-Batch processing, are gaining traction as fast-fashion brands disclose environmental footprints. Research into energy-saving dyeing routes for ramie and cotton fabrics continues to improve levelness and fixation rates.
Stringent REACH and EPA Restrictions on Heavy-Metal Pigments
Cadmium, chromium VI, and lead compounds face near-zero tolerance in coatings and plastics, with REACH limiting cadmium in polymer matrices to 0.01 wt%. Tattoo-ink rules effective in 2024 widened the scope to more than 4,000 substances, including phthalocyanine Blue 15 and Green 7, pushing formulators to explore organic alternatives. The US Modernization of Cosmetics Regulation Act grants the FDA the ability to request safety data and recall pigment-containing products, elevating compliance costs. Companies holding portfolios of chromium-free yellows or bismuth vanadate substitutes are gaining share in regulated markets. Heavy-metal pigment producers confront shrinking volumes and margin compression as markets pivot to safer chemistries.
Other drivers and restraints analyzed in the detailed report include:
- Infrastructure-Led Rise in Construction Pigments
- Shift Toward Low-VOC, Water-Borne Formulations
- Volatile Crude-Derived Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dyes control 56.63% of the global dyes and pigments market in 2025 and will advance at 5.76% CAGR to 2031, fueled by penetrating textile, leather, and paper workflows that need molecular-level color dispersion. Reactive dyes dominate cotton and ramie applications due to strong covalent bonding, supporting e-commerce demand for vibrant apparel. Azo dye proliferation is now curbed in children's wear, with Danish rules capping aromatic amines at 0.003 wt%.
The dyes subsegment showcases a widening specialty range, from fluorescent optical brighteners to near-infrared absorbers for laser-markable plastics. Meanwhile, pigments keep gaining ground in functional coatings that demand corrosion resistance or thermal control. Technological barriers between the two categories blur as nano-engineered hybrid colorants deliver soluble-like brilliance with pigment-level lightfastness. Brands pursuing cradle-to-cradle certification gravitate toward metal-free recipes, stimulating cross-disciplinary innovation.
Synthetic colorants represented 84.55% of total volume in 2025 and continue to lead due to predictable shade strength, wide color coverage, and cost efficiency. Petroleum-based intermediates support high-scale production that meets just-in-time logistics for fast-fashion and packaging converters. Natural alternatives grow at a 6.74% CAGR, buoyed by consumer preference for clean labels and regulatory incentives.
Microbial fermentation advances enable production of betalains and carotenoids from waste glycerol, enhancing supply security. Synthetic producers are hedging with renewable routes, investing in bio-aromatics derived from lignocellulose. Pilot lines for bio-based indigo and anthraquinone intermediates are entering validation stages. Stakeholders anticipate carbon-border adjustment mechanisms in the EU that could penalize high-footprint imports, making low-carbon synthetic routes financially attractive.
Complete Report Scope:
- By Product Type
- Dyes
- Reactive
- Disperse
- Vat
- Sulfur
- Acid
- Azo
- Pigments
- Organic Pigments
- Inorganic Pigments
- Dyes
- By Source
- Synthetic
- Natural / Bio-based
- By Formulation
- Powder
- Granular
- Liquid Dispersion
- By End-user Industry
- Paints and Coatings
- Textiles
- Printing Inks
- Plastics
- Other End-user Industries (Construction Materials, Paper and Pulp, Cosmetics and Personal Care)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominates the dyes and pigments market, holding 46.88% share in 2025 and expanding at 6.05% CAGR through 2031. China's program to reach 70% textile automation by 2025 fuels orders for digitally compatible liquid dyes that shorten batch cycles and cut water usage. Regional pigment supply investments, such as VOXCO Pigments' USD 60 million expansion in chrome yellow and molybdate orange, target export markets and reduce lead times for global customers.
Europe retains strategic significance despite stringent regulation. Anti-dumping duties on Chinese titanium dioxide recalibrate sourcing, offering openings for domestic producers in France, Germany, and the Netherlands. Germany remains a critical source of iron oxides, while Tronox's idling of a Dutch plant reflects cost pressures in energy-intensive processes.
North America is mature yet dynamic, with EPA VOC standards catalyzing waterborne formulation upgrades. LANXESS markets iron-phosphate intermediates for lithium iron phosphate cathodes, expanding pigment reach into battery applications.
South America leans on Brazil's iron oxide output, supporting domestic construction. The Middle East and Africa observe pigment demand growth from megaprojects such as Saudi Arabia's NEOM, combined with coatings demand for climate-resilient facades.
- Altana AG
- BASF
- Archroma
- artience Co., Ltd.
- Bodal Chemicals Ltd
- Cathay Industries
- DIC Corporation
- Flint Group
- ISHIHARA SANGYO KAISHA, LTD.
- Kronos Worldwide, Inc.
- Lanxess
- Meghmani Group
- Merck KGaA
- Sudarshan Chemical Industries Limited
- Tronox Holdings plc
- Venator Materials PLC
- Vibrantz
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand from Paints and Coatings in APAC
- 4.2.2 Expanding Textile Production
- 4.2.3 Infrastructure-Led Rise in Construction Pigments (Cement and Roof Tiles)
- 4.2.4 Shift Toward Low-VOC, Water-Borne Formulations
- 4.2.5 Adoption of Dye-Infused Filaments for Additive Manufacturing
- 4.3 Market Restraints
- 4.3.1 Stringent REACH and EPA Restrictions on Heavy-Metal Pigments
- 4.3.2 Volatile Crude-Derived Feedstock Prices
- 4.3.3 Ban on Certain Azo Dyes in Children's Apparel
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Dyes
- 5.1.1.1 Reactive
- 5.1.1.2 Disperse
- 5.1.1.3 Vat
- 5.1.1.4 Sulfur
- 5.1.1.5 Acid
- 5.1.1.6 Azo
- 5.1.2 Pigments
- 5.1.2.1 Organic Pigments
- 5.1.2.2 Inorganic Pigments
- 5.1.1 Dyes
- 5.2 By Source
- 5.2.1 Synthetic
- 5.2.2 Natural / Bio-based
- 5.3 By Formulation
- 5.3.1 Powder
- 5.3.2 Granular
- 5.3.3 Liquid Dispersion
- 5.4 By End-user Industry
- 5.4.1 Paints and Coatings
- 5.4.2 Textiles
- 5.4.3 Printing Inks
- 5.4.4 Plastics
- 5.4.5 Other End-user Industries (Construction Materials, Paper and Pulp, Cosmetics and Personal Care)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Altana AG
- 6.4.2 BASF
- 6.4.3 Archroma
- 6.4.4 artience Co., Ltd.
- 6.4.5 Bodal Chemicals Ltd
- 6.4.6 Cathay Industries
- 6.4.7 DIC Corporation
- 6.4.8 Flint Group
- 6.4.9 ISHIHARA SANGYO KAISHA, LTD.
- 6.4.10 Kronos Worldwide, Inc.
- 6.4.11 Lanxess
- 6.4.12 Meghmani Group
- 6.4.13 Merck KGaA
- 6.4.14 Sudarshan Chemical Industries Limited
- 6.4.15 Tronox Holdings plc
- 6.4.16 Venator Materials PLC
- 6.4.17 Vibrantz
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment