

|
시장보고서
상품코드
2120661
실험실용 화학제품 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Laboratory Chemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
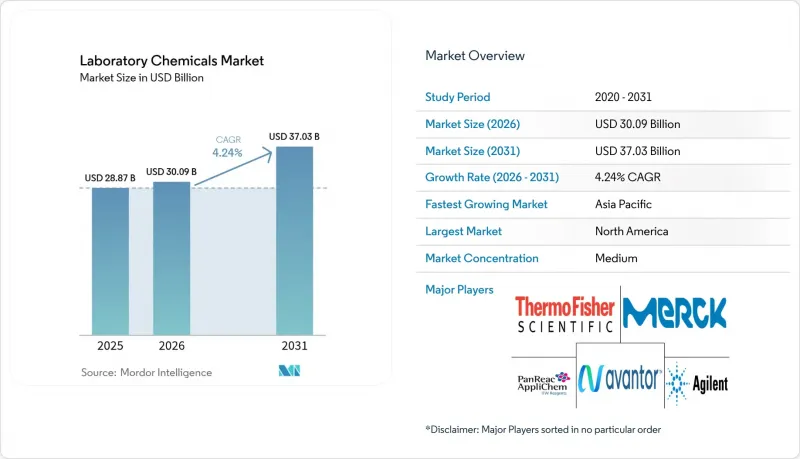
에 의하면, 2026년 실험용 화학제품 시장 규모는 300억 9,000만 달러로 추정되며, 2025년 288억 7,000만 달러에서 2031년에는 370억 3,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR)은 4.24%를 기록할 전망입니다.
본 보고서는 유형별(생화학, 분자생물학, 사이토카인 및 케모카인 검사, 탄수화물 분석, 면역화학, 기타), 용도별(학술 및 교육, 산업, 정부, 의료 및 제약), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 실험실용 화학약품 시장 동향 및 인사이트
생명과학 및 제약 부문의 연구개발비 증가
주요 제약 기업들은 2024년 매출의 15-20%를 신약 개발 프로그램에 할당하고 있으며, 정밀 생물학을 뒷받침하는 크로마토그래피용 용매, 효소 기질 및 동위원소 표지 표준 물질에 대한 수요가 지속되고 있습니다. 대학은 공공 자금의 변동으로부터 연구 파이프라인을 보호하기 위한 산학 협력 및 재단의 보조금을 활용하여 계속해서 활발한 구매자로 남아 있습니다. 로봇식 액체 핸들러와 AI를 활용한 실험 설계를 기반으로 하는 ‘자율형 실험실’의 확대로 인해, 시약 소비는 바코드가 부착된 메타데이터가 기재된 즉시 사용 가능한 액체 재고로 전환되고 있습니다. 자동화에 대응한 포장 및 디지털 문서화를 제공할 수 있는 공급업체는 수주량이 증가하는 추세를 보이고 있습니다. 이러한 동향은 선순환을 만들어내고 있습니다. 즉, 더 풍부한 데이터가 더 우수한 알고리즘을 만들어내고, 이는 다시 처리 능력과 시약 수요를 더욱 높이고 있는 것입니다.
전 세계 바이오의약품 생산 능력 확대
2024년에 전 세계 바이오의약품 생산 능력이 20% 이상 급증함에 따라, GMP 환경에서 사용되는 공정 버퍼, 크로마토그래피 수지 및 방출 시험용 표준 물질에 큰 호재가 되었습니다. 위탁 개발·제조 기관(CDMO)은 고객 전반에 걸쳐 시약 수요를 증가시키는 플랫폼 공정에 의존하고 있으며, 이로 인해 예측 가능한 판매 전망이 확고해졌습니다. 아시아태평양은 경쟁력 있는 비용 구조가 다국적 기업과 바이오시밀러 기업 모두를 끌어들이고 있어, 새로운 유형 자산 투자의 상당 부분을 차지하고 있습니다. ‘품질 설계(QbD)’ 프레임워크에 기반한 연속 제조 패러다임은 배치의 무결성을 보장하는 실시간 분석 시약에 대한 수요를 강화하고 있습니다. 검증된 PAT(공정 분석 기술)용 화학 시약을 공급하는 업체들은 장기적인 상업적 공급에 연계된 다년 계약을 확보하고 있습니다.
주요 용매 및 산의 원자재 가격 변동
원유 및 나프타의 벤치마크 가격의 급격한 변동은 아세톤, 아세토니트릴, 황산공급에 파급되어 소비량이 많은 연구소의 예산 계획을 불안정하게 만들고 있습니다. 입찰 주도형 고객들이 가격 전가에 저항함에 따라, 공급업체들은 이익률 압박 위험에 직면하고 있습니다. 동아시아 내 특수 화학제품 생산의 지리적 집중은 해상 운송의 병목 현상이나 무역 마찰이 발생할 경우 그 영향을 더욱 확대시킵니다. 이중 조달 전략은 위험을 상쇄하지만, 인증 취득 비용이 발생하여 일정이 지연되고 운전 자금이 묶이게 됩니다. 이미 보조금 불확실성에 대처하고 있는 학술 기관은 단기적으로 가장 심각한 영향을 받고 있습니다.
부문 분석
2025년, 생화학 분야는 실험실용 화학약품 시장 점유율의 27.12%를 차지하며, 효소 반응 속도론, 대사체학 및 단백질체학 규모의 분석에서 그 매우 중요한 역할을 부각시켰습니다. 단백질체학 연구실에서는 고순도 완충액, 환원제 및 질량 분석용 등급의 용매가 일상적으로 소비되고 있으며, 이들은 고가 제품군에 속합니다. 이 부문에서 제약사가 바이오의약품 파이프라인을 확대함에 따라, 의료 및 제약용 시약의 실험실용 화학약품 시장 규모는 2031년까지 연평균 성장률(CAGR) 4.93%로 확대될 것으로 예측됩니다.
분자생물학용 시약은 고정밀도를 중시하는 중합효소 및 뉴클레오티드 혼합액이 필요한 CRISPR 및 차세대 염기서열 분석 워크플로우에 힘입어, 그 시장 규모는 분자생물학용 시약에 근소한 차이로 뒤를 잇고 있습니다. 세포·조직 배양 배지는 첨단 치료에 관한 규제 지침에 따라 무혈청의 화학적으로 정의된 제제로 전환되고 있습니다. 환경 시험용 화학 약품은 정부의 오염 물질 스크리닝 의무화가 확대됨에 따라 꾸준한 수요 증가세를 이어가고 있습니다. 이러한 하위 분야 전반에 걸쳐 공급업체들은 데이터가 충실한 분석 증명서를 제공하고, 고객의 재고 비용을 최소화할 수 있는 유연한 로트 크기를 제안함으로써 시장 점유율을 확보하고 있습니다.
지역별 분석
북미는 GSK의 300억 달러, 일라이 릴리의 50억 달러에 달하는 미국 제조 시설 투자에 힘입어 2025년 매출의 29.60%를 차지했습니다. FDA 및 EPA와 같은 연방 기관들은 규정 준수 및 조사 요건을 충족하기 위해 지속적으로 시약을 발주하고 있습니다. 캐나다의 특수 화학 물질 생태계는 지역 공급의 회복력을 높여 북미 대륙 전체의 실험용 화학 물질 시장 기반을 더욱 공고히 하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 4.66%로 가장 빠른 성장 궤도에 올라 있습니다. 중국이 생명공학 분야의 자급자족을 추진하고 있어 크로마토그래피용 지지체, 세포 배양용 보충제, 분석용 표준 물질의 대량 조달이 촉진되고 있습니다. 인도는 API(원료의약품) 분야에서의 리더십을 활용하여, 검증용 시약을 국내에서 조달하는 동시에 잉여분을 전 세계로 수출하고 있습니다. 일본과 한국은 하이엔드 재료 과학 및 유전체학 분야 수요를 견인하고 있으며, 추적 가능성과 자동화와의 호환성을 중시하는 정교한 구매자층을 뒷받침하고 있습니다. 따라서 아시아태평양의 실험용 화학물질 시장 규모는 수량 측면과 부가가치가 높은 제품 구성이라는 두 가지 측면에서 혜택을 받고 있습니다.
유럽은 엄격한 환경 규제와 독일, 스위스를 중심으로 한 선진적인 제약 클러스터에 힘입어 견고한 기반을 유지하고 있습니다. 공공 자금을 통한 저탄소 실험실 운영 지원이 확대됨에 따라, 그린 케미스트리의 도입이 가속화되고 있습니다. 브렉시트로 인해 일부 주문 거점이 영국에서 EU 본토로 이전되었으나, 대서양 횡단 및 유럽 내 무역 흐름은 대체로 유지되고 있습니다. 남미, 중동 및 아프리카 등 신흥 지역에서는 공중보건 연구소 설립이 점점 더 활발해지고 있으며, 현재 시장 점유율은 여전히 소규모이지만 향후 점진적인 성장이 예상됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the laboratory chemicals market size in 2026 is estimated at USD 30.09 billion, growing from 2025 value of USD 28.87 billion with 2031 projections showing USD 37.03 billion, growing at 4.24% CAGR over 2026-2031.
This report is Segmented by Type (Biochemistry, Molecular Biology, Cytokine and Chemokine Testing, Carbohydrate Analysis, Immunochemistry, and Other Types), Application (Academia/Educational, Industrial, Government, and Healthcare/Pharmaceutical), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Laboratory Chemicals Market Trends and Insights
Growing R&D Spending in Life-Science and Pharma Sectors
Major drugmakers allocated 15-20% of 2024 revenue to discovery programs, sustaining demand for chromatographic solvents, enzyme substrates, and isotope-labeled standards that underpin precision biology. Universities remain active buyers by leveraging industry alliances and foundation grants that shield research pipelines from public-funding volatility. The expansion of self-driving laboratories, built on robotic liquid handlers and AI-guided experiment design, tilts reagent consumption toward ready-to-use liquid stocks carrying bar-coded metadata. Suppliers able to deliver automation-compatible packaging and digital documentation are seeing elevated order volumes. The trend establishes a flywheel: richer data feeds better algorithms, which in turn heightens throughput and reagent requirements.
Expanding Biopharmaceutical Manufacturing Capacity Worldwide
A greater than 20% jump in global biologics capacity during 2024 opened a sizeable tailwind for process buffers, chromatography resins, and release-testing standards used in GMP environments. Contract development and manufacturing organizations rely on platform processes that multiply reagent needs across clients, cementing a predictable offtake profile. Asia-Pacific captures the lion's share of new bricks-and-mortar investment as competitive cost structures attract multinationals and biosimilar firms alike. Continuous-manufacturing paradigms rooted in quality-by-design frameworks intensify demand for real-time analytical reagents that ensure batch integrity. Suppliers offering validated PAT chemistries are securing multi-year agreements tied to long-term commercial supply.
Volatility in Feedstock Prices for Key Solvents and Acids
Sharp swings in crude-oil and naphtha benchmarks cascade into acetone, acetonitrile, and sulfuric-acid supply, destabilizing budgeting for high-consumption labs. Suppliers risk margin compression as tender-driven customers resist price pass-throughs. Geographic clustering of specialty chemical production in East Asia magnifies exposure when maritime bottlenecks or trade friction arise. Dual-sourcing strategies offset risk but incur qualification costs that stretch timelines and tie up working capital. Academic institutions, already coping with grant uncertainties, feel the pinch most acutely in the near term.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for High-Purity Reagents in Environmental and Food Testing
- Digitization and AI-Enabled High-Throughput "Lab-of-the-Future" Initiatives
- Stringent Hazardous-Waste and Chemical-Safety Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biochemistry captured 27.12% of laboratory chemicals market share in 2025, underscoring its pivotal role in enzyme kinetics, metabolomics, and proteome-scale analyses. Proteomics labs routinely consume high-purity buffers, reducing agents, and mass-spectrometry grade solvents that command price premiums. Within this category, the laboratory chemicals market size for healthcare/pharmaceutical reagents is expected to compound at 4.93% CAGR through 2031 as drug manufacturers upscale biologics pipelines.
Molecular-biology reagents trail closely behind, buoyed by CRISPR and next-generation sequencing workflows that require fidelity-centric polymerases and nucleotide mixes. Cell/tissue-culture media are shifting toward serum-free, chemically defined formulations, aligning with regulatory guidance for advanced therapies. Environmental-testing chemicals continue steady uptake as governments widen contaminant-screening mandates. Across these subdomains, suppliers win share by offering data-rich certificates of analysis and flexible batch sizes that minimize customer inventory costs.
Complete Report Scope:
- By Type
- Biochemistry
- Molecular Biology
- Cytokine and Chemokine Testing
- Carbohydrate Analysis
- Immunochemistry
- Cell/Tissue Culture
- Environmental Testing
- Other Types
- By Application
- Academia/Educational
- Industrial
- Government
- Healthcare (Pharmaceutical)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America anchored 29.60% of 2025 revenue, fueled by GSK's USD 30 billion and Eli Lilly's USD 5 billion investments in U.S. manufacturing facilities. Federal bodies such as the FDA and EPA sustain consistent reagent requisitions for compliance and research mandates. Canada's specialty-chemicals ecosystem adds regional supply resilience, further entrenching the laboratory chemicals market across the continent.
Asia-Pacific is on course for the most rapid expansion at a 4.66% CAGR. China's push for biotech self-sufficiency spurs heavy procurement of chromatography media, cell-culture supplements, and analytical standards. India leverages its API leadership to source validation reagents domestically while exporting surplus supply worldwide. Japan and South Korea contribute high-end materials science and genomics demand, underpinning a sophisticated buyer base that prizes traceability and automation compatibility. The laboratory chemicals market size in Asia-Pacific thus benefits from both volume and value-added product mixes.
Europe retains a robust foothold underpinned by strict environmental legislation and advanced pharma clusters centered in Germany and Switzerland. Green-chemistry adoption is accelerating as public funding channels reward low-carbon lab operations. Brexit has nudged some ordering hubs from the UK to mainland EU, but trans-Atlantic and intra-European trade flows remain largely intact. Emerging regions such as South America and the Middle East and Africa are increasingly commissioning public-health labs, signaling future incremental uplift even though current shares stay modest.
- Agilent Technologies
- Avantor, Inc.
- BD Biosciences
- Beckman Coulter, Inc.
- Biosynth
- Calibre Scientific
- Carlo Erba Reagents
- FUJIFILM Wako Pure Chemical Corporation
- ITW Reagents Division
- Merck KGaA
- New England Biolabs
- PerkinElmer
- Promega Corporation
- Sartorius AG
- Shanghai Bid Pharmaceutical Technology Co., Ltd.
- Shimadzu Corporation
- Thermo Fisher Scientific Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing R&D Spending in Life-Science and Pharma Sectors
- 4.2.2 Expanding Biopharmaceutical Manufacturing Capacity Worldwide
- 4.2.3 Rising Demand for High-Purity Reagents in Environmental and Food Testing
- 4.2.4 Digitization and AI-Enabled High-Throughput "Lab-of-the-Future" Initiatives
- 4.2.5 Shift Toward Sustainable/Green Solvents and Bio-Based Reagents
- 4.3 Market Restraints
- 4.3.1 Volatility in Feedstock Prices for Key Solvents and Acids
- 4.3.2 Stringent Hazardous-Waste and Chemical-Safety Regulations
- 4.3.3 Availability of Functional Substitute Kits and Automation Platforms
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Biochemistry
- 5.1.2 Molecular Biology
- 5.1.3 Cytokine and Chemokine Testing
- 5.1.4 Carbohydrate Analysis
- 5.1.5 Immunochemistry
- 5.1.6 Cell/Tissue Culture
- 5.1.7 Environmental Testing
- 5.1.8 Other Types
- 5.2 By Application
- 5.2.1 Academia/Educational
- 5.2.2 Industrial
- 5.2.3 Government
- 5.2.4 Healthcare (Pharmaceutical)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 NORDIC Countries
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Agilent Technologies
- 6.4.2 Avantor, Inc.
- 6.4.3 BD Biosciences
- 6.4.4 Beckman Coulter, Inc.
- 6.4.5 Biosynth
- 6.4.6 Calibre Scientific
- 6.4.7 Carlo Erba Reagents
- 6.4.8 FUJIFILM Wako Pure Chemical Corporation
- 6.4.9 ITW Reagents Division
- 6.4.10 Merck KGaA
- 6.4.11 New England Biolabs
- 6.4.12 PerkinElmer
- 6.4.13 Promega Corporation
- 6.4.14 Sartorius AG
- 6.4.15 Shanghai Bid Pharmaceutical Technology Co., Ltd.
- 6.4.16 Shimadzu Corporation
- 6.4.17 Thermo Fisher Scientific Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


