

|
시장보고서
상품코드
2120672
항공기 전기화 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)More Electric Aircraft - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
항공기 전기화(MEA) 시장 규모는 2026년에 62억 9,000만 달러로 추정되고 2025년 56억 2,000만 달러에서 성장하여 2031년에는 110억 4,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 11.92%가 될 것으로 전망됩니다.
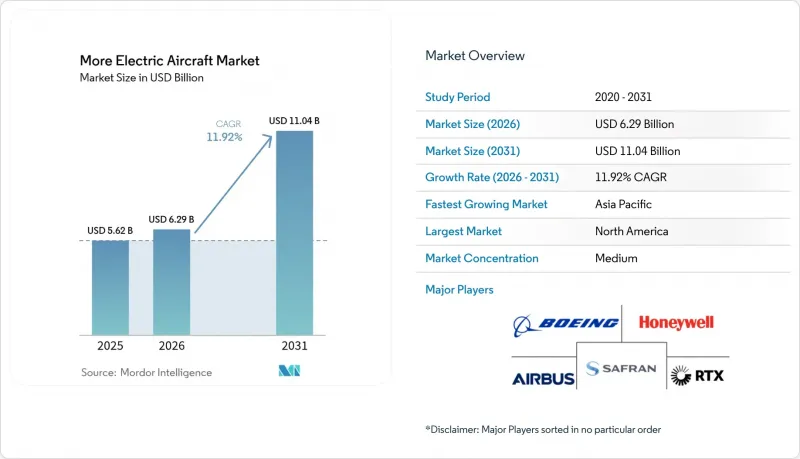
본 보고서는 항공기 유형(민간 항공, 군용 항공 등), 플랫폼(고정익 및 회전익), 시스템(발전·관리 시스템, 작동 시스템, 열 관리 시스템 등), 최종 사용자(OEM 및 애프터마켓), 지역(북미, 유럽, 아시아태평양 등)별로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 항공기 전기화 시장 동향 및 인사이트
연료 소비 및 CO₂ 배출 감축을 위한 전동화 추진
연료비는 항공사 운영비의 20%-30%를 차지하고 있으며, 배기 가스 감축의 이점 외에도 kW급 전기 파워트레인은 경제적으로도 매력적입니다. GE 에어로스페이스의 ‘CLEEN III’ 실증 프로젝트에서는 90kW 스타터-제너레이터가 채택되어, 이를 통해 블리드 에어 배관이 불필요해지고 터보팬 코어를 최적 추력 설정에 가까운 상태로 운전할 수 있게 되었습니다. 787에 탑재된 콜린스 에어로스페이스(Collins Aerospace)사의 블리드리스 환경 제어 팩은 전기 서브시스템이 이산화탄소 배출량을 줄이면서 정비 계획을 용이하게 하는 구조를 보여줍니다. 이를 통해 항공사는 점검 주기를 예측 가능하게 하고, 유체 누출을 줄이며, 예정에 없던 지상 대기 시간을 단축할 수 있습니다. 이러한 경제적 이점과 규제 준수 이점이 결합되어, 모든 기체 유형에 대한 전기화 신규 탑재 및 개조 프로그램에 대한 지속적인 투자가 촉진되고 있습니다.
전 세계 배출 규제 강화
현재 자발적인 서약 대신 법적 구속력이 있는 규정이 도입되고 있습니다. 미국 연방항공청(FAA)은 2024년 4월부터 시행된 연료 효율 기준을 채택하여, 신형 제트기의 좌석 킬로미터당 최대 연료 소비량을 규정하고 있습니다. 유럽의 ‘ReFuelEU’ 지침은 항공사들에게 2030년까지 6%, 2050년까지 70%의 지속가능한 항공연료 사용을 의무화하고 있으며, 이로 인해 드롭인 연료와 전기 부스터를 결합한 하이브리드 전기 아키텍처의 도입이 촉진되고 있습니다. ICAO(국제민간항공기구)의 세계 상쇄 제도에서는 검증 가능한 배출 감축이 요구되고 있으며, 엔진 미세 조정만으로는 단기적인 규제 준수 기간을 충족할 수 없기 때문에 OEM 각사는 전기 시스템 통합을 가속화할 수밖에 없는 상황입니다. 예를 들어, 에어버스는 규제 프레임워크에 부합하기 위해 2035년까지 제로 배출 상용기 모델을 실현하겠다는 목표를 공개적으로 내걸고 있습니다.
고전압 인증의 장벽
전기 추진 시스템은 일반적으로 직류 1,000V를 초과하지만, 기존의 규제는 270V 아키텍처에 중점을 두어 왔습니다. FAA는 새로운 아크 고장 및 절연 파괴 모드에 대처하기 위해 BETA Technologies사의 H500A에 대해 특별 조건을 발행했습니다. FAA와 EASA 간의 규제 수립 방향이 다르기 때문에 전 세계적인 인증 절차가 복잡해지고 있으며, 개발자들은 여러 가지 최악의 시나리오를 상정하여 설계할 수밖에 없는 상황입니다. 보잉의 B777-9는 기존 전력 공급 없이 운항하는 것과 관련하여 여전히 추가적인 심사를 받고 있으며, 전압 범위가 확대되면 기존 프로그램이 인증 지연에 직면하게 될 것이라는 점이 부각되고 있습니다. 이러한 불확실성은 개발 주기를 길게 만들고, 예산을 부풀리며, 전기화가 진행되고 있는 항공기 시장의 주요 성장률을 둔화시키고 있습니다.
부문별 분석
2025년, 항공사들이 유지보수 비용을 절감하기 위해 유압 시스템을 분산형 전기 서브시스템으로 교체한 결과, 상업용 항공기 부문은 항공기 전기화 시장의 39.12%를 차지했습니다. 항공사들은 라인 교체 가능 유닛(LRU)이 유체 구동식이 아닌 솔리드 스테이트 방식일 경우, 수명 주기 비용을 예측하기 쉬워진다는 점을 강조하고 있습니다. 한편, eVTOL 부문은 2031년까지 연평균 성장률(CAGR) 15.38%를 기록하며, 도시 간 에어택시 운항에 대한 투자자들의 신뢰가 높아지고 있음을 보여줍니다. Joby사와 Archer사의 인증 이정표를 계기로 인식이 ‘컨셉’에서 ‘가까운 시일 내 서비스 개시’로 전환되면서, 지역 항공 사업자들의 기체 주문이 잇따르고 있습니다. 군사 프로그램에서는 주로 레이더 반사 단면적 감소를 목적으로 전기 구동 방식이 채택되고 있으며, 비즈니스 항공 분야에서는 기내 소음 및 공항 내 배기가스 감축을 목적으로 도입이 진행되고 있습니다.
이러한 부문 간의 분화는 전동화가 진행되는 항공기 시장이 기존 수요 지표를 재검토할 가능성을 시사합니다. JSX가 2028년 이후 300대 이상의 하이브리드 전기식 지역 항공기를 도입할 계획은 지역 항공사가 이를 실현할 수 있게 되면 구형 기종을 건너뛰고 기종 교체를 추진할 것임을 보여줍니다. 수주 가속화로 인해 개발 리드타임이 단축되면서, 공급망은 반도체를 eVTOL 스타트업에 우선적으로 배정할 수밖에 없는 상황에 처해 있습니다. 그 결과, 고사이클 배터리용 셀 생산이 제한적이라는 점이 기존 나로우바디 항공기 개조 과정에서 병목 현상으로 작용하고 있습니다. 하지만 기체 전체를 교체하는 것이 경제적으로 어려운 경우, 구형 상업용 항공기용 개조 키트가 보급되고 있어, 이를 통해 항공기 등급 전반에 걸쳐 균형 잡힌 수주 구성이 확보되고 있습니다.
2025년 시점에서 고정익기 설계는 모어 일렉트릭 에어크래프트(More Electric Aircraft) 시장 규모의 63.10%를 차지했습니다. 이는 B787이나 A350과 같은 인증된 레퍼런스 프로그램이 실제 운항에서 전동식 환경 제어를 입증한 덕분입니다. 이러한 사례들은 협폭기 기단에 대한 고전압 개조를 승인할 때 규제 당국과 리스 회사에 안도감을 주고 있습니다. 한편, 회전익기 및 파워리프트기의 개념은 직접 드라이브 방식의 전동 모터가 가져다주는 호버링 효율의 비약적인 향상에 힘입어 연평균 성장률(CAGR) 12.18%로 확대되고 있습니다.
DARPA의 XRQ-73 하이브리드 전기 드론은 로터에 의한 양력과 고정익에 의한 순항을 융합하여, 파워 일렉트로닉스가 수직 이착륙기(VTOL)에 스텔스성과 항속 거리를 제공함을 입증하고 있습니다. 일렉트라(Electra)사의 단거리 이륙형 지역 항공기 실증기는 이러한 경계를 더욱 모호하게 만들며, 미래의 분류 체계가 날개의 평면 형상이 아닌 임무 프로파일에 초점을 맞출 것임을 시사하고 있습니다. 회전익 항공기 프로그램에서는 기어박스의 윤활 라인이 필요 없습니다는 점도 활용하여, 중량과 유지보수 부담을 경감하고 있습니다. 이러한 범주 경계의 모호화는 통일된 인증 체계 구축을 촉진하고, 기존과는 다른 레이아웃 시장 진입을 원활하게 할 뿐만 아니라, 전동화가 진행되고 있는 항공기 시장에서 플랫폼의 다양성을 유지하는 데 기여할 것입니다.
지역별 분석
북미는 2025년 지출의 34.96%를 차지했습니다. 이는 국방 예산이 메가와트급 실증기를 지원하고, FAA가 전기 추진 인증을 위한 초기 로드맵을 제시했기 때문입니다. 미국의 확고한 1차 공급업체들은 연구시설, 시험 장비, 인재 파이프라인이 하나로 통합된 성숙한 생태계의 기반이 되고 있습니다. NASA의 ‘전동 파워트레인 비행 실증 프로그램’에서는 GE와 보잉의 엔지니어들이 협력하여 2027년까지 지역 항공기 플랫폼에서 하이브리드 추진 시스템의 비행 시험을 실시할 예정이며, 이는 이 분야의 지역적 모멘텀을 더욱 강화하고 있습니다.
유럽은 청정 항공 보조금과 공항 탈탄소화 정책에 힘입어 금액 기준 2위를 차지하고 있습니다. GOLIAT 및 EcoPulse와 같은 EU 프로젝트는 공공 자금을 액체 수소 취급, 초전도 케이블 및 하이브리드 전기식 비행 시험에 투입하고 있습니다. EASA와 FAA의 규제 조화를 통해 eVTOL의 대서양 횡단 인증이 가속화되어, 이중 등록 사업자 시장 출시 기간이 단축되고 있습니다. 다만, 유럽공급업체들은 반도체 조달 과정에서 통화 강세로 인한 비용 상승에 직면해 있으며, 웨이퍼 확보를 위해 아시아 파운드리와의 합작 사업이 진행되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 12.24%로 가장 높은 성장률을 기록하고 있습니다. 중국 민용항공국은 eVTOL을 이용한 물류 및 여객 셔틀 운행을 위해 전용 저고도 공역을 지정하고, 상업화 일정을 앞당기고 있습니다. 중국은 2030년까지 1조 위안 규모의 일반 항공 산업을 구축할 계획을 세우고 있으며, 보조금 투입과 규제 명확화를 통해 해외 Tier 2 공급업체를 유치하려 하고 있습니다. 일본과 한국은 엑스포와 같은 행사를 위한 도시 지역 실증 비행에 주력하고 있으며, 본격적인 인증 취득에 앞서 그 성과를 선보이고 있습니다. 그러나 공항 측의 준비는 뒤처지고 있습니다. 인도는 UDAN 연결 계획에 따라 단거리 노선용 전기식 지역 터보프롭기 도입을 검토하고 있습니다. 이 지역의 다양한 시장 진입은 배터리, 모터, 항공전자기기 공급업체들에게 지속적인 수주로 이어지고 있으며, 아시아태평양이 전동화가 진행되는 항공기 시장에서 주요 판매량 견인 역할을 계속할 것임을 보장하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the more electric aircraft (MEA) market size in 2026 is estimated at USD 6.29 billion, growing from 2025 value of USD 5.62 billion with 2031 projections showing USD 11.04 billion, growing at 11.92% CAGR over 2026-2031.
This report is Segmented by Aircraft Type (Commercial Aviation, Military Aviation, and More), Platform (Fixed Wing and Rotary Wing), System (Power Generation and Management, Actuation System, Thermal Management System, and More), End-User (OEM and Aftermarket), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global More Electric Aircraft Market Trends and Insights
Electrification Drive to Cut Fuel Burn and CO2
Fuel accounts for 20%-30% of airline operating expense, making kilowatt-class electric powertrains economically attractive in addition to their emission benefits. GE Aerospace's CLEEN III demonstration delivers a 90 kW starter-generator that removes bleed-air plumbing and lets turbofan cores run closer to optimum thrust settings. Collins Aerospace's bleed-less environmental control pack on the 787 illustrates how electrical subsystems lower carbon output while easing maintenance planning. Airlines thus gain predictable inspection intervals and fewer fluid leaks, reducing unscheduled ground time. These dual financial and compliance rewards reinforce continuous investment in electrified line-fit and retrofit programs across fleet types.
Global Emission Regulations Tightening
Binding rules now supplant voluntary pledges. The US Federal Aviation Administration (FAA) adopted fuel-efficiency standards effective April 2024 that set maximum fuel per seat-kilometer for new jets. The European "ReFuelEU" mandate obliges carriers to uplift 6% sustainable aviation fuel by 2030 and 70% by 2050, prompting hybrid-electric architectures that blend drop-in fuels with electric boost. ICAO's global offset scheme requires verifiable emission cuts, forcing OEMs to accelerate electrical integration because incremental engine tweaks cannot satisfy near-term compliance windows. Airbus, for example, publicly targets a zero-emission commercial model by 2035 to stay within regulatory guardrails.
High-Voltage Certification Hurdles
Electric propulsion routinely exceeds 1,000 V DC, yet historical regulations focus on 270 V architectures. The FAA issued special conditions for BETA Technologies' H500A to address new arc-fault and insulation-breakdown modes. Divergent rule-making between the FAA and EASA complicates global validation, obliging developers to engineer for multiple worst-case scenarios. Boeing's B777-9 still faces additional scrutiny for operations without conventional electrical power, underscoring how legacy programs experience certification delays when voltage envelopes widen. These uncertainties lengthen development cycles and inflate budgets, tempering the headline growth rate of the more electric aircraft market.
Other drivers and restraints analyzed in the detailed report include:
- High-Power Motors and SiC/GaN Electronics
- Solid-State Batteries Enable Power-Spike Loads
- Thermal Reliability of Dense Power Modules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Commercial airframes contributed 39.12% of the more electric aircraft market in 2025 as airlines replaced hydraulics with distributed electrical subsystems to curb maintenance outlay. Carriers highlight predictable life-cycle costs when line-replaceable units are solid-state rather than fluid-powered. Meanwhile, the eVTOL category posts a 15.38% CAGR to 2031, signaling rising investor confidence in city-pair air-taxi operations. Certification milestones by Joby and Archer shifted perceptions from concept to near-term service, unlocking fleet orders from regional operators. Military programs adopt electric actuation chiefly for radar-signature reduction, while business aviation follows for lower cabin noise and airport emissions.
The segment divergence suggests the more electric aircraft market may recalibrate traditional demand metrics. JSX's plan to accept more than 300 hybrid-electric regional aircraft after 2028 illustrates how regional carriers will leapfrog older fleets when viable. Accelerated orders shrink developmental lead times, forcing supply chains to allocate semiconductors first to eVTOL founders. Limited cell production for high-cycle batteries thus becomes a gating item for legacy narrow-body retrofits. Still, retrofit kits for older commercial types gain traction where full fleet renewal is financially prohibitive, ensuring a balanced order mix across aircraft classes.
Fixed-wing designs held 63.10% of the more electric aircraft market size in 2025, thanks to certified reference programs such as the B787 and A350 demonstrating electric environmental control in revenue service. These examples reassure regulators and lessors when approving high-voltage retrofits to narrow-body fleets. At the same time, rotary-wing and powered-lift concepts expand at 12.18% CAGR, buoyed by the step-change in hover efficiency that direct-drive electric motors deliver.
DARPA's XRQ-73 hybrid-electric drone blends rotor lift with fixed-wing cruise and showcases how power electronics endow vertical assets with stealth and endurance. Electra's short-takeoff regional demonstrator collapses the divide further, hinting that future taxonomy will focus on mission profile rather than wing planform. Rotary programs also exploit the absence of gearbox lubrication lines, cutting weight and maintenance. This blurring of categories could spur unified certification frameworks, smoothing entry for unconventional layouts and sustaining platform diversity inside the more electric aircraft market.
Complete Report Scope:
- By Aircraft Type
- Commercial Aviation
- Military Aviation
- Business and General Aviation
- Unmanned Aerial Vehicles (UAV)
- Urban Air Mobility/eVTOL
- By Platform
- Fixed Wing
- Rotary Wing
- By System
- Power Generation and Management
- Electric Power Generation
- Power Conversion
- Power Distribution
- Actuation System
- Flight Control Actuation
- Landing Gear Actuation
- Thermal Management System
- Engine Start System
- Environmental Control System
- Others
- Power Generation and Management
- By End-user
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 34.96% of 2025 spending as defense budgets backed megawatt demonstrators and the FAA provided early pathways for electric propulsion certification. Established Tier-1 suppliers in the United States anchor a mature ecosystem that co-locates research laboratories, test rigs, and human-capital pipelines. NASA's Electrified Powertrain Flight Demonstration program pairs GE and Boeing engineers to flight-test hybrid propulsion on a regional platform by 2027, reinforcing regional momentum.
Europe ranks second by value, buoyed by Clean Aviation grants and airport decarbonization policies. EU projects such as GOLIAT and EcoPulse channel public funds into liquid-hydrogen handling, superconducting cables, and hybrid-electric flight tests. EASA harmonization with the FAA accelerates transatlantic validation for eVTOLs, shortening time-to-market for dual-registry operators. Nevertheless, European suppliers face currency inflation in semiconductor procurement, prompting joint ventures with Asian foundries to secure wafer allocations.
Asia-Pacific records the highest growth at a 12.24% CAGR. China's Civil Aviation Administration earmarked dedicated low-altitude corridors for eVTOL logistics and passenger shuttles, compressing commercial deployment timelines. State plans to build a trillion-yuan general-aviation industry by 2030, injecting subsidies and regulatory certainty to attract foreign Tier-2 suppliers. Japan and South Korea focus on urban demonstrator flights for Expo-type events, offering a showcase before broader certification. However, airport readiness lags. India explores electric regional turboprops for short-haul routes under the UDAN connectivity scheme. The region's diverse market entries collectively translate into sustained order books for battery, motor, and avionics vendors, ensuring Asia-Pacific remains the principal volume driver in the more electric aircraft market.
- Airbus SE
- The Boeing Company
- Collins Aerospace (RTX Corporation)
- Safran SA
- Honeywell International Inc.
- General Electric Company
- Rolls-Royce plc
- BAE Systems plc
- Parker-Hannifin Corporation
- Moog Inc.
- Eaton Corporation plc
- Thales Group
- Liebherr Group
- Crane Co.
- Diehl Aviation GmbH
- GKN Aerospace (Melrose plc)
- magniX USA, Inc.
- Ampaire Inc.
- Wright Electric Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrification drive to cut fuel burn and CO2
- 4.2.2 Global emission regulations tightening
- 4.2.3 High-power motors and SiC/GaN electronics
- 4.2.4 Solid-state batteries enable power-spike loads
- 4.2.5 ESG-driven retrofit demand for APUs
- 4.2.6 Stealth-focused electric actuation (defense)
- 4.3 Market Restraints
- 4.3.1 High-voltage certification hurdles
- 4.3.2 Thermal reliability of dense power modules
- 4.3.3 Scarcity of aero-grade SiC supply chain
- 4.3.4 Airport MRO infrastructure lag
- 4.4 Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Aircraft Type
- 5.1.1 Commercial Aviation
- 5.1.2 Military Aviation
- 5.1.3 Business and General Aviation
- 5.1.4 Unmanned Aerial Vehicles (UAV)
- 5.1.5 Urban Air Mobility/eVTOL
- 5.2 By Platform
- 5.2.1 Fixed Wing
- 5.2.2 Rotary Wing
- 5.3 By System
- 5.3.1 Power Generation and Management
- 5.3.1.1 Electric Power Generation
- 5.3.1.2 Power Conversion
- 5.3.1.3 Power Distribution
- 5.3.2 Actuation System
- 5.3.2.1 Flight Control Actuation
- 5.3.2.2 Landing Gear Actuation
- 5.3.3 Thermal Management System
- 5.3.4 Engine Start System
- 5.3.5 Environmental Control System
- 5.3.6 Others
- 5.3.1 Power Generation and Management
- 5.4 By End-user
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 France
- 5.5.2.3 Germany
- 5.5.2.4 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Airbus SE
- 6.4.2 The Boeing Company
- 6.4.3 Collins Aerospace (RTX Corporation)
- 6.4.4 Safran SA
- 6.4.5 Honeywell International Inc.
- 6.4.6 General Electric Company
- 6.4.7 Rolls-Royce plc
- 6.4.8 BAE Systems plc
- 6.4.9 Parker-Hannifin Corporation
- 6.4.10 Moog Inc.
- 6.4.11 Eaton Corporation plc
- 6.4.12 Thales Group
- 6.4.13 Liebherr Group
- 6.4.14 Crane Co.
- 6.4.15 Diehl Aviation GmbH
- 6.4.16 GKN Aerospace (Melrose plc)
- 6.4.17 magniX USA, Inc.
- 6.4.18 Ampaire Inc.
- 6.4.19 Wright Electric Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


