

|
시장보고서
상품코드
2120675
에틸렌옥사이드 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Ethylene Oxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
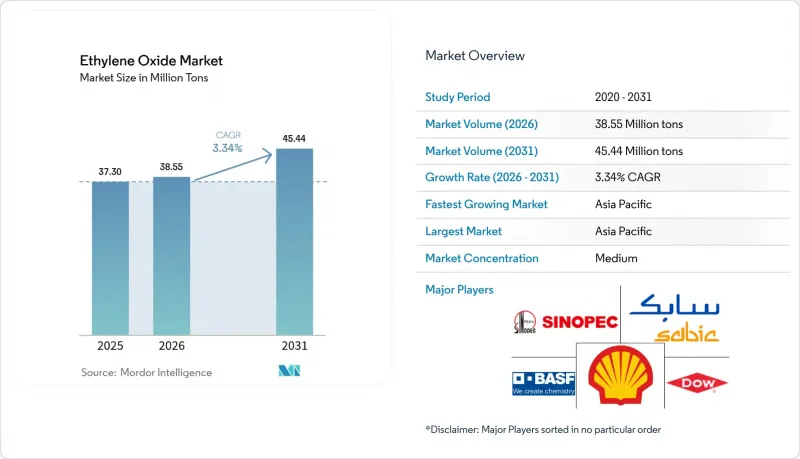
에 의하면, 에틸렌옥사이드 시장 규모는 2025년 3,730만 톤에서 2026년에는 3,855만 톤에 이르고, 2026-2031년 CAGR 3.34%로 성장을 지속하여 2031년에는 4,544만 톤에 이를 것으로 예측됩니다.
본 보고서는 파생 제품(에틸렌글리콜, 에톡실레이트, 에탄올아민 등), 용도(폴리에스터 섬유·PET 수지, 계면활성제·세제 등), 최종 사용자 산업(자동차, 농약, 식품 및 음료 등),원료(석유 유래 에틸렌 및 바이오 에틸렌), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
세계 에틸렌옥사이드 시장 동향 및 인사이트
식품 및 음료 업계에서의 PET 사용 확대
브랜드 소유주들이 제품의 품질을 유지하면서 가볍고 재활용 가능한 솔루션을 선호함에 따라 PET 포장재의 채택이 가속화되고 있습니다. 에틸렌옥사이드 유래의 모노에틸렌글리콜은 PET 중합에 사용되는 전체 에틸렌글리콜의 약 90%를 차지하며, 업스트림 수요를 직접 견인하고 있습니다. 주요 수지 제조업체들은 사용 후 PET를 90% 이상의 수율로 단량체로 탈중합하는 화학 재활용 플랫폼을 지원함으로써, 에틸렌옥사이드 공급량을 안정화시키면서 순환형 공급망을 실현하고 있습니다. 다우(Dow) 등의 기업은 2030년까지 매년 수백만 메트르톤 규모의 순환형 및 재생 가능 플라스틱을 공급하기 위한 프로그램을 수립하고 있습니다. 이러한 노력 덕분에 제품 구성이 재생 등급으로 전환되고 있는 상황에서도 장기적인 수요 전망이 더욱 밝아지고 있습니다.
가정용·퍼스널케어 제품 수요 증가
에톡실레이트나 에탄올아민이 배합된 계면활성제나 세제는 특히 경수 지역에서 뛰어난 세정 효과를 발휘합니다. 친환경 성분을 선호하는 소비자의 기호에 따라 누리온(Nourion) 등의 제조업체는 ISCC PLUS 체계를 기반으로 친환경 에틸렌옥사이드 유도체의 인증 취득을 추진하고 있습니다. 알킬페놀에서 지방알코올 에톡시레이트로의 전환은 성능을 유지하면서 향후 시행될 생분해성 규제에 대응하는 데에도 부합합니다. 자사 브랜드 세정제가 소매점 진열 공간을 확대하는 가운데, 유럽 및 북미의 생산 능력 증강은 이러한 수요 증가에 대응하기 위해 적절한 시기에 이루어지고 있습니다.
고농도 노출에 따른 건강 및 환경 영향
에틸렌옥사이드(EO)는 발암성 물질로 분류되어 있으며, 이에 따라 미국 환경보호청(EPA)은 2025년 1월, 근로자 노출 한계치를 2028년까지 0.5 ppm에서 2035년까지 0.1 ppm으로 낮추는 잠정 결정을 내렸습니다. 이 규정을 준수하기 위해서는 고비용의 공학적 대책, 개인 모니터링, 그리고 설비 투자를 통한 업그레이드가 필요합니다. 일부 의료기기 제조업체들은 감마선 조사, 과산화수소 증기, 이산화질소 등 대체 멸균 방법에 대한 인증 절차를 가속화하고 있습니다. 이러한 대체 수단으로 인해 특정 분야 수요는 감소하겠지만, 복잡한 내강을 가진 열에 민감한 의료기기의 경우 에틸렌옥사이드가 여전히 필수적입니다.
부문 분석
2025년, 에틸렌글리콜은 에틸렌옥사이드 시장의 기반을 형성했으며, 아시아태평양의 폴리에스테르 섬유 및 PET 수지 생산 확대에 따라 75.02%의 점유율을 차지했습니다. 업스트림 공급 차질로 인해 가격 변동이 재연되면서, 아시아의 구매자들은 통합형 생산 업체와의 장기 계약 확보에 박차를 가하고 있습니다. 이와 동시에, 브랜드 소유주들이 저탄소 포장 옵션을 요구함에 따라, 바이오 유래 MEG의 시범 프로젝트가 탄력을 받고 있습니다.
에탄올아민은 생산량은 적지만, 농약, 가스 처리, 퍼스널케어 분야 수요에 힘입어 2031년까지 3.55%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. BASF가 앤트워프 공장의 병목 현상을 해소함에 따라 전 세계 알킬에탄올아민 생산 능력은 연간 14만 톤을 넘어 약 30% 증가했으며, 이로 인해 해당 부문의 전략적 가치가 부각되었습니다. 라틴아메리카 및 아시아 지역의 글리포세이트계 제초제 판매량 증가가 모노에탄올아민 수요를 지속적으로 견인하고 있는 반면, 트리에탄올아민은 CO2 포집용 용매 분야에서 새로운 기회를 발견하고 있습니다. 하류 부문의 강력한 다각화로 인해, 이 유도체 군은 단일 산업의 경기 순환에 덜 영향을 받게 되었습니다.
2025년에는 PET 수지 및 폴리에스테르 섬유가 에틸렌옥사이드 수요의 27.86%를 차지했습니다. 음료 제조업체들이 유리나 금속 병에서 경량 PET 병으로 전환함에 따라, PET와 관련된 에틸렌옥사이드 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 디메틸 카보네이트를 이용한 메탄올 분해와 같은 혁신적인 탈중합 공정을 통해 디메틸 테레프탈산의 수율을 90% 이상 달성할 수 있게 되어, 고순도의 재생 PET 스트림이 실현됩니다. 예측 기간 동안 선진 지역에서는 버진 소재 수요가 완만하게推移하는 반면, 재활용 인프라가 아직 구축 중인 급성장 경제권에서는 수요가 확대될 전망입니다.
멸균 및 훈증은 연평균 성장률(CAGR) 3.67%로 가장 빠르게 성장하는 용도로 선정되었습니다. 약 50,000종의 의료기기가 에틸렌옥사이드에 의한 멸균에 의존하고 있으며, 이는 감마선이나 전자선 조사에 견디지 못하는 열불안정성 폴리머를 보호하는 데 도움이 됩니다. 배출 규제가 엄격함에도 불구하고, 대체 방식으로는 복잡한 포장을 관통하지 못하거나 필요한 멸균 보증 수준을 달성하지 못하는 경우가 많기 때문에 수요는 지속되고 있습니다. 촉매 산화 장치 및 연속 배기가스 모니터링에 대한 투자를 통해 규제를 준수하는 운영이 가능해지면서, 이 틈새 시장의 성장이 지속되고 있습니다.
지역별 분석
2025년에도 아시아태평양은 에틸렌옥사이드 시장에서 최대 규모를 유지하며, 전 세계 수요의 50.72%를 공급할 뿐만 아니라 2031년까지 지역 최고 수준인 연평균 성장률(CAGR) 3.68%로 성장할 전망입니다. 중국은 생산 능력 확충을 주도하고 있으며, BASF의 잔장(湛江) 통합 복합 시설이 2025년에 가동을 시작할 예정입니다. 인도에서는 정부의 제조 장려 정책에 힘입어 국내 폴리에스터 섬유 생산 확대에 따라 생산량이 증가하고 있습니다. 각 지역 정부는 환경 규제를 강화하고 있지만, 첨단 배출 저감 기술을 갖춘 통합 복합 단지는 경쟁력을 유지하고 있습니다.
북미는 셰일 유래 에탄을 활용한 경제성 덕분에 세계에서 가장 낮은 수준의 에틸렌 현금 원가를 실현하고 있습니다. 의료기기 멸균 수요 증가가 국내 소비를 견인하고 있으며, 2024년 INEOS가 LyondellBasell의 베이포트 사업부를 인수함으로써 최대 단일 시장에서공급 체제가 강화되었습니다. EPA(미국 환경보호청)의 배출 규제를 준수함에 따라 촉매식 스크러버 및 실시간 모니터링에 대한 투자가 가속화되어 세계적 기술 기준을 확립하고 있습니다.
유럽은 에너지 가격 급등과 더욱 엄격해진 CO2 배출 목표에 직면해 있으며, 2023년부터 2024년에 걸쳐 지역 내 화학제품 생산 능력 1,100만 톤이 폐쇄될 전망입니다. 2024년에 체결된 클라리언트와 OMV 간의 저탄소 에틸렌 및 에틸렌옥사이드 유도체 공급에 관한 합의와 같은 제휴는 수입품에 대한 시장 점유율을 방어하기 위한 것입니다. 동유럽은 파이프라인 가스 접근성과 확립된 하류 폴리에스터 자산을 통해 선택적인 경쟁력을 유지하고 있습니다.
중동에서는 통합형 복합 시설에서 유리한 원료를 활용하고 있으며, 사우디아라비아에 기반을 둔 생산자들은 아시아 수출 시장을 목표로 하고 있습니다. 아프리카에서는 현지 생산이 제한적이지만, 세제 및 농약 제제용 수입은 견조한 추세를 보이고 있습니다. 남미에서는 브라질에서 바이오에틸렌 프로젝트가 진행 중이며, 향후 10년 동안 이 지역이 저탄소 유도체의 잠재적 순수출 지역이 될 전망입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the ethylene oxide market size is expected to grow from 37.30 Million tons in 2025 to 38.55 Million tons in 2026 and is forecast to reach 45.44 Million tons by 2031 at 3.34% CAGR over 2026-2031.
This report is Segmented by Derivative (Ethylene Glycols, Ethoxylates, Ethanolamines, and More), Application (Polyester Fiber and PET Resins, Surfactants and Detergents, and More), End-User Industry (Automotive, Agrochemicals, Food and Beverage, and More), Feedstock (Petro-Based Ethylene and Bio-Ethylene), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa).
Global Ethylene Oxide Market Trends and Insights
Growing Usage of PET in the Food and Beverage Industry
PET packaging adoption is accelerating because brand owners favor lightweight, recyclable solutions that preserve product integrity. Monoethylene glycol derived from ethylene oxide constitutes nearly 90% of the ethylene glycol pool used for PET polymerization, causing direct pull-through on upstream demand. Large resin producers are backing chemical-recycling platforms that depolymerize post-consumer PET into monomers with yields above 90%, enabling circular supply chains while keeping ethylene oxide volumes steady. Companies such as Dow have earmarked multi-million-metric-ton programs to deliver circular and renewable plastics annually by 2030. These initiatives strengthen long-term demand visibility even as the product mix shifts toward recycled grades.
Increasing Demand for Household and Personal Care Products
Surfactants and detergents formulated with ethoxylates and ethanolamines deliver superior cleaning efficiency, especially in hard-water regions. Consumer preference for eco-friendly ingredients is prompting producers such as Nouryon to certify green ethylene oxide derivatives under the ISCC PLUS scheme. Switching from alkylphenol to fatty-alcohol ethoxylates aligns with forthcoming biodegradability regulations while sustaining performance. Capacity additions in Europe and North America are timed to capture this demand uptick as private-label cleaning brands gain retail shelf space.
Health and Environmental Effects over High Exposure
Ethylene oxide is classified as carcinogenic, prompting the EPA's January 2025 interim decision that cuts worker exposure limits from 0.5 ppm by 2028 down to 0.1 ppm by 2035. Compliance demands costly engineering controls, personal monitoring, and capital upgrades. Some healthcare device makers are accelerating the qualification of alternative sterilization methods, including gamma radiation, vaporized hydrogen peroxide, and nitrogen dioxide. While these substitutes will erode specific volumes, ethylene oxide remains indispensable for heat-sensitive devices with intricate lumens.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Utilization in Medical Device Sterilization
- Growing Demand from Textile and Apparel Industry
- Volatility of Ethylene Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ethylene glycols formed the bedrock of the ethylene oxide market in 2025, capturing 75.02% share as polyester fiber and PET resin output scaled in Asia-Pacific. Price volatility has returned following upstream supply disruptions, pushing Asia-based buyers to secure long-term contracts with integrated producers. In parallel, bio-MEG pilots are gaining traction as brand owners seek lower-carbon packaging options.
Ethanolamines contribute a smaller volume but post the highest 3.55% CAGR to 2031, driven by agrochemicals, gas treatment, and personal-care demand. BASF's Antwerp debottlenecking raised global alkyl ethanolamine capacity by nearly 30% to more than 140,000 t per year, underscoring the segment's strategic value. Rising glyphosate herbicide volumes in Latin America and Asia sustain monoethanolamine pull-through, while triethanolamine sees new opportunities in CO2 capture solvents. Strong downstream diversification shields this derivative class from single-industry cyclicality.
PET resins and polyester fibers absorbed 27.86% of ethylene oxide demand in 2025. The ethylene oxide market size linked to PET is expected to grow steadily as beverage companies transition from glass and metal to lightweight PET bottles. Innovative depolymerization pathways such as dimethyl-carbonate-aided methanolysis enable greater than 90% dimethyl terephthalate yields, opening high-purity recycled PET streams. Over the forecast horizon, virgin demand moderates in developed regions yet expands in fast-growing economies where recycling infrastructure remains nascent.
Sterilization and fumigation ranked as the fastest-growing application at 3.67% CAGR. Approximately 50,000 distinct medical devices rely on ethylene oxide sterilization, preserving thermolabile polymers that cannot withstand gamma or electron-beam radiation. Even with stringent emissions limits, demand persists because alternative modalities often fail to penetrate complex packaging or achieve required sterility assurance levels. Investment in catalytic oxidation units and continuous emissions monitoring allows compliant operations, sustaining growth in this niche.
Complete Report Scope:
- By Derivative
- Ethylene Glycols
- Monoethylene Glycol (MEG)
- Diethylene Glycol (DEG)
- Triethylene Glycol (TEG)
- Ethoxylates
- Ethanolamines
- Glycol Ethers
- Polyethylene Glycol
- Other Derivatives
- Ethylene Glycols
- By Application
- Polyester Fiber and PET Resins
- Surfactants and Detergents
- Sterilization and Fumigation
- Coolant and Antifreeze
- Pharmaceuticals Excipients
- Other Applications
- By End-user Industry
- Automotive
- Agrochemicals
- Food and Beverage
- Textile
- Personal Care
- Pharmaceuticals
- Detergents
- Others End user Industries
- By Feedstock
- Petro-based Ethylene
- Bio-ethylene
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific remained the largest ethylene oxide market in 2025, supplying 50.72% of global demand and expanding at a region-leading 3.68% CAGR to 2031. China anchors capacity additions with BASF's Zhanjiang Verbund complex slated for start-up in 2025. India's production grows alongside local polyester fiber expansion, supported by government manufacturing incentives. Regional governments tighten environmental norms, but integrated complexes with advanced abatement maintain competitiveness.
North America benefits from shale-based ethane economics that yield some of the world's lowest ethylene cash costs. Medical device sterilization concentration elevates domestic consumption, and INEOS's 2024 acquisition of LyondellBasell's Bayport unit consolidates supply in the largest single market. Compliance with EPA emission rules accelerates investment in catalytic scrubbers and real-time monitoring, setting a global technology benchmark.
Europe confronts high energy prices and more stringent CO2 targets, prompting 11 million tons of regional chemical capacity closures during 2023-2024. Collaborations such as the 2024 Clariant-OMV agreement to supply lower-carbon ethylene and ethylene oxide derivatives aim to defend market share against imports. Eastern Europe retains selective competitiveness through access to pipeline gas and established downstream polyester assets.
The Middle East leverages advantaged feedstock at integrated complexes, with Saudi-based producers targeting export markets in Asia. Africa sees limited local production but steady imports for detergent and agrochemical formulations. South America advances bio-ethylene projects in Brazil, positioning the subcontinent as a potential net exporter of low-carbon derivatives over the next decade.
- BASF SE
- China Petrochemical Corporation
- Clariant
- Dow
- Huntsman International LLC
- India Glycols Limited
- Indorama Ventures Public Company Limited
- INEOS
- LOTTE Chemical Corporation
- NIPPON SHOKUBAI CO., LTD.
- Nouryon
- PETRONAS Chemicals Group Berhad
- Reliance Industries Limited
- SABIC
- Sasol Limited
- Shell plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Usage of PET in the Food and Beverage Industry
- 4.2.2 Increasing Demand for Household and Personal Care Products
- 4.2.3 Increasing Utilziation in Medical Device Sterilization
- 4.2.4 Growing Demand from Textile and Apparel Industry
- 4.2.5 Increasing Utilization from the Agriculture Sector
- 4.3 Market Restraints
- 4.3.1 Health and Environmental Effects over High Exposure
- 4.3.2 Volatility of Ethylene Feedstock Prices
- 4.3.3 High Production Cost
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Derivative
- 5.1.1 Ethylene Glycols
- 5.1.1.1 Monoethylene Glycol (MEG)
- 5.1.1.2 Diethylene Glycol (DEG)
- 5.1.1.3 Triethylene Glycol (TEG)
- 5.1.2 Ethoxylates
- 5.1.3 Ethanolamines
- 5.1.4 Glycol Ethers
- 5.1.5 Polyethylene Glycol
- 5.1.6 Other Derivatives
- 5.1.1 Ethylene Glycols
- 5.2 By Application
- 5.2.1 Polyester Fiber and PET Resins
- 5.2.2 Surfactants and Detergents
- 5.2.3 Sterilization and Fumigation
- 5.2.4 Coolant and Antifreeze
- 5.2.5 Pharmaceuticals Excipients
- 5.2.6 Other Applications
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Agrochemicals
- 5.3.3 Food and Beverage
- 5.3.4 Textile
- 5.3.5 Personal Care
- 5.3.6 Pharmaceuticals
- 5.3.7 Detergents
- 5.3.8 Others End user Industries
- 5.4 By Feedstock
- 5.4.1 Petro-based Ethylene
- 5.4.2 Bio-ethylene
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 BASF SE
- 6.4.2 China Petrochemical Corporation
- 6.4.3 Clariant
- 6.4.4 Dow
- 6.4.5 Huntsman International LLC
- 6.4.6 India Glycols Limited
- 6.4.7 Indorama Ventures Public Company Limited
- 6.4.8 INEOS
- 6.4.9 LOTTE Chemical Corporation
- 6.4.10 NIPPON SHOKUBAI CO., LTD.
- 6.4.11 Nouryon
- 6.4.12 PETRONAS Chemicals Group Berhad
- 6.4.13 Reliance Industries Limited
- 6.4.14 SABIC
- 6.4.15 Sasol Limited
- 6.4.16 Shell plc
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Usage of Bio-derived Ethylene over Petro-based Ethylene for Production


