

|
시장보고서
상품코드
2120686
LiDAR 드론 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)LiDAR Drones - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
LiDAR 드론 시장 규모는 2026년에 2억 9,973만 달러로 추정되고, 2025년 2억 5,122만 달러에서 확대해, 2031년에는 7억 2,466만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 19.31%로 성장할 것으로 전망됩니다.
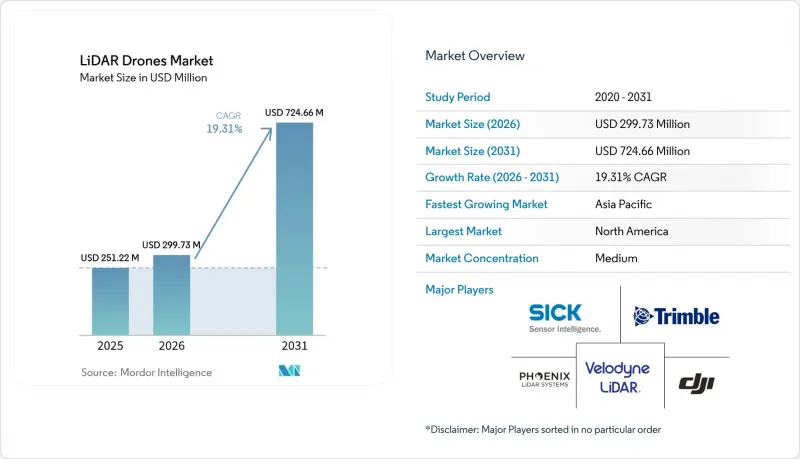
본 보고서는 구성 부품별(레이저 스캐너, 905 nm 기계식 등), 제품 폼 팩터별(회전익, 고정익 등), 운용 고도별(초저고도, 저고도 등), 측정 범위별(단거리, 중거리 등), 서비스 모델별(하드웨어 판매, 턴키형 LiDAR-as-a-Service 등), 용도별(정밀 농업 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 LiDAR 드론 시장 동향 및 인사이트
솔리드 스테이트 LiDAR의 비용이 400달러 미만으로 떨어지면서 양산형 드론의 보급이 가능해졌습니다.
포토닉스의 집적화와 양산화로 인해 솔리드 스테이트 LiDAR의 단가는 400달러 아래로 떨어졌으며, 그동안 소규모 계약업체, 농가, 지자체가 LiDAR 탑재 기기를 도입하는 것을 주저하게 만들었던 비용 장벽이 제거되었습니다. Hesai사의 연간 30만 대라는 생산량은 현재 가능해 진 규모의 경제를 여실히 보여주고 있습니다. 기계 부품의 제거로 신뢰성이 향상되었으며, 유지보수 비용도 절감되었습니다. 또한, 특허 출원 현황을 통해 빔 스티어링 최적화를 위한 적극적인 노력이 엿보입니다. 이러한 변화로 인해 조달처가 전문 측량 회사에 그치지 않고 일반 건설 업계 및 환경 서비스 업계로 확대되면서, 정기적인 업그레이드 주기가 촉진되고 있습니다.
EU의 ‘오픈 카테고리’ 규정에 힘입어 250g 미만의 마이크로 매핑 드론이 급증
유럽의 ‘오픈 카테고리’ 규제에 따라 250g 미만의 항공기는 조종사 면허 없이도 비행이 가능해지면서, 클래스 C0 드론을 위해 설계된 마이크로 LiDAR 페이로드가 대거 등장하고 있습니다. 각 제조업체는 중량 상한을 초과하지 않으면서 50 pts/m²에 가까운 점 밀도를 실현하고 있습니다. DJI의 ‘Air 3S’는 소비자용 기체에서도 장애물 회피 및 기본적인 매핑을 위해 전방 LiDAR를 탑재할 수 있게 되었음을 보여줍니다. 도시 계획 담당자와 문화재 보호 담당자들은 합리적인 가격에 신속하게 도입할 수 있는 도구의 혜택을 누리고 있으며, 캐나다와 일본에서도 유사한 체계가 마련되고 있어 대상 시장이 확대되고 있습니다.
다중 페이로드 기체에서 1550 nm 레이저의 EMI 적합성 관련 과제
FAA 지침 AC 20-183에서는 고출력 1550 nm 레이저가 무선기나 레이더와 동일한 기체에 탑재되는 경우, 엄격한 EMI, 피폭 및 눈에 대한 위험성 계산을 요구하고 있습니다. 차폐 및 파장 선택형 필터의 도입으로 인해 시스템 비용이 15-25% 증가함에 따라, 멀티 센서 탑재 리그의 조달이 지연되고 있습니다. 인증 지연으로 인해 리드타임이 길어지고 있으며, 특히 하나의 리그에 메탄 분광 분석, 광대역 통신, GNSS를 통합하는 석유 및 가스 사업자에게 큰 영향을 미치고 있습니다.
부문 분석
2025년, 레이저 스캐너는 LiDAR 드론 시장 점유율의 39.35%를 유지했으며, 이는 포인트 클라우드 생성에 있어 레이저 스캐너가 수행하는 대체 불가능한 역할을 반영합니다. 센티미터급 관성 항법 및 GNSS 융합이 긴밀하게 연계된 SLAM 워크플로우에 필수적이기 때문에 항법 및 위치 측정 유닛은 연평균 성장률(CAGR) 21.1%로 발전하고 있습니다. 이러한 고정밀 기준 패키지는 프리미엄 측량 등급의 결과물을 제공하는 LiDAR 드론 시장 규모를 뒷받침하고 있습니다. 온도 조절 모듈 및 엣지 프로세서와 같은 2차 구성 요소에는 현재 비행 중 특징량 추출을 처리하기 위한 AI 가속기가 내장되어 있습니다. 각 제조업체는 개발 주기를 단축하고 현장에서의 교체를 간소화하기 위해 공통 전기 및 데이터 인터페이스를 도입하고 있으며, 이를 통해 기체 운영 사업자의 총 소유 비용(TCO)이 절감되고 있습니다.
표준화는 LiDAR 코어뿐만 아니라 카메라, 다중 스펙트럼 또는 자력계 유닛의 플러그 앤 플레이 방식 업그레이드를 가능하게 하는 오픈소스 미들웨어로도 확대되고 있습니다. 비행 시간의 연장에 따라 배터리 수명과 열적 한계에 대한 부하가 증가함에 따라, 배터리 관리 시스템은 고도화되고 있습니다. 설계상의 초점은 고주파 송신기와 광증폭 회로 간의 전자기 결합에 대한 차폐 대책으로 이동하고 있으며, 이는 1550 nm 대역의 도입 확대에 따라 그 중요성이 더욱 커지고 있습니다.
2025년 총 출하 대수의 62.4%를 차지한 것은 회전익기였으며, 호버링 시의 안정성, 수직 이륙, 그리고 구조물 주변에서의 정밀한 위치 결정이 가능하다는 점에서 선호되고 있습니다. 하이브리드 VTOL 기체는 비교적 새로운 기종이지만, 이러한 제어상의 장점과 고정익 기체의 순항 효율을 겸비하고 있어, 조종사는 배터리 한 번 충전으로 50km가 넘는 구간을 감시할 수 있습니다. 현재 고정익기 설계에는 듀얼 센서 페이로드를 탑재할 수 있는 모듈식 노즈콘과 날개 하드포인트가 채택되어 있어, 비행 시간당 측량 생산성이 향상되고 있습니다.
LiDAR 드론 시장에서는 휴대전화 기지국, 건물 외관,및 협소한 현장의 매핑 분야에서 회전익기의 범용성이 여전히 높이 평가되고 있지만, 호버링 시간과 관련된 보험료 상승으로 인해 지형상 이착륙 구역을 확보할 수 있는 장소에서는 운영자가 고정익기를 활용한 출동을 검토하고 있습니다. 이에 대응하여 각 제조업체는 1교대 근무 동안 동일한 센서 스택을 서로 다른 플랫폼 간에 재배치할 수 있는 퀵 스왑 방식의 기체 키트를 제공함으로써, 제품 유형 간의 기존 경계를 모호하게 만들고 있습니다.
지역별 분석
북미는 2025년 전 세계 매출의 35.10%를 차지한 것으로 평가되었으며, 확립된 BVLOS(시야 외 비행) 면제 체계, 견고한 GNSS 보정 그리드 및 100 kg/h의 감지 임계치를 규정하는 연방 메탄 누출 규제의 혜택을 받고 있습니다. 주요 에너지 기업들은 EPA(미국 환경보호청)의 규제 준수를 충족하기 위해 드론 도입에 자금을 투자하고 있으며, 각 주 교통국(DOT)은 보수 주기에 앞서 교량과 도로를 스캔하기 위해 자금을 배정하고 있습니다. Trimble사의 2025년 1분기 8억 4,100만 달러의 매출은 기계 제어 및 측량 자동화와 관련된 측정 장비에 대한 지속적인 수요를 보여줍니다.
아시아태평양은 22.80%의 점유율을 차지했으며, 중국의 LiDAR 생산 규모와 인도의 인프라 정비에 힘입어 가장 가파른 성장 곡선을 그리고 있습니다. 헤사이(Hesai)사만 해도 2025년 1분기에 19만 5,818개의 센서를 출하하여, 이 지역의 강력한 제조 역량을 보여주고 있습니다. 인도의 민관 협력 프로젝트에서는 부지 확보 및 진행 상황 추적에 드론 매핑이 활용되고 있는 반면, 일본에서는 지방 자치 단체의 논 조사에 대해 보조금이 지급되고 있습니다. 아세안(ASEAN) 국가들에서는 BVLOS(시야 외 비행)에 관한 규제 조화가 지연되고 있어, 해상 파이프라인 및 송전선로 정찰 활동의 확대가 억제되고 있습니다.
유럽에서는 EASA의 ‘오픈 카테고리’에 기반한 통일된 공역 규제의 혜택을 받고 있으며, 도시 측량 및 문화유산 아카이빙을 위한 마이크로 플랫폼 도입이 촉진되고 있습니다. 헥사곤은 2024년 3분기에 5억 6,490만 유로(6억 6,464만 달러)의 지속적 매출을 보고했으며, 이는 거시경제적 역풍에도 불구하고 디지털 리얼리티 도입이 견조함을 보여줍니다. 단일 광자 기술의 발전으로 효율적인 국토 측량이 기대되고 있으며, ‘그린 딜’의 생물다양성 목표가 임업 및 서식지에 대한 LiDAR 기준선 수요를 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, LiDAR drone market size in 2026 is estimated at USD 299.73 million, growing from 2025 value of USD 251.22 million with 2031 projections showing USD 724.66 million, growing at 19.31% CAGR over 2026-2031.
This report is Segmented by Component (Laser Scanners, 905 Nm Mechanical, and More), Product Form-Factor (Rotary-Wing, Fixed-Wing, and More), Operating Altitude (Very-Low, Low, and More), Range (Short, Medium, and More), Service Model (Hardware Sales, Turn-Key LiDAR-As-A-Service, and More), Application (Precision Agriculture, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global LiDAR Drones Market Trends and Insights
Break-even of Solid-state LiDAR Cost Below USD 400 Enabling Mass-market Drones
Photonics integration and scaled manufacturing have pushed solid-state unit prices below USD 400, removing the historical cost barrier that discouraged smaller contractors, farmers, and municipalities from adopting LiDAR-equipped aircraft. Hesai's 300,000-unit annual volumes exemplify the economies of scale now possible. Mechanical parts elimination improves reliability and cuts maintenance, and patent filings show intense work on beam steering optimization. These shifts are expanding procurement beyond specialized survey firms into mainstream construction and environmental services, bolstering recurring upgrade cycles.
Surge in Sub-250 g Micro-mapping Drones Driven by EU Open-category Rules
Open-category regulations in Europe allow sub-250 g aircraft to be flown without a pilot license, spurring a wave of micro-LiDAR payloads engineered for class C0 drones. Manufacturers now reach point densities near 50 pts/m2 while staying under the weight ceiling. DJI's Air 3S shows how consumer-grade craft now host forward-facing LiDAR for obstacle avoidance and basic mapping. Urban planners and heritage conservators benefit from affordable, quick-deployment tools, and similar frameworks are emerging in Canada and Japan, broadening the addressable base.
EMI Compliance Hurdles for 1550 nm Lasers on Multi-payload Rigs
FAA guidance AC 20-183 requires rigorous EMI, exposure, and ocular hazard calculations when high-power 1550 nm lasers share airframes with radios and radars. Shielding and wavelength-selective filters add 15-25% to system cost, slowing procurement for multi-sensor fleets. Certification backlogs extend lead times, particularly for oil-and-gas operators integrating methane spectroscopy, broadband comms, and GNSS on one rig.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Bathymetric LiDAR on VTOL Drones for Shallow-water Asset Surveys
- Cloud-native SLAM/AI Point-cloud Pipelines Reducing Post-processing Lead-time
- Fragmented Air-traffic Management Delaying BVLOS Permits in ASEAN
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Laser scanners retained 39.35% of LiDAR drone market share in 2025, reflecting their irreplaceable role in point-cloud generation. Navigation and positioning units are advancing at a 21.1% CAGR, as centimeter-grade inertial-GNSS fusion has become essential for tightly coupled SLAM workflows. These precise reference packages anchor the LiDAR drone market size for premium survey-grade deliverables. Second-tier components, including thermal regulation modules and edge processors, now incorporate AI accelerators to handle in-flight feature extraction. Manufacturers are rolling out common electrical and data interfaces that shorten development cycles and simplify field swaps, lowering total cost of ownership for fleet operators.
Standardization extends to open-source middleware that allows plug-and-play upgrades of camera, multispectral, or magnetometer units alongside the LiDAR core. Battery management systems gain sophistication as extended-endurance flights stress cell life and thermal limits. Design attention is shifting to shielding against electromagnetic coupling between high-frequency transmitters and light-amplification circuits, a theme amplified by growing 1550 nm deployment.
Rotary-wing aircraft provided 62.4% of total shipments in 2025, favored for their hover stability, vertical takeoff, and precision positioning around structures. Hybrid VTOL craft, though newer, combine those control benefits with fixed-wing cruise efficiency, allowing operators to surveil corridors exceeding 50 km on a single battery. Fixed-wing designs now include modular nose cones and wing hardpoints capable of hosting dual-sensor payloads, expanding survey productivity per flight hour.
The LiDAR drone market continues to value rotary-wing versatility for cell-tower, facade, and confined-site mapping, yet rising insurance premiums tied to hover time encourage operators to consider fixed-wing sorties where terrain allows launch and recovery strips. Manufacturers answer with quick-swap airframe kits enabling crews to redeploy the same sensor stack across platform types within a single shift, blurring historical boundaries between product classes.
Complete Report Scope:
- By Component
- Laser Scanners
- 905 nm Mechanical
- 905 nm MEMS
- 1550 nm Fiber
- Navigation and Positioning Systems
- Inertial Measurement Units
- Cameras
- Power and Thermal Modules
- Other Components
- By Product Form-Factor
- Rotary-Wing
- Fixed-Wing
- Hybrid VTOL
- By Operating Altitude
- Very-Low (?120 m)
- Low (120-300 m)
- Medium (300-500 m)
- By Range
- Short (<100 m)
- Medium (100-500 m)
- Long (>500 m)
- By Service Model
- Hardware Sales
- Turn-key LiDAR-as-a-Service
- Analytics SaaS
- By Application
- Construction and Infrastructure
- Environment and Forestry
- Precision Agriculture
- Corridor Mapping (Road, Rail, Pipeline)
- Mining and Quarrying
- Defense and Security
- Disaster Management and Insurance
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America preserved 35.10% of global revenues in 2025, benefiting from established BVLOS waiver pathways, robust GNSS correction grids, and federal methane-leak rules that specify 100 kg/h detection thresholds. Energy majors fund fleet rollouts to meet EPA compliance, and state DOTs allocate capital to scan bridges and roads ahead of rehabilitation cycles. Trimble's Q1 2025 USD 841 million earnings reveal sustained instrument demand tied to machine control and survey automation.
Asia-Pacific holds 22.80% share yet records the steepest growth slope, propelled by China's LiDAR production scale and India's infrastructure build-out. Hesai alone shipped 195,818 sensors in Q1 2025, underlining regional manufacturing muscle. India's public-private corridors embrace drone mapping for land acquisition and progress tracking, while Japan subsidizes local government rice-field surveys. BVLOS harmonization lags across ASEAN, tempering offshore pipeline and power-line reconnaissance expansion.
Europe benefits from uniform air-space provisions under EASA's Open-category, stimulating micro-platform uptake for urban surveying and cultural-heritage archiving. Hexagon reported EUR 564.9 million (USD 664.64 million) recurring revenue for Q3 2024, signaling strong digital reality adoption despite macro headwinds. Single-photon advances promise efficient national mapping, and the Green Deal's biodiversity targets feed demand for forestry and habitat LiDAR baselines.
- DJI
- Leica Geosystems (Hexagon)
- RIEGL Laser Measurement
- Velodyne / Ouster
- Phoenix LiDAR Systems
- YellowScan SAS
- FARO Technologies
- Teledyne Optech
- Trimble Inc.
- Sick AG
- Microdrones GmbH
- senseFly SA
- Terra Drone Corp.
- Innoviz Technologies
- Luminar Technologies
- Parrot Drone SAS
- GeoCue Group Inc.
- Cepton Technologies
- Robosense (LeiShen)
- Topodrone LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Break-even of solid-state LiDAR cost < USD 400 enabling mass-market drones
- 4.2.2 Surge in sub-250 g "micro-mapping" drones driven by EU Open-category rules
- 4.2.3 Integration of bathymetric LiDAR on VTOL drones for shallow-water asset surveys
- 4.2.4 Cloud-native SLAM/AI point-cloud pipelines reducing post-processing lead-time
- 4.2.5 60 % Oil-and-gas methane-leak detection mandates in N. America using LiDAR UAVs
- 4.2.6 African corridor finance (Af CFTA) favouring drone-based topo surveys over manned aircraft
- 4.3 Market Restraints
- 4.3.1 EMI compliance hurdles for 1550 nm lasers on multi-payload rigs
- 4.3.2 Fragmented air-traffic management delaying BVLOS permits in ASEAN
- 4.3.3 Carbon-battery transport regulations raising logistics cost for service providers
- 4.3.4 Limited GNSS correction infrastructure in Caribbean island nations
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Industry Value-Chain Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Laser Scanners
- 5.1.2 905 nm Mechanical
- 5.1.3 905 nm MEMS
- 5.1.4 1550 nm Fiber
- 5.1.5 Navigation and Positioning Systems
- 5.1.6 Inertial Measurement Units
- 5.1.7 Cameras
- 5.1.8 Power and Thermal Modules
- 5.1.9 Other Components
- 5.2 By Product Form-Factor
- 5.2.1 Rotary-Wing
- 5.2.2 Fixed-Wing
- 5.2.3 Hybrid VTOL
- 5.3 By Operating Altitude
- 5.3.1 Very-Low (?120 m)
- 5.3.2 Low (120-300 m)
- 5.3.3 Medium (300-500 m)
- 5.4 By Range
- 5.4.1 Short (<100 m)
- 5.4.2 Medium (100-500 m)
- 5.4.3 Long (>500 m)
- 5.5 By Service Model
- 5.5.1 Hardware Sales
- 5.5.2 Turn-key LiDAR-as-a-Service
- 5.5.3 Analytics SaaS
- 5.6 By Application
- 5.6.1 Construction and Infrastructure
- 5.6.2 Environment and Forestry
- 5.6.3 Precision Agriculture
- 5.6.4 Corridor Mapping (Road, Rail, Pipeline)
- 5.6.5 Mining and Quarrying
- 5.6.6 Defense and Security
- 5.6.7 Disaster Management and Insurance
- 5.7 Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 United Kingdom
- 5.7.2.2 Germany
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Rest of Asia
- 5.7.4 Middle East
- 5.7.4.1 Israel
- 5.7.4.2 Saudi Arabia
- 5.7.4.3 United Arab Emirates
- 5.7.4.4 Turkey
- 5.7.4.5 Rest of Middle East
- 5.7.5 Africa
- 5.7.5.1 South Africa
- 5.7.5.2 Egypt
- 5.7.5.3 Rest of Africa
- 5.7.6 South America
- 5.7.6.1 Brazil
- 5.7.6.2 Argentina
- 5.7.6.3 Rest of South America
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Funding, Partnerships)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global?level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 DJI
- 6.4.2 Leica Geosystems (Hexagon)
- 6.4.3 RIEGL Laser Measurement
- 6.4.4 Velodyne / Ouster
- 6.4.5 Phoenix LiDAR Systems
- 6.4.6 YellowScan SAS
- 6.4.7 FARO Technologies
- 6.4.8 Teledyne Optech
- 6.4.9 Trimble Inc.
- 6.4.10 Sick AG
- 6.4.11 Microdrones GmbH
- 6.4.12 senseFly SA
- 6.4.13 Terra Drone Corp.
- 6.4.14 Innoviz Technologies
- 6.4.15 Luminar Technologies
- 6.4.16 Parrot Drone SAS
- 6.4.17 GeoCue Group Inc.
- 6.4.18 Cepton Technologies
- 6.4.19 Robosense (LeiShen)
- 6.4.20 Topodrone LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


