

|
시장보고서
상품코드
2121269
파이토뉴트리언트 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Phytonutrients - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
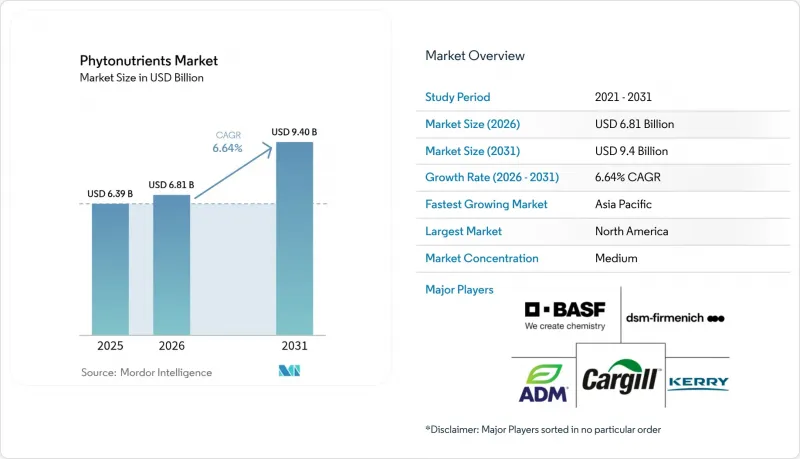
에 따르면 파이토뉴트리언트 시장 규모는 2025년 63억 9,000만 달러에서 2026년에는 68억 1,000만 달러로 확대되고, 2026년부터 2031년까지 CAGR 6.64%를 기록하며 2031년까지 94억 달러에 달할 것으로 예측됩니다.
본 보고서는 유형별(카로티노이드, 폴리페놀, 기타), 공급원별(과일·채소, 곡물, 콩류, 유지종자, 기타), 형태별(분말, 액체, 기타), 용도별(음식·음료, 영양보조식품, 동물 사료, 기타), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 파이토뉴트리언트 시장의 동향 및 인사이트
클린 라벨 식음료의 영양 강화에 대한 수요 급증
2024년 FDA가 식품 용도에서의 적색 3호 사용을 금지함에 따라, 각 제조사는 천연 유래 대체재를 사용하여 제품 배합을 재검토했습니다. 식품·음료 기업들은 브랜드 전략, 규제 요건, 관능적 특성 요건을 충족하기 위해 스피루리나, 비트 뿌리 적색, 카로티노이드 등의 천연 착색 원료를 점점 더 많이 도입하고 있습니다. 각 제조사는 2025년에 소매 가격을 12-15% 인상함으로써 원자재비 급등분을 성공적으로 상쇄했습니다. 고도 추출법, 특히 천연 심공융 용매의 도입을 통해 기존 에탄올 공정에 비해 10% 이상의 수율 향상을 달성함과 동시에 지속가능성 목표도 뒷받침되고 있습니다. 클린 라벨 원료로의 산업 전환은 전문적인 시장 부문에서 소비자가 가장 중요하게 여기는 요소 중 하나로 크게 진화하고 있으며, 이것이 파이토뉴트리언트 시장의 지속적인 성장을 뒷받침하고 있습니다. 이러한 변화는 천연 원료와 식품의 투명성에 대한 소비자의 폭넓은 선호도를 반영하고 있습니다.
예방 의료 및 건강 증진에 대한 소비자의 인식 제고
예방 의학에 대한 인식이 높아짐에 따라 모든 연령대에서 파이토뉴트리언트가 풍부하게 함유된 제품에 대한 소비자 수요가 증가하고 있습니다. 이러한 변화는 건강 의식에 대한 광범위한 변화를 반영하며, 소비자들은 자신의 웰니스 습관을 위해 천연 화합물을 적극적으로 찾고 있습니다. 염증 및 면역 기능에 대한 파이토뉴트리언트의 효과를 입증한 연구는, 증거 기반의 건강 솔루션을 추구하는 소비자에게 어필할 수 있는 과학적 근거를 제공합니다. 여러 임상 연구를 통해 이러한 화합물이 다양한 생물학적 과정의 조절을 돕고 전반적인 건강 유지를 지원한다는 사실이 밝혀졌습니다. 피토좀과 같은 첨단 전달 시스템은 파이토뉴트리언트의 흡수를 개선하여 효과적인 제품을 원하는 소비자의 요구를 충족시킬 뿐만 아니라, 고가 제품화를 가능하게 하고 있습니다. 이러한 기술적 진보 덕분에 제조사들은 식물 유래 화합물의 치료 효과를 극대화하면서 생체 이용률을 높이는, 보다 효율적인 제형을 개발할 수 있게 되었습니다.
파이토뉴트리언트의 추출 및 가공에 따른 높은 생산 비용
높은 생산 비용은 가격에 민감한 소비자의 접근을 제한하고 제조사의 이익을 압박함으로써 시장 성장을 저해하고 있습니다. 기존 추출 방식에는 막대한 에너지와 특수 설비가 필요하며, 특히 초임계 CO₂ 시스템은 제조사에 막대한 설비 투자를 요구합니다. 아임계수 처리나 천연 심공융 용매와 같은 새로운 추출 기술은 제품의 품질과 환경 기준을 유지하면서 비용을 절감할 가능성이 있습니다. 많은 파이토뉴트리언트 카테고리에서는 용도나 지역에 따라 수요가 분산되어 있어 규모의 경제를 달성하기 어렵습니다. 미생물 발효나 식물 세포 배양과 같은 생명공학 기법은 장기적인 생산 비용을 절감하고 농업상의 제약을 극복할 가능성이 있지만, 막대한 초기 투자가 필요합니다. 농업 부산물을 식물성 영양소의 원료로 활용하는 것은 비용 절감과 지속가능성 향상에 도움이 됩니다.
부문 분석
카로티노이드는 식품 및 보충제에서 착색제 및 항산화제로 오랫동안 사용되어 온 점을 바탕으로, 2025년에는 파이토뉴트리언트 시장 점유율의 38.12%를 차지했습니다. 활성산소 제거 능력과 프로비타민 A로서의 기능 덕분에 수요는 안정적인 상태를 유지하고 있습니다. 한편, 폴리페놀은 심장 보호 및 신경 보호 효과에 대한 증거가 축적됨에 따라 9.39%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 발효를 통한 합성 기술은 작물의 계절적 제약을 피하고, 로트 간 균일성을 향상시키며, 용매 잔류물을 감소시키고 있습니다. 이 모든 것은 클린 라벨 브랜드를 전개하는 기업들에게 설득력 있는 이점입니다.
확고한 임상적 입증과 비용 효율적인 생산 덕분에 카로티노이드는 앞으로도 식물성 영양소 시장의 수익 기둥으로 남아 있을 것으로 보입니다. 그러나 갈로일을 풍부하게 함유한 탄닌, 레스베라트롤 유사체, 플라보놀 배당체 분야의 혁신이 폴리페놀의 두 자릿수 성장을 견인하고 있어, 2020년대 후반에는 카로티노이드의 우위를 흔들 가능성이 있습니다. 정밀 영양 플랫폼이 유전자 변이와 산화 스트레스 마커를 연관 짓게 됨에 따라, 개인의 건강 프로필에 맞춘 폴리페놀 혼합물이 주목을 받고 있습니다. 이러한 동향은 더 광범위한 파이토뉴트리언트 시장에서 제품 구성이 점차 재조정될 것임을 예고하고 있습니다.
2025년, 과일과 채소는 대규모 농업 생산과 소비자의 신뢰를 바탕으로 파이토뉴트리언트 시장의 53.21%를 차지했습니다. 토마토 찌꺼기, 양파 껍질, 포도 찌꺼기 등의 식품 가공 부산물이 원료로 점점 더 많이 활용되면서, 폐기물을 가치 있는 제품으로 전환하는 동시에 환경에 미치는 영향을 줄이고 있습니다. 미국 농무부(USDA) 보고서에 따르면, 2023년 채소 생산량은 7억 5,800만 cwt에 달하여 충분한 원료 공급이 확보되어 있습니다.
허브와 나무는 아슈와간다, 인삼, 녹차 카테킨에 포함된 아답토젠 화합물에 대한 관심이 높아짐에 힘입어 8.33%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 표준화된 추출 프로토콜을 통해 일관된 유효 성분 농도가 확보되어, 기존에 존재하던 품질 관리상의 우려가 해소되었습니다. 곡물, 콩류, 유지종자는 비용 효율이 뛰어난 대규모 생산이 가능하지만, 식품 용도로서의 수요와 경쟁해야 하는 상황에 직면해 있습니다. 해조류와 합성생물학 플랫폼은 순도와 환경 관리를 보장하는 장기적인 대안이지만, 식물성 영양소 시장을 재편하기 위해서는 추가적인 비용 최적화가 필요합니다.
지역별 분석
북미는 2025년 파이토뉴트리언트 시장의 41.22%를 차지했습니다. 이는 명확한 규제 환경, 연구 개발에 대한 투자, 소비자들이 프리미엄 가격을 지불할 의향이 있다는 점이 기여한 결과입니다. 최근 FDA가 나비콩과 가르디에리아에서 추출한 청색 색소를 승인함에 따라 천연 착색료의 공급이 확대되고 시장의 신뢰도가 더욱 높아지고 있습니다. 2023년 7억 5,800만 cwt의 채소를 포함한 이 지역의 농산물 생산량은 안정적인 원료 공급을 보장하고 있습니다. E-Commerce와 맞춤형 영양 구독 모델을 통해 슈퍼푸드 혼합 제품이나 특정 용도의 구미와 같은 제품의 소비자 직접 판매가 가속화되고 있습니다.
아시아태평양은 중산층의 확대, 진보적인 규제, 전통 의학의 전통에 힘입어 연평균 성장률(CAGR) 8.52%로 가장 빠르게 성장하고 있는 지역입니다. 중국에서는 미세조류 오일 및 프로안토시아니딘과 같은 새로운 건강식품 원료가 승인되면서, 사용이 허가된 성분 목록이 확충되고 제품 혁신의 폭이 넓어지고 있습니다(cfda.com). 인도의 아유르베다와 기능성 표시가 있는 일본 식품은 파이토뉴트리언트의 활용을 더욱 주류화하고 있는 반면, 현지 위탁 제조 생태계는 생산 비용을 절감하여 수출 경쟁력을 높이고 있습니다.
유럽에서는 엄격한 품질 및 지속가능성 기준에 힘입어 꾸준한 성장이 나타나고 있습니다. 친환경 추출 기술의 도입과 생애주기 평가(LCA) 보고는 프리미엄 브랜드의 포지셔닝을 뒷받침하고 있지만, EU 회원국 간의 규제 조화가 일관되지 않아 시간과 비용 부담이 증가하고 있습니다. 남미, 중동 및 아프리카는 여전히 발전 단계에 있지만, 향후 전망은 밝다고 할 수 있습니다. 브라질의 풍부한 농업 자원과 걸프협력회의(GCC) 국가들의 뉴트라슈티컬(영양 기능성 식품) 수요 증가는 파이토뉴트리언트 시장의 향후 확장을 위한 비옥한 토대를 마련하고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the phytonutrients market size is expected to grow from USD 6.39 billion in 2025 to USD 6.81 billion in 2026 and is forecast to reach USD 9.4 billion by 2031 at 6.64% CAGR over 2026-2031.
This report is Segmented by Type (Carotenoids, Polyphenols, and More), Source (Fruits and Vegetables, Cereals, Pulses, and Oilseeds, and More), Form (Powder, Liquid, Others), Application (Food and Beverages, Dietary Supplements, Animal Nutrition, and More), and Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Phytonutrients Market Trends and Insights
Surging Demand for Clean-Label Food and Beverage Fortification
The FDA's delisting of Red Dye No. 3 for food applications in 2024 prompted manufacturers to reformulate their products with natural alternatives. Food and beverage companies are increasingly incorporating natural color ingredients such as spirulina, beetroot red, and carotenoids to meet their branding, regulatory, and sensory requirements. Manufacturers have successfully offset the increased raw material costs through retail price premiums of 12-15% in 2025. The implementation of advanced extraction methods, particularly natural deep eutectic solvents, has achieved yield improvements exceeding 10% compared to traditional ethanol processes while supporting sustainability goals. The industry's transition toward clean-label ingredients has evolved significantly from a specialized market segment to become a primary consumer consideration, which continues to support sustained growth in the phytonutrients market. This shift reflects broader consumer preferences for natural ingredients and transparency in food products.
Heightened Consumer Awareness About Preventive Healthcare and Wellness
Growing awareness of preventive healthcare has increased consumer demand for phytonutrient-enriched products across all demographics. This shift reflects a broader transformation in health consciousness, where consumers actively seek natural compounds for their wellness routines. Research demonstrating phytonutrients' effects on inflammation and immune function has provided scientific validation that appeals to consumers seeking evidence-based health solutions. Multiple clinical studies have shown these compounds can help regulate various biological processes and support overall health maintenance. Advanced delivery systems like phytosomes improve the absorption of phytonutrients, meeting consumer requirements for effective products and supporting higher price points. These technological improvements have enabled manufacturers to develop more efficient formulations that maximize the therapeutic potential of plant-based compounds while ensuring better bioavailability.
High Production Costs Associated with Phytonutrient Extraction and Processing
High production costs limit market growth by restricting access to price-sensitive consumers and reducing manufacturer profits. Traditional extraction methods require substantial energy and specialized equipment, particularly supercritical CO2 systems that demand significant capital investment from manufacturers. New extraction technologies, such as subcritical water processing and natural deep eutectic solvents, may reduce costs while maintaining product quality and environmental standards. Many phytonutrient categories struggle to achieve economies of scale due to scattered demand across applications and regions. While biotechnology methods like microbial fermentation and plant cell culture could lower long-term production costs and overcome agricultural limitations, they require substantial initial investment. Using agricultural by-products as phytonutrient sources helps reduce costs and improve sustainability.
Other drivers and restraints analyzed in the detailed report include:
- Rising Prevalence of Chronic Diseases and Health Conditions
- Accelerating Demand for Immunity-Boosting Products
- Limited Availability of Raw Materials Due to Seasonal Dependencies and Agricultural Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Carotenoids secured 38.12% of the phytonutrients market share in 2025, anchored in long-standing uses as colorants and antioxidants in foods and supplements. Their oxide-scavenging capacity and Provitamin A functions keep demand stable. Conversely, polyphenols deliver the highest 9.39% CAGR on mounting evidence of cardioprotective and neuroprotective benefits. Fermentation-based synthesis now sidesteps seasonal crop limits, improving batch-to-batch consistency and reducing solvent residues-all persuasive advantages for clean-label brand owners.
Strong clinical validation and cost-efficient production ensure carotenoids remain the revenue anchor of the phytonutrients market. However, innovations in galloyl-rich tannins, resveratrol analogs, and flavonol glycosides propel polyphenols toward double-digit gains, which could erode carotenoids' dominance by the late decade. As precision-nutrition platforms link gene variants to oxidative-stress markers, polyphenol blends tailored to personal health profiles gain traction. These trends foreshadow a gradually rebalancing product mix within the wider phytonutrients market.
Fruits and vegetables accounted for 53.21% of the phytonutrients market in 2025, supported by extensive agricultural production and consumer trust. Food processing byproducts such as tomato pomace, onion skins, and grape marc are increasingly used as raw materials, converting waste into valuable products while reducing environmental impact. The United States Department of Agriculture (USDA) reported vegetable production of 758 million cwt in 2023, ensuring a sufficient raw material supply.
Herbs and trees chart the fastest 8.33% CAGR, propelled by interest in adaptogenic compounds from ashwagandha, ginseng, and green tea catechins. Standardized extraction protocols ensure consistent potency, alleviating historical quality-control concerns. Cereals, pulses, and oilseeds offer cost-efficient scale yet must compete with food-use demand. Marine algae and synthetic-biology platforms represent longer-term alternatives that promise purity and environmental control but require further cost optimization before they reshape the phytonutrients market.
Complete Report Scope:
- By Type
- Carotenoids
- Polyphenols
- Phytosterols
- Omega-3 and 6 Fatty Acids
- Vitamins
- Others
- By Source
- Fruits and Vegetables
- Cereals, Pulses, and Oilseeds
- Herbs and Trees
- Other Sources
- By Form
- Powder
- Liquid
- Others
- By Application
- Food and Beverages
- Dietary Supplements
- Animal Nutrition
- Cosmetics and Personal Care
- Pharmaceuticals
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 41.22% of the phytonutrients market in 2025, leveraging robust regulatory clarity, investment in research and development, and consumer readiness to pay premium prices. Recent FDA approvals of butterfly pea flower and Galdieria-derived blue pigment boost the supply of natural colorants, further reinforcing market confidence. The region's produce output, including 758 million cwt of vegetables in 2023, guarantees steady raw-material flows. E-commerce and personalized-nutrition subscription models accelerate direct-to-consumer adoption of superfood blends and targeted gummies.
Asia-Pacific is the fastest-growing region at an 8.52% CAGR, fueled by expanding middle-class populations, progressive regulations, and traditional-medicine heritage. China's approval of new health-food ingredients such as microalgae oil and proanthocyanidins enriches the permissible ingredient list and widens product innovation latitude cfda.com. Indian Ayurveda and Japanese Foods with Function Claims further mainstream phytonutrient usage, while local contract-manufacturing ecosystems reduce production costs, enhancing export competitiveness.
Europe posts steady growth underpinned by stringent quality and sustainability standards. Adoption of green extraction technologies and life-cycle-assessment reporting supports premium brand positioning, though fragmented regulatory alignment across EU members adds time and cost. South America and the Middle East and Africa remain nascent but promising; agricultural abundance in Brazil and emerging nutraceutical demand in the Gulf Cooperation Council create fertile terrain for the future expansion of the phytonutrients market.
- Cargill Inc.
- BASF SE
- Archer Daniels Midland Company
- DSM-Firmenich
- Kerry Group
- Givaudan SA
- Kemin Industries
- Lycored Ltd.
- Sabinsa Corp.
- Indena SpA
- International Flavors and Fragrances Inc.
- Ingredion Inc.
- Tate and Lyle PLC
- Arla Foods amba
- Roquette Freres
- Kalsec Inc.
- Prinova Group
- Foodchem International
- Zhejiang Medicine Co.
- Guangzhou Leader Bio-Tech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for clean-label food and beverage fortification
- 4.2.2 Heightened consumer awareness about preventive healthcare and wellness
- 4.2.3 Rising prevalence of chronic diseases and health conditions
- 4.2.4 Accelerating demand for immunity-boosting products
- 4.2.5 Increasing demand for natural and plant-based ingredients in food products
- 4.2.6 Integration of phytonutrients in animal feed
- 4.3 Market Restraints
- 4.3.1 High production costs associated with phytonutrient extraction and processing
- 4.3.2 Limited availability of raw materials due to seasonal dependencies and agricultural constraints
- 4.3.3 Complex regulatory requirements and approval processes across different regions
- 4.3.4 Competition from synthetic alternatives with lower production costs
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type
- 5.1.1 Carotenoids
- 5.1.2 Polyphenols
- 5.1.3 Phytosterols
- 5.1.4 Omega-3 and 6 Fatty Acids
- 5.1.5 Vitamins
- 5.1.6 Others
- 5.2 By Source
- 5.2.1 Fruits and Vegetables
- 5.2.2 Cereals, Pulses, and Oilseeds
- 5.2.3 Herbs and Trees
- 5.2.4 Other Sources
- 5.3 By Form
- 5.3.1 Powder
- 5.3.2 Liquid
- 5.3.3 Others
- 5.4 By Application
- 5.4.1 Food and Beverages
- 5.4.2 Dietary Supplements
- 5.4.3 Animal Nutrition
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Pharmaceuticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.1.4 Rest of North America
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 Italy
- 5.5.2.4 France
- 5.5.2.5 Spain
- 5.5.2.6 Netherlands
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials (if available), Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cargill Inc.
- 6.4.2 BASF SE
- 6.4.3 Archer Daniels Midland Company
- 6.4.4 DSM-Firmenich
- 6.4.5 Kerry Group
- 6.4.6 Givaudan SA
- 6.4.7 Kemin Industries
- 6.4.8 Lycored Ltd.
- 6.4.9 Sabinsa Corp.
- 6.4.10 Indena SpA
- 6.4.11 International Flavors and Fragrances Inc.
- 6.4.12 Ingredion Inc.
- 6.4.13 Tate and Lyle PLC
- 6.4.14 Arla Foods amba
- 6.4.15 Roquette Freres
- 6.4.16 Kalsec Inc.
- 6.4.17 Prinova Group
- 6.4.18 Foodchem International
- 6.4.19 Zhejiang Medicine Co.
- 6.4.20 Guangzhou Leader Bio-Tech


