

|
시장보고서
상품코드
2121294
코일 코팅 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Coil Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
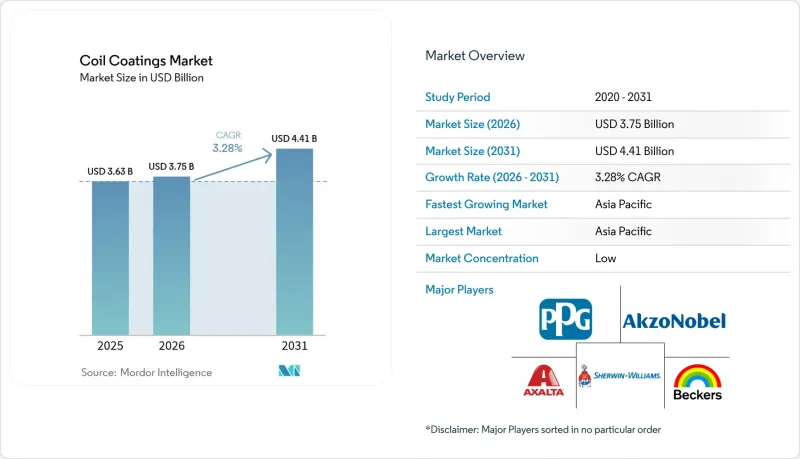
에 의하면, 코일 코팅 시장 규모는 2025년 36억 3,000만 달러에서 2026년에는 37억 5,000만 달러에 이르고, 2026-2031년 CAGR 3.28%로 성장을 지속하여 2031년에는 44억 1,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 수지 유형(폴리에스테르, 폴리비닐리덴플루오라이드, 폴리우레탄, 플라스티졸, 기타 수지), 최종 사용자 산업(건축 및 건설, 산업용·가정용 기기, 운송, 기타 최종 사용자 산업), 지역(아시아태평양, 북미, 유럽,남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 코일 코팅 시장 동향 및 인사이트
건설용 강재 수요 회복
건설용 강재 수주 회복에 따라 프리코트 코일의 사용이 확대되고 있습니다. 이는 건설사가 현장에서의 도장 작업으로 인한 지연을 해소하고, 기상 위험을 줄이며, 인건비를 절감할 수 있기 때문입니다. 세계철강협회는 2025년에 세계 철강 수요가 회복될 것이라는 전망을 제시하고 있으며, 미국, 중국, 인도에서는 비주거용 및 인프라에 대한 지출이 수요를 견인할 것으로 보입니다. 각국 정부는 교량, 학교, 재생에너지 프로젝트에 경기 부양책을 투입하고 있으며, 내식성이 뛰어난 코일 코팅 패널이 선호되고 있습니다. 모듈식 건축 기업들은 품질 표준화와 프로젝트 기간 단축을 위해 공장에서 마감 처리된 시트의 채택을 점점 더 늘리고 있습니다. 20-30년 보증이 적용되는 폴리에스터 및 PVDF 코팅은 총 유지 관리 비용을 절감함으로써 이러한 추세를 뒷받침하고 있습니다. 이러한 요인들이 향후 코일 코팅 시장 성장의 상당 부분을 지탱하는 기반이 되고 있습니다.
에너지 절약형 가전제품의 확대
가전 제조업체(OEM)는 열 성능 및 디자인 요구 사항을 충족하기 위해 코일 코팅을 지정하고 있습니다. 히트 펌프의 실외기에는 동결과 해동이 반복되는 환경을 견디면서도 열전달 효율을 유지할 수 있는 마감 처리가 요구되며, 이러한 필요성은 미국 에너지부의 인센티브 프로그램을 통해 강조되고 있습니다. 한국의 제조업체인 삼성과 LG는 전 세계적으로 645억 달러 규모의 고급 빌트인 제품 라인을 확대하고 있으며, 색상이 조화롭게 적용된 내스크래치 코팅이 브랜드 차별화 요소로 작용하고 있습니다. 냉동 분야에서 저 GWP(지구 온난화 계수) 냉매로의 전환이 진행되는 가운데, 엔지니어들은 화학적 적합성을 확보해야 합니다. 고도의 폴리에스터·실리콘 하이브리드가 필요한 배리어 기능을 제공합니다. 고급 부동산 시장의 일체형 주방 트렌드로 인해 미적 기대치가 높아지고 있으며, 공급업체는 깊이 있는 색조와 고광택 코일 코팅 옵션을 제공해야 합니다. 이러한 트렌드로 인해 코일 코팅 시장 내에서는 견조한 수요 분야가 형성되고 있습니다.
이산화티타늄 및 수지 가격 변동
이산화티타늄(TiO2) 시장에서는 2024년 내내 가격이 격렬하게 변동했습니다. 이는 중국의 생산 감축, 전력 부족, 환경 검사 등의 요인이 도료, 플라스틱, 종이 분야 수요 변동과 겹쳤기 때문입니다. 코일의 흰색이나 파스텔 색상은 이산화티타늄에 크게 의존하고 있기 때문에 분기별 가격 변동은 이익률을 압박하거나, 고객을 불안하게 만드는 가격 전가 조항의 발동을 초래하고 있습니다. 폴리에스터와 아크릴 수지는 업스트림 석유화학 사이클의 영향을 받기 때문에 아시아의 원료 공급 혼란은 몇 주 이내에 전 세계 공급망 전체로 파급될 가능성이 있습니다. 생산자들은 조달처 다각화, 안전 재고 확충, 또는 대체 안료 배합 등을 통해 리스크를 헤지하고 있지만, 이러한 대책은 운전자금을 부풀리고 배합의 안정성을 저해하는 요인이 됩니다.
부문 분석
폴리에스테르계 도료는 낮은 단가, 폭넓은 색상 범위, 그리고 다양한 프라이머 및 기질과의 높은 호환성 덕분에 2025년 매출의 66.84%를 차지했습니다. 최근 고고형분 및 내후성 하이브리드 제품에 대한 투자로 인해, 중저가 건축자재 및 가전제품용 프로그램에서 그 입지가 더욱 공고해졌습니다. 폴리에스테르 제품의 코일 코팅 시장 규모는 현재 24억 3,000만 달러를 넘어섰으며, 아시아의 위탁 코팅 업체들의 생산 라인 가동률을 뒷받침하고 있습니다. 생산량은 적지만, 건축가들이 대형 상업시설의 파사드에서 30년 보증과 깊이 있는 색조의 미관을 중시함에 따라 PVDF 등급은 2031년까지 연평균 성장률(CAGR) 3.63%로 성장을 지속하고, 있습니다. PVDF가 차지하는 코일 코팅 시장 점유율 확대는 고온 기후 지역에서 최저 태양 반사율 값을 규정하는 ‘쿨 루프(Cool Roof)’ 규제에 의해 더욱 가속화되고 있습니다.
PFAS가 포함되지 않은 불소 수지로의 전환은 치열한 연구 개발(R&D) 경쟁을 촉발하고 있습니다. NOF 메탈 코팅스 그룹은 기존의 내후성 지표를 충족하는 파일럿 배치를 공개하며, 규제 준수가 가능한 프리미엄 탑코트를 실현할 수 있는 길을 제시했습니다. 셔윈-윌리엄스(Sherwin-Williams)사의 ‘RadGuard’ 방사선 경화 제품 라인은 또 다른 혁신적인 방향을 제시하고 있습니다. 이는 자외선(UV) 조사에 의한 중합 기술로, 이를 통해 천연가스 사용량을 줄이고 생산 라인 속도를 향상시킬 수 있어 탄소 발자국 감소를 원하는 도장 업체들에게 매력적인 선택지입니다. 고객들이 입찰을 비용뿐만 아니라 내재된 탄소량과 재활용 가능성까지 기준으로 평가하게 됨에 따라, 신뢰할 수 있는 환경 데이터를 보유한 수지 공급업체는 코일 코팅 시장 전체에서 시장 점유율을 확대할 것으로 전망됩니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 49.88%를 차지할 것으로 보이며, 일부 지역에서 철강 공급 과잉 현상이 나타나고 있음에도 불구하고 2031년까지 연평균 성장률(CAGR) 3.73%를 기록할 전망입니다. 중국에서는 경기 부양책에 힘입은 철도 및 전기차(EV) 충전 인프라 구축이 내수 수요를 뒷받침하고 있는 반면, 수출 지향적인 코일 코팅 생산 라인은 아세안(ASEAN) 전역의 가전 산업 클러스터에 제품을 공급하고 있습니다. 일본은 원양 선박용 조선소 및 국내 주요 가전 제조업체와의 장기 공급 계약을 활용하여 고품질 PVDF 수요를 유지하고 있습니다. 한편, 한국의 주요 가전 기업은 수출 시장용 물류를 최적화하기 위해 추가 생산량을 베트남의 위탁 코팅 업체에 외주하고 있습니다. 인도에서는 스마트 시티 계획과 농촌 지역의 전기화가 진행되면서 아연 도금 지붕 자재 및 아그리볼타익 구조물에 대한 수주가 확대되고 있지만, 가격에 대한 민감성으로 인해 현지 폴리에스테르 배합재가 선호되고 있습니다.
북미는 여전히 기술 중심의 자세를 유지하고 있으며, 단순한 성장보다는 규제 준수 및 내구성을 중시하고 있습니다. 미국의 코일 코팅 시장 규모는 리모델링 붐과 에너지 절약형 지붕에 대한 세제 혜택의 수혜를 받고 있습니다. 사우스코스트 대기질 관리 구역에 의한 VOC 배출 상한선 강화로 인해 고고형분 도료의 채택이 가속화되고 있으며, 서부 해안의 생산 라인에서는 설비 투자를 통한 업그레이드가 진행되고 있습니다. 캐나다의 추운 기후로 인해, 동결·융해 주기를 견딜 수 있도록 설계된 유연한 폴리우레탄으로 코팅된 단열 패널에 대한 수요가 증가하고 있습니다. 한편, 멕시코는 미국의 OEM 제조업체와 지리적으로 가까워 USMCA(미국·멕시코·캐나다 협정)의 무역 규정 하에서 가전제품의 수주 잔고가 안정적입니다.
성숙한 시장인 유럽에서는 지속가능성 인증과 추적성이 중요시되고 있습니다. 탄소 국경 조정 조치와 확대 생산자 책임 제도에 따라 제철소 및 코팅 제조업체는 ‘크래들-투-게이트’ 배출량을 문서화해야 하며, 검증된 환경 제품 선언(EPD)을 보유한 공급업체에게는 우대 조치가 취해지고 있습니다. 독일의 개보수 보조금 제도는 PVDF를 선호하는 쿨 루프로의 개보수를 촉진하고 있으며, 프랑스의 아그리볼타익(농업과 태양광 발전의 융합)에 대한 보조금은 내식성 프레임에 대한 수요를 가속화하고 있습니다. 또한 북유럽 국가들에서는 주택 건설 시 스탠딩 심 금속 지붕에 무광 마감 폴리에스테르가 계속해서 지정되고 있습니다. 남미 및 중동 및 아프리카은 현재 공급량이 적지만, 매우 큰 잠재력을 지니고 있습니다. 브라질의 해안 휴양지에서는 내염수 분무성 코팅이 의무화되어 있는 반면, 걸프 연안 지역의 물류 허브에서는 극심한 자외선에 노출되는 환경에서 색이 바래기 어려운 창고용 외벽재가 채택되고 있습니다. 이처럼 지역적으로 광범위하게 분산되어 있어, 코일 코팅 시장은 특정 지역에 기인한 충격으로부터 보호받고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the coil coatings market size is expected to grow from USD 3.63 billion in 2025 to USD 3.75 billion in 2026 and is forecast to reach USD 4.41 billion by 2031 at 3.28% CAGR over 2026-2031.
This report is Segmented by Resin Type (Polyester, Polyvinylidene Fluoride, Polyurethane, Plastisols, and Other Resin Types), End-User Industry (Building and Construction, Industrial and Domestic Appliances, Transportation, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Coil Coatings Market Trends and Insights
Construction Steel Demand Upswing
Recovering construction steel orders drive greater use of pre-coated coil because builders can eliminate on-site painting delays, mitigate weather risks, and lower labor costs. The World Steel Association signals a 2025 rebound in global steel demand, with non-residential and infrastructure spending pushing volumes in the United States, China, and India. Governments channel stimulus into bridges, schools, and renewable-energy projects, favoring corrosion-resistant coil-coated panels. Modular construction firms increasingly specify factory-finished sheets to standardize quality and compress project timelines. Polyester and PVDF coatings with 20- to 30-year warranties support this momentum by lowering total maintenance expense. These factors underpin a significant share of future coil coatings market growth.
Energy-efficient Appliances Expansion
Appliance OEMs (original equipment manufacturers) specify coil coatings to satisfy thermal performance and design demands. Heat-pump outdoor units require finishes that survive freeze-thaw cycles while retaining heat-transfer efficiency, a need highlighted by the United States Department of Energy's incentive programs. Korean manufacturers Samsung and LG are scaling premium built-in product lines worth USD 64.5 billion globally, with color-matched, scratch-resistant coatings acting as brand differentiators. Engineers must ensure chemical compatibility as refrigeration moves to low-GWP (Global Warming Potential) refrigerants; advanced polyester-silicone hybrids provide the necessary barrier. Luxury real-estate trends toward integrated kitchens elevate aesthetic expectations, pressuring suppliers to offer deep-hue, high-gloss coil options. These dynamics create durable demand pockets inside the coil coatings market.
Volatile Titanium Dioxide and Resin Prices
Titanium dioxide (TiO2) markets experienced rapid price oscillations throughout 2024 as Chinese output cuts, power shortages, and environmental inspections collided with uneven demand from coatings, plastics, and paper. Because white and pastel coil colors rely heavily on TiO2, quarter-to-quarter swings erode margins or trigger pass-through clauses that unsettle customers. Polyesters and acrylic resins follow upstream petrochemical cycles, so feedstock disruptions in Asia can ripple across global supply chains within weeks. Producers hedge by expanding multi-sourcing, raising safety stocks, or blending alternative pigments, yet these tactics inflate working capital and complicate formulation stability.
Other drivers and restraints analyzed in the detailed report include:
- Stricter VOC and Carbon Regulations
- Shift toward High-Durability Exterior Panels
- Plastic and Composite Material Substitution
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyester chemistries represented 66.84% of 2025 revenue thanks to low unit cost, broad color gamut, and compatibility with a spectrum of primers and backers. Recent investments in high-solids and weather-resistant hybrids strengthen their foothold in mid-range building and appliance programs. The coil coatings market size for polyester products eclipses USD 2.43 billion today, underpinning line utilization across Asia's contract coaters. Although smaller in volume, PVDF grades post a 3.63% CAGR to 2031 as architects prioritize 30-year warranties and deep-tone aesthetics in large commercial facades. The coil coatings market share grabbed by PVDF is further fueled by cool-roof codes in hot climates that specify minimum solar-reflectance values.
Transitioning to PFAS-free fluoropolymers has initiated an intense R&D (research and development) race. NOF Metal Coatings Group unveiled pilot batches that match traditional weathering metrics, signaling viable pathways to regulation-proof premium topcoats. Sherwin-Williams' RadGuard radiation-cure line illustrates another innovation vector: UV-triggered polymerization that trims natural-gas usage and raises line speed, appealing to coaters eager to curb carbon footprints. As customers judge bids not only on cost but also on embodied carbon and recyclability, resin suppliers with credible environmental data stand to gain wallet share across the coil coatings market.
Complete Report Scope:
- By Resin Type
- Polyester
- Polyvinylidene Fluoride (PVDF)
- Polyurethane (PU)
- Plastisols
- Other Resin Types
- By End-user Industry
- Building and Construction
- Industrial and Domestic Appliances
- Transportation
- Furniture
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 49.88% of global revenue in 2025 and is on track for a 3.73% CAGR to 2031 despite pockets of steel oversupply. China's stimulus-backed rail and EV charging buildout cushions domestic demand, while export-oriented coil lines feed appliance clusters across ASEAN. Japan leverages long-term supply deals with ocean-going shipyards and home-grown appliance majors to sustain premium PVDF demand, whereas South Korea's appliance giants outsource additional tonnage to Vietnamese toll coaters to optimize logistics for export markets. India's smart-city schemes and rural electrification spur orders for galvanized roofing and agrivoltaic structures, though price sensitivity favors local polyester formulations.
North America remains technology-focused, emphasizing regulatory compliance and durability over sheer growth. The coil coatings market size in the United States benefits from a remodeling boom and tax incentives for energy-efficient roofs. Stricter VOC caps from the South Coast Air Quality Management District accelerate high-solids adoption and drive capital upgrades among West Coast lines. Canada's colder climate elevates insulation panels coated with flexible polyurethanes designed to withstand freeze-thaw cycles, while Mexico's proximity to United States OEMs secures appliance backlog stability under USMCA (United States-Mexico-Canada Agreement) trade provisions.
Europe's mature landscape values sustainability badges and traceability. Carbon-border adjustments and extended producer-responsibility schemes push mills and coaters to document cradle-to-gate emissions, rewarding suppliers with verified EPDs. Germany's refurbishment grants promote cool-roof retrofits that favor PVDF, France's agrivoltaic subsidies accelerate demand for corrosion-resistant framing, and the Nordics continue to specify matte polyesters for standing-seam metal roofs in residential constructions. South America and the Middle East & Africa contribute modest volumes but outsize potential; Brazil's coastal resorts mandate anti-salt-spray coatings, while Gulf logistics hubs commission color-fast warehouse cladding amid extreme UV exposure. The overall geography spread insulates the coil coatings market against single-region shocks.
- Coil Coaters
- Paint Suppliers
- Pretreatment, Resins, Pigments, Equipment
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Construction Steel Demand Upswing
- 4.2.2 Energy-efficient Appliances Expansion
- 4.2.3 Stricter VOC and Carbon Regulations
- 4.2.4 Shift toward High-Durability Exterior Panels
- 4.2.5 Agrivoltaic Metal Framing Boom
- 4.3 Market Restraints
- 4.3.1 Volatile Titanium Dioxide and Resin Prices
- 4.3.2 Plastic and Composite Material Substitution
- 4.3.3 PFAS-free Fluoropolymer Reformulations
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Polyester
- 5.1.2 Polyvinylidene Fluoride (PVDF)
- 5.1.3 Polyurethane (PU)
- 5.1.4 Plastisols
- 5.1.5 Other Resin Types
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Industrial and Domestic Appliances
- 5.2.3 Transportation
- 5.2.4 Furniture
- 5.2.5 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Coil Coaters
- 6.4.1.1 ArcelorMittal
- 6.4.1.2 Arconic
- 6.4.1.3 BDM Coil Coaters
- 6.4.1.4 CENTRIA
- 6.4.1.5 CHEMCOATERS
- 6.4.1.6 Goldin Metals Inc.
- 6.4.1.7 Jupiter Aluminum Corporation
- 6.4.1.8 Norsk Hydro ASA
- 6.4.1.9 Novelis
- 6.4.1.10 RALCO STEELS PRIVATE LIMITED
- 6.4.1.11 Salzgitter Flachstahl GmbH
- 6.4.1.12 Tata Steel
- 6.4.1.13 Tekno Kroma
- 6.4.1.14 thyssenkrupp AG
- 6.4.1.15 UNICOIL
- 6.4.1.16 United States Steel Corporation
- 6.4.2 Paint Suppliers
- 6.4.2.1 Akzo Nobel N.V.
- 6.4.2.2 Axalta Coating Systems, LLC
- 6.4.2.3 Beckers Group
- 6.4.2.4 Brillux GmbH & Co. KG
- 6.4.2.5 Hempel A/S
- 6.4.2.6 Kansai Paint Co., Ltd.
- 6.4.2.7 Nippon Paint Holdings Co., Ltd
- 6.4.2.8 NOROO Coil Coatings Co., Ltd.
- 6.4.2.9 PPG Industries, Inc.
- 6.4.2.10 The Sherwin-Williams Company
- 6.4.2.11 Yung Chi Paint & Varnish Mfg Co. Ltd
- 6.4.3 Pretreatment, Resins, Pigments, Equipment
- 6.4.3.1 Arkema
- 6.4.3.2 Covestro AG
- 6.4.3.3 Evonik Industries AG
- 6.4.3.4 Henkel AG & Co. KgaA
- 6.4.3.5 Wacker Chemie AG
- 6.4.1 Coil Coaters
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


