

|
시장보고서
상품코드
2121320
브레이징 합금 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Braze Alloys - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
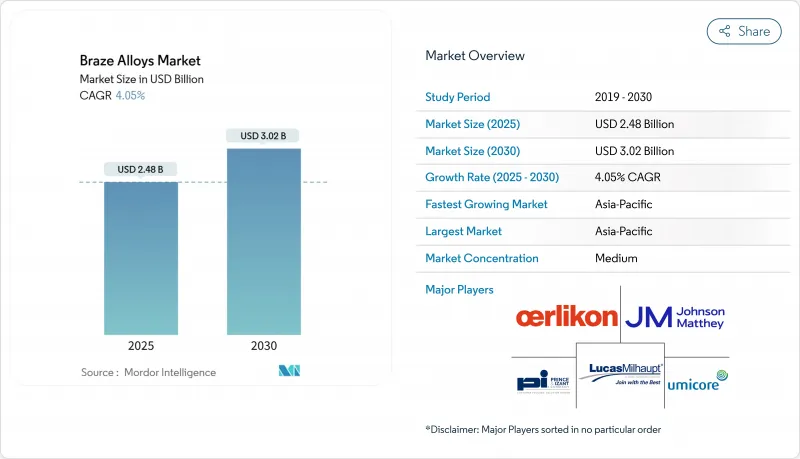
에 따르면 브레이징 합금 시장 규모는 2026년에 25억 8,000만 달러로 추정되며, 예측 기간(2026-2031년) 동안 CAGR 4.12%를 기록하며 2031년까지 31억 6,000만 달러에 달할 것으로 전망됩니다.
본 보고서는 비철금속(구리, 은, 금, 기타), 필러 형태(분말, 페이스트, 포일·리본, 기타), 온도 범위(저온, 중온, 고온), 최종사용자 산업(자동차, 항공우주·방위, 전기·전자기기, 기타), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 브레이징 합금 시장의 동향 및 인사이트
용접 및 납땜을 대체하는 브레이징의 도입
제조업체들은 브레이징으로의 전환을 추진하고 있습니다. 이는 브레이징이 모재의 항복 강도의 90%에 가까운 접합 강도를 확보하면서도, 용접 후 종종 발생하는 열영향부(HAZ)의 균열을 피할 수 있기 때문입니다. 현재 알루미늄 라디에이터 생산에서는 제어된 주변 환경의 용광로가 주류를 이루고 있으며, 불량률을 8%에서 2% 이하로 줄여 조립 라인 1개당 연간 최대 180만 달러의 비용 절감을 실현하고 있습니다. 납땜의 경우, 보닛 내부의 150℃라는 작동 주기에 대응할 수 없기 때문에 각 OEM 업체들은 전기 구동 플랫폼용으로 브레이징된 버스바와 냉각판을 점점 더 많이 지정하고 있습니다. 설비 공급업체에 따르면, 2025년에 수주요 새로운 브레이징로의 60%는 그동안 스폿 용접에 의존해 왔던 중국과 멕시코의 자동차 Tier 1 제조업체용이었다고 합니다.
자동차용 열교환기에서 알루미늄계 브레이징 재료 수요 급증
실리콘 함량이 7-12% 범위인 Al-Si계 브레이징 재료는 여전히 열교환기 코어의 주류를 이루고 있으며, 배터리 전기자동차(BEV)에서는 내연 기관 레이아웃에 비해 표면적 요구 사항이 2-3배 증가했습니다. 현재 일반적인 EV 배터리 팩에는 최대 6개의 액체 냉각 회로가 탑재되어 있으며, 각 회로에서 150,000km의 수명 동안 누출률이 1g/년 이하임을 보장하고 있습니다. 전 세계 OEM 업체들이 공급망 다각화를 추진하는 가운데, 2025 회계연도 인도의 부품 수출은 18% 증가했습니다. 망간과 구리를 첨가한 합금 개량을 통해 가속 열충격 시험에서의 피로 수명이 25% 연장되어, 공급업체가 보증 목표를 달성하는 데 도움이 되고 있습니다.
비귀금속 가격 변동
2024년부터 2025년까지 은 가격은 트로이 온스당 22달러에서 32달러 사이에서 변동했습니다. 가격이 10% 상승할 때마다 완제품 합금의 원가는 최대 6% 상승하지만, 연간 계약으로 인해 가격 전가가 9개월 지연되어 이익률에 압박이 가해지고 있습니다. 구리 가격 역시 톤당 8,200달러에서 10,500달러 사이에서 변동하며, HVAC-R용 필러의 수익성에 영향을 미치고 있습니다. 헤지 프로그램이 없는 소규모 공급업체들은 연구개발비 지출을 미루고 있어, 신합금 개발이 지연되고 있습니다.
부문별 분석
구리계 필러는 2025년에 브레이징 합금 시장 점유율의 35.92%를 차지했으며, 이는 HVAC-R 코일 및 배전용 버스바의 낮은 단가를 반영한 것입니다. 니켈 및 코발트 계열을 포함한 기타 비철금속 부문은 항공우주용 터빈 블레이드 개조 및 SiC 파워 모듈 채택을 호재로 삼아 연평균 성장률(CAGR) 4.82%를 기록할 것으로 전망됩니다. 금과 은 필러는 생체적합성과 열 안정성이 요구되는 고신뢰성 틈새 시장을 차지하고 있어, 이에 따라 높은 가격 책정이 정당화됩니다. 알루미늄·실리콘 합금은 자동차용 열교환기의 기반이 되며, 제어된 주변 환경에서의 브레이징을 통해 얇은 두께 구조와 내식성을 실현하고 있습니다.
가공성과 내열 온도의 상한이 채택 곡선을 결정짓고 있습니다. 구리·인계 합금은 700-850℃에서 용융되며, 냉매 회로에서 처리 능력과 접합 강도의 균형을 맞추고 있습니다. 니켈·크롬·붕소계 합금은 1,000℃ 및 산화성 배가스를 견디며, 터빈 수리에 적합합니다. 제조사가 새로운 가동 주기에 맞춰 성능 범위를 조정하는 가운데, 이러한 차이가 브레이징 합금 시장의 기반을 형성하고 있습니다.
봉·와이어 형태는 2025년 시장 규모의 40.04%를 차지하며 여전히 베스트셀러로, 수동 토치 작업이나 배치로에서 사용하기에 선호됩니다. 그러나 전기자동차 인버터 조립 라인에서 유도 브레이징용 로봇 기술의 보급으로 인해 링과 프리폼은 연평균 성장률(CAGR) 5.04%로 성장하고 있습니다. 미리 성형된 알루미늄·실리콘 링을 사용함으로써, 한 번의 용광로 처리당 최대 16개의 콜드 플레이트 포트를 동시에 접합할 수 있게 되어, 택트 타임을 35% 단축하고 초기 수율을 향상시키고 있습니다.
분말 및 페이스트 형태의 필러는 전자기기 및 소규모 접합 작업에서 주류를 이루고 있으며, 스크린 인쇄나 디스펜싱 헤드를 사용하여 ±0.01그램의 정밀도로 0.05그램의 충전량을 도포합니다. 박막이나 리본 형태의 제품은 항공우주 분야의 허니콤 구조에 대응하며, 용융층을 균일하게 형성함으로써 브레이징 재료 부족으로 인한 접합 부위를 방지할 수 있습니다. 그 결과, 다양한 형태의 제품군이 형성되어 브레이징 합금 시장은 자동화 동향에 유연하게 대응하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 46.38%를 차지하며, 중국의 BEV(배터리 전기자동차) 생산 대수 900만 대와 인도의 열교환기 수출의 두 자릿수 성장에 힘입어 2031년까지 연평균 5.16%의 성장이 예상됩니다. 일본은 터빈 부품용으로 정밀한 니켈계 브레이징을 공급하는 한편, 한국의 배터리 팩 생산 라인에서는 누출이 없는 알루미늄 콜드 플레이트의 접합이 요구되고 있습니다. 동남아시아는 비용이 높은 중국 각 성에서 이전해 오는 생산을 흡수하고 있으며, 베트남에서는 전자기기의 수탁 제조가 확대되고 있습니다.
북미의 브레이징 합금 수요는 고온용 니켈 필러가 필요한 항공우주 부문의 MRO(정비·수리·점검) 활동이 주도하고 있습니다. 멕시코는 무역 협정 및 니어쇼어링 동향을 활용하여 80억 달러 상당의 열 관리 모듈을 수출했습니다. 미국은 ‘인플레이션 억제법’의 혜택을 받고 있으며, 이 법에 따라 국내 인버터 및 배터리 조립에 자금이 투입됨에 따라 현지 필러 분말 수요가 확대되고 있습니다.
유럽은 2025년에 상당한 시장 점유율을 차지했으나, 유해 금속 금지와 관련된 규정 준수 비용에 직면해 있습니다. 독일의 자동차 부문은 구리와 알루미늄 필러 사용을 주도하고 있는 반면, 프랑스는 제트 엔진 부품용으로 니켈 필러에 의존하고 있습니다. 북유럽 국가들은 진공 브레이징된 선박용 열교환기에 투자하고 있습니다. 남미, 중동 및 아프리카는 각각 금액 기준으로 5% 미만의 공급에 그치고 있지만, 브라질의 자동차 생산 및 걸프 지역의 HVAC 건설과 연계되어 꾸준한 성장을 기록하고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the braze alloys market size is estimated at USD 2.58 billion in 2026, and is expected to reach USD 3.16 billion by 2031, at a CAGR of 4.12% during the forecast period (2026-2031).
This report is Segmented by Base Metal (Copper, Silver, Gold, and More), Filler Form (Powder, Paste, Foil/Ribbon, and More), Temperature Range (Low, Medium, and High), End-User Industry (Automotive, Aerospace and Defense, Electrical and Electronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Braze Alloys Market Trends and Insights
Adoption of Brazing Over Welding and Soldering
Manufacturers are pivoting toward brazing because it secures joint strengths approaching 90% of parent-metal yield while avoiding heat-affected-zone cracking that often follows fusion welding. Controlled-atmosphere furnaces now dominate aluminum radiator production, cutting scrap from 8% to under 2% and saving up to USD 1.8 million per assembly line annually. Soldering cannot meet 150 °C under-hood duty cycles, so OEMs increasingly specify brazed busbars and cooling plates for electric-drive platforms. Equipment suppliers confirm that 60% of all new brazing furnace orders booked in 2025 were for automotive Tier-1 plants in China and Mexico, regions that previously relied on spot welding.
Surging Demand for Aluminum-Based Brazes in Automotive Heat Exchangers
Al-Si brazes in the 7-12 % silicon range remain the backbone of heat-exchanger cores, and battery electric vehicles multiply surface-area requirements two to three times versus internal-combustion layouts. A typical EV pack now houses up to six liquid-cooling circuits, each demanding leak-rate guarantees below 1 g/year over a 150,000 km service life. India's component exports grew 18% in fiscal 2025 as global OEMs diversified their supply chains. Alloy tweaks that add manganese and copper are extending fatigue life by 25% in accelerated thermal-shock tests, helping suppliers meet warranty targets.
Base-Metal Price Volatility
Silver prices swung between USD 22 and USD 32 per troy ounce during 2024-2025. Every 10% uptick pushes finished alloy cost by up to 6%, yet annual contracts delay pass-through for nine months, pressuring margins. Copper prices likewise fluctuated from USD 8,200 to USD 10,500 per metric ton, hitting HVAC-R filler economics. Smaller suppliers lacking hedging programs defer research and development spending, slowing new alloy development.
Other drivers and restraints analyzed in the detailed report include:
- EV Power-Electronics Uptake of Nickel-Based Induction Pastes
- Growth of the HVAC-R Industry Raising Braze Consumption
- Toxic-Metal (Cd, Pb) Regulatory Bans
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Copper-based fillers captured 35.92% of the braze alloys market share in 2025, reflecting their low unit cost in HVAC-R coils and power-distribution busbars. The other base metals segment, including Nickel and cobalt systems, is forecast for a 4.82% CAGR, riding on aerospace turbine-blade refurbishment and SiC power module adoption. Gold and silver fillers occupy high-reliability niches where biocompatibility or thermal stability warrants premium pricing. Aluminum-silicon alloys underpin vehicle heat exchangers, with controlled-atmosphere brazing enabling thin-wall geometries and corrosion resistance.
Processability and temperature ceilings explain adoption curves. Copper-phosphorus compositions melt at 700-850 °C, balancing throughput and joint strength for refrigerant circuits. Nickel-chromium-boron blends withstand 1,000 °C and oxidative exhaust gases, suiting turbine repairs. These distinctions underpin the braze alloys market as manufacturers match performance envelopes to new duty cycles.
Rod and wire formats remained top-selling at 40.04% of the 2025 value, favored in manual torch operations and batch furnaces. However, rings and preforms are growing at 5.04% CAGR thanks to induction-brazing robotics in EV inverter assembly lines. Pre-shaped aluminum-silicon rings allow simultaneous joining of up to 16 cold-plate ports per furnace run, trimming takt time by 35% and lifting first-pass yield.
Powder and paste fillers dominate electronics and small-joint work, where screen-printing and dispensing heads deposit 0.05-gram charges with +-0.01-gram accuracy. Foil and ribbon variants address aerospace honeycomb structures, delivering uniform melt layers that avoid starved joints. The outcome is a diverse form-factor portfolio that keeps the braze alloys market responsive to automation trends.
Complete Report Scope:
- By Base Metal
- Copper
- Silver
- Gold
- Aluminum
- Other Base Metals (Nickel,Cobalt, etc.)
- By Filler Form
- Powder
- Paste
- Foil / Ribbon
- Rod / Wire
- Rings and Preforms
- By Temperature Range
- Low-Temperature (Less than 450 °C)
- Medium-Temperature (450-800 °C)
- High-Temperature (Greater than 800 °C)
- By End-User Industry
- Automotive
- Aerospace and Defense
- Electrical and Electronics
- Construction
- Other End-User Industries(Medical Devices, Energy and Power, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 46.38% of 2025 revenue and is projected to grow 5.16% annually through 2031, driven by China's 9 million BEV output and India's double-digit heat-exchanger export growth. Japan supplies precision nickel-based brazing for turbine components, whereas South Korea's battery-pack lines demand tight-leak aluminum cold-plate joints. Southeast Asia captures production relocating from higher-cost Chinese provinces, with Vietnam scaling electronics contract manufacturing.
North America's braze alloys demand is led by aerospace MRO activity requiring high-temperature nickel fillers. Mexico exported USD 8 billion in thermal-management modules, leveraging trade agreements and near-shoring trends. The United States benefits from the Inflation Reduction Act, which funds domestic inverter and battery assembly, thereby enlarging local filler-powder demand.
Europe accounted for a considerable market share in 2025 but faces compliance costs tied to toxic-metal bans. Germany's automotive sector drives copper and aluminum filler use, whereas France leans on nickel fillers for jet-engine parts. Nordic countries invest in vacuum-brazed marine heat exchangers. South America and the Middle East and Africa each supplied under 5% of value yet register steady growth tied to Brazilian vehicle output and Gulf HVAC construction.
- Aimtek, Inc.
- Bellman-Melcor, LLC
- Cupro Alloys Corporation
- Fusion, Inc.
- Indian Solder and Braze Alloys Pvt. Ltd.
- Johnson Matthey
- Lucas-Milhaupt Inc.
- Materion Corporation
- Morgan Advanced Materials plc
- Nihon Superior Co., Ltd.
- OC Oerlikon Management AG
- Prince & Izant Company
- Saru Silver Alloy Private Limited
- Sulzer Ltd
- The Lincoln Electric Company
- Umicore
- VBC Group
- Wall Colmonoy
- Wieland Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Adoption of brazing over welding and soldering
- 4.2.2 Surging demand for Aluminum based brazes in automotive heat-exchangers
- 4.2.3 EV power-electronics uptake of Ni-based induction pastes
- 4.2.4 Growth of the HVAC-R industry increasing demand for brazes
- 4.2.5 Emergence of high-entropy braze alloys for extreme environments
- 4.3 Market Restraints
- 4.3.1 Base-metal price volatility
- 4.3.2 Toxic-metal (Cd, Pb) regulatory bans
- 4.3.3 Shortage of furnace-qualified labour
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Base Metal
- 5.1.1 Copper
- 5.1.2 Silver
- 5.1.3 Gold
- 5.1.4 Aluminum
- 5.1.5 Other Base Metals (Nickel,Cobalt, etc.)
- 5.2 By Filler Form
- 5.2.1 Powder
- 5.2.2 Paste
- 5.2.3 Foil / Ribbon
- 5.2.4 Rod / Wire
- 5.2.5 Rings and Preforms
- 5.3 By Temperature Range
- 5.3.1 Low-Temperature (Less than 450 °C)
- 5.3.2 Medium-Temperature (450-800 °C)
- 5.3.3 High-Temperature (Greater than 800 °C)
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Aerospace and Defense
- 5.4.3 Electrical and Electronics
- 5.4.4 Construction
- 5.4.5 Other End-User Industries(Medical Devices, Energy and Power, etc.)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 NORDIC Countries
- 5.5.3.7 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aimtek, Inc.
- 6.4.2 Bellman-Melcor, LLC
- 6.4.3 Cupro Alloys Corporation
- 6.4.4 Fusion, Inc.
- 6.4.5 Indian Solder and Braze Alloys Pvt. Ltd.
- 6.4.6 Johnson Matthey
- 6.4.7 Lucas-Milhaupt Inc.
- 6.4.8 Materion Corporation
- 6.4.9 Morgan Advanced Materials plc
- 6.4.10 Nihon Superior Co., Ltd.
- 6.4.11 OC Oerlikon Management AG
- 6.4.12 Prince & Izant Company
- 6.4.13 Saru Silver Alloy Private Limited
- 6.4.14 Sulzer Ltd
- 6.4.15 The Lincoln Electric Company
- 6.4.16 Umicore
- 6.4.17 VBC Group
- 6.4.18 Wall Colmonoy
- 6.4.19 Wieland Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Development of Vacuum Brazing Technology


