

|
시장보고서
상품코드
2121321
중동의 해양지원선 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Middle East Offshore Support Vessels - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
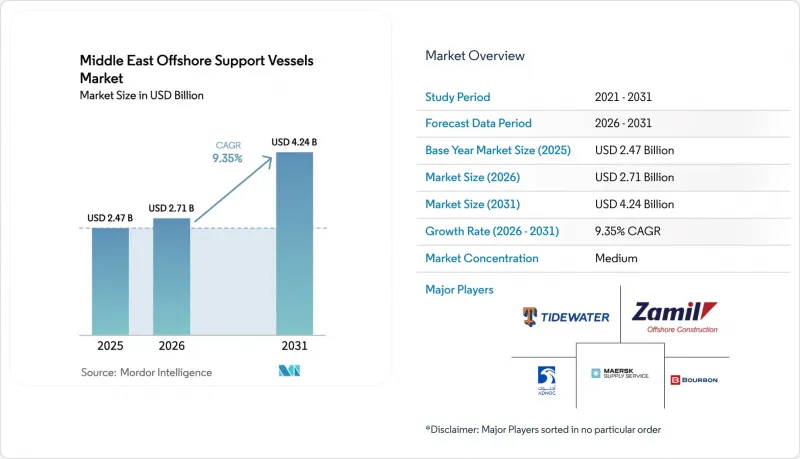
에 따르면 중동의 해양지원선 시장 규모는 2025년에 24억 7,000만 달러, 2026년에 27억 1,000만 달러에 달하고, 2031년까지 42억 4,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 CAGR 9.35%로 성장할 것으로 전망됩니다.
본 보고서는 선박 유형(앵커 핸들링 예인선/앵커 핸들링 예인·보급선, 플랫폼 보급선, 기타 선종), 용도(해상 석유·가스, 해상 풍력, 해상 설비 해체, 기타), 지역(사우디아라비아, 아랍에미리트, 카타르, 오만, 쿠웨이트, 바레인, 이란, 기타 중동)별로 분류되어 있습니다.
중동 해양지원선 시장의 동향 및 인사이트
해상 탐사·생산(E&P) 투자의 회복
사우디 아람코(Saudi Aramco)는 마르잔(Marjan) 증산 계획을 위한 124억 달러의 자금 조달을 확정했습니다. 이 계획은 2025년 말까지 일일 30만 배럴의 생산을 목표로 하고 있으며, 건설 기간 동안 18척 이상의 플랫폼 보급선(PSV)과 6척 이상의 앵커 핸들링 예인선이 필요할 것으로 보입니다. ADNOC는 하일 가샤 산성 가스 프로젝트를 승인했습니다. 이 프로젝트에서는 180km에 달하는 파이프라인 부설을 위해 고사양의 해저 건설 유닛이 필요합니다. 카타르 에너지의 노스 필드 확장 계획에서는 2027년까지 시추 및 해저 연결 작업을 지원하기 위해 80-100척의 전용 선박이 투입될 예정입니다. 이러한 계약으로 인해 현물 시장의 선박 공급은 감소하는 반면, 플랫폼 보급선 및 앵커 핸들링선 부문에서는 가동률이 높은 수준으로 유지될 것입니다. 아시아의 가스 수요 증가는 장기 용선 계약을 뒷받침하고 있으며, 선주들은 탄소 집약도 점수를 개선하는 하이브리드 추진 시스템으로의 개조를 정당화할 수 있게 되었습니다. 따라서 이 투자 주기는 수익 증대의 요인이자 기술 업그레이드의 계기가 되고 있습니다.
홍해·페르시아만 해상 풍력발전소 건설 확대
NEOM 그린 수소사는 아카바 만에서 4GW 규모의 풍력·태양광 복합 발전소 건설을 추진 중이며, 터빈 설치는 2027년으로 예정되어 있습니다. 이에 이어 이집트의 500MW 규모 홍해 풍력발전소가 2028년 일정에 따라 진행되고 있습니다. 해상 풍력발전소 건설 1기가와트당 통상 15-20척의 전용 지원선이 동원되므로, NEOM 프로젝트만으로도 60-80척에 달합니다. 현재 이 지역에서 풍력발전 인증을 받은 선박의 공급 수는 20척 이하이며, 이에 따라 PSV(지원선)에 A-프레임 및 동요 보상식 갱웨이 장비를 장착하는 개조가 진행되고 있습니다. DNV 또는 뷰로 베리타스의 기준에 따른 인증 획득에는 최대 18개월이 소요되므로, 단기적으로는 설비 부족이 발생할 것이며, 걸프 지역 조선소에서 개조를 신속하게 진행할 수 있는 사업자가 유리할 것입니다. 장기적으로는 풍력발전 프로젝트가 수익원을 다각화하고, 원유 가격 변동에 대한 의존도를 낮추게 될 것입니다.
불안정한 원유 가격 전망
브렌트 선물 가격은 2025년 내내 배럴당 70-90달러 범위에서 등락하고 있어, 탐사 프로그램의 예산 전망을 불투명하게 만들고 있습니다. 사우디 아람코는 가격 변동에 따라 2025년 2분기에 3개의 해양 광구에 대한 최종 투자 결정을 연기했으며, 이로 인해 PSV의 가동률이 직접적으로 하락했습니다. Tidewater사의 보고에 따르면, 브렌트 선물 계약의 평균 용선료가 10달러 하락할 때마다 분기 내 용선료율은 6-8% 하락한다고 합니다. 각 운영사는 국영 석유 회사와의 다년 계약을 우선시함으로써 리스크 헤지를 도모하고 있지만, 소규모 선단의 경우 현물 시장에 대한 노출도가 여전히 높은 상태입니다. 가격이 65달러 아래로 떨어질 경우, 콜드 스태킹이나 레이업으로 인해 2023년 이후 달성된 가동률 개선이 후퇴할 가능성이 있습니다. 반대로, 가격이 95달러 이상으로 유지된다면 연기되었던 프로젝트가 재개될 것이며, 가격 변동의 양날의 검과 같은 성격이 부각될 것입니다.
부문별 분석
2025년, 플랫폼 보급선은 중동 해양지원선 시장의 44.4%를 차지하고 있으며, 사파니아에서 자쿰에 이르기까지 시추 유체, 시멘트, 파이프를 시추 장비로 수송하는 그 다목적성을 반영하고 있습니다. 하이브리드 추진 시스템으로의 업그레이드를 통해 마스쿠 서플라이 서비스(Maersk Supply Services)는 4척의 DP2급 PSV를 도입했습니다. 이 선박들은 연료 소비량을 20% 절감하여, 사우디 아람코(Saudi Aramco)와의 다년 용선 계약에서 현재 의무화되어 있는 CII-A 목표를 충족하고 있습니다. 앵커 핸들링 예인·급유선은 수심 1,500미터를 초과하는 심해역에서 블록의 위치 설정 작업에 투입되고 있으나, 수요는 간헐적입니다. 해저 건설 유닛 및 승무원 수송선을 포함한 ‘기타 선종’ 부문은 NEOM의 풍력발전 일정과 카타르의 해저 타이백 공사를 배경으로 연평균 성장률(CAGR) 11.8%를 기록하며 가장 빠르게 성장할 전망입니다. 원격 조종 차량(ROV)을 탑재한 해저 작업선은 하이르-가샤 프로젝트의 파이프라인 검사를 위해 용선되는 사례가 증가하고 있어, 전문성이 경쟁상의 강점임을 여실히 보여주고 있습니다.
중동 해양지원선 시장에서 ‘기타 선종’의 규모가 급속히 확대됨에 따라, 선단 운영사들은 자본 배분을 재검토하고 있습니다. 부르봉은 풍력발전 프로젝트에 참여할 자격을 얻기 위해 6척의 PSV(플랫폼 보급선)에 300만-400만 달러를 투자하여 A-프레임 개조를 계획하고 있습니다. 대기용 크루 보트는 수익 면에서는 규모가 작지만, 24시간 체제로 인원 수송 능력이 요구되는 터빈 설치 시즌에는 수요가 정점에 달합니다. 이러한 특수한 성장에 따라 조선소에 대한 수요는 순수한 볼라드 풀 지표보다는 크레인, 갱웨이, 배터리 시스템 쪽으로 이동하고 있으며, 이는 사양상의 우선순위에 구조적인 변화가 일어나고 있음을 시사합니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the Middle East offshore support vessels market size is projected to be USD 2.47 billion in 2025, USD 2.71 billion in 2026, and reach USD 4.24 billion by 2031, growing at a CAGR of 9.35% from 2026 to 2031.
This report is Segmented by Vessel Type (Anchor Handling Tug/Anchor Handling Towing Supply Vessels, Platform Supply Vessels, and Other Types), Application (Offshore Oil and Gas, Offshore Wind, Offshore Decommissioning, and Other Applications), and Geography (Saudi Arabia, United Arab Emirates, Qatar, Oman, Kuwait, Bahrain, Iran, and Rest of Middle East)
Middle East Offshore Support Vessels Market Trends and Insights
Increasing Offshore E&P Spending Rebound
Saudi Aramco finalized USD 12.4 billion in funding for the Marjan increment, targeting 300,000 bpd by late 2025 and requiring more than 18 PSVs and six anchor-handling tugs across the construction window. ADNOC sanctioned the Hail & Ghasha sour-gas project, which needs high-specification subsea construction units for 180 km of pipeline lay. QatarEnergy's North Field expansion schedules 80-100 dedicated vessels to support drilling and subsea tie-ins through 2027. These commitments reduce spot availability and keep utilization elevated across platform supply and anchor-handling segments. Rising gas demand from Asia strengthens long-term charter tenors, allowing owners to justify hybrid-propulsion retrofits that improve carbon intensity scores. The spending cycle is therefore both a revenue catalyst and a technology-upgrade trigger.
Offshore Wind Farm Build-Out in Red Sea & Gulf
The NEOM Green Hydrogen Company is progressing a 4 GW wind-and-solar complex in the Gulf of Aqaba, with turbine installation slated for 2027. Egypt's 500 MW Red Sea wind farm follows on a 2028 timeline. Each gigawatt of offshore wind construction typically mobilizes 15-20 specialized support vessels, translating to 60-80 units for NEOM alone. Current regional supply of wind-certified tonnage is under 20 units, prompting PSV retrofits with A-frames and motion-compensated gangways. Certification under DNV or Bureau Veritas standards can take up to 18 months, creating a near-term equipment gap that favors operators able to fast-track modifications in Gulf yards. Long term, wind projects diversify revenue streams and lessen dependence on oil-price cycles.
Volatile Oil Price Outlook
Brent futures ranged between USD 70-90 per barrel through 2025, hampering budget visibility for exploration programs. Saudi Aramco postponed final investment decisions on three offshore blocks in Q2 2025 amid price swings, directly trimming PSV utilization. Tidewater reports that every USD 10 decline in Brent contracts average charter rates by 6-8% within a quarter. Operators hedge by prioritizing multi-year fixtures with national oil companies, yet spot exposure remains high for smaller fleets. If prices fall below USD 65, cold-stacking and lay-ups could reverse utilization gains achieved since 2023. Conversely, sustained prices above USD 95 would unlock deferred projects, underlining the double-edged nature of volatility.
Other drivers and restraints analyzed in the detailed report include:
- Fleet Renewal to Meet IMO CII/EEXI Rules
- Localization & In-Country-Value Mandates
- Surge in DP-Rig Spot Chartering Crowds Out OSVs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Platform supply vessels controlled 44.4% of the Middle East offshore support vessels market in 2025, reflecting their versatility in transporting drilling fluids, cement, and tubulars to rigs from Safaniya to Zakum. Hybrid-propulsion upgrades allowed Maersk Supply Service to introduce four DP2-class PSVs that cut fuel use by 20% and meet CII-A targets now required on multi-year Saudi Aramco charters. Anchor-handling tug supply vessels serve deep-water block positioning beyond 1,500 m, but demand is episodic. The Other Types segment, including subsea construction units and crew-transfer boats, will grow fastest at an 11.8% CAGR, propelled by NEOM's wind timetable and Qatar's subsea tie-backs. Subsea vessels equipped with remotely operated vehicles are increasingly chartered for pipeline inspection on the Hail & Ghasha project, underscoring specialization as a competitive moat.
Fleet operators are re-evaluating capital allocation as the Middle East offshore support vessels market size for Other Types rises quickly. Bourbon plans USD 3-4 million A-frame retrofits on six PSVs to gain wind-project eligibility. Standby crew boats, though small in revenue terms, enjoy peaks during turbine-installation seasons that require 24-hour personnel shuttle capability. Growth in these specialty categories tilts yard demand toward cranes, gangways, and battery systems rather than pure bollard-pull metrics, signaling a structural shift in specification priorities.
Complete Report Scope:
- By Vessel Type
- Anchor Handling Tug/Anchor Handling Towing Supply Vessels (AHT/AHTSs)
- Platform Supply Vessels (PSV)
- Other Types (MPSV, Subsea, Standy Crew)
- By Application
- Offshore Oil and Gas
- Offshore Wind
- Offshore Decommissioning
- Other Applications
- By Geography
- Saudi Arabia
- United Arab Emirates
- Qatar
- Oman
- Kuwait
- Bahrain
- Iran
- Rest of Middle East
List of Companies Covered in this Report:
- Tidewater Inc.
- Bourbon Corp. SA
- ADNOC Logistics & Services
- Maersk Supply Service
- Seacor Marine Holdings
- OFCO Offshore International
- Baltic Marine Services LLC
- Zamil Offshore Services
- Zakher Marine International
- Halul Offshore Services
- Topaz Energy & Marine (P&O Maritime Logistics)
- Swire Pacific Offshore
- Vallianz Holdings
- Rawabi Vallianz Offshore
- Solstad Offshore ASA
- DOF Group ASA
- Boskalis Westminster
- MMA Offshore Ltd
- Al Seer Marine
- Bahri - National Shipping Co. of Saudi Arabia
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing offshore E&P spending rebound
- 4.2.2 Offshore wind farm build-out in Red Sea & Gulf
- 4.2.3 Fleet renewal to meet IMO CII/EEXI rules
- 4.2.4 Localization & in-country-value mandates
- 4.2.5 Port & yard capacity upgrades in KSA & UAE
- 4.3 Market Restraints
- 4.3.1 Volatile oil price outlook
- 4.3.2 Surge in DP-rig spot chartering crowds out OSVs
- 4.3.3 Tightening regional carbon-intensity limits
- 4.3.4 Geopolitical choke-point disruptions
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Vessel Type
- 5.1.1 Anchor Handling Tug/Anchor Handling Towing Supply Vessels (AHT/AHTSs)
- 5.1.2 Platform Supply Vessels (PSV)
- 5.1.3 Other Types (MPSV, Subsea, Standy Crew)
- 5.2 By Application
- 5.2.1 Offshore Oil and Gas
- 5.2.2 Offshore Wind
- 5.2.3 Offshore Decommissioning
- 5.2.4 Other Applications
- 5.3 By Geography
- 5.3.1 Saudi Arabia
- 5.3.2 United Arab Emirates
- 5.3.3 Qatar
- 5.3.4 Oman
- 5.3.5 Kuwait
- 5.3.6 Bahrain
- 5.3.7 Iran
- 5.3.8 Rest of Middle East
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Tidewater Inc.
- 6.4.2 Bourbon Corp. SA
- 6.4.3 ADNOC Logistics & Services
- 6.4.4 Maersk Supply Service
- 6.4.5 Seacor Marine Holdings
- 6.4.6 OFCO Offshore International
- 6.4.7 Baltic Marine Services LLC
- 6.4.8 Zamil Offshore Services
- 6.4.9 Zakher Marine International
- 6.4.10 Halul Offshore Services
- 6.4.11 Topaz Energy & Marine (P&O Maritime Logistics)
- 6.4.12 Swire Pacific Offshore
- 6.4.13 Vallianz Holdings
- 6.4.14 Rawabi Vallianz Offshore
- 6.4.15 Solstad Offshore ASA
- 6.4.16 DOF Group ASA
- 6.4.17 Boskalis Westminster
- 6.4.18 MMA Offshore Ltd
- 6.4.19 Al Seer Marine
- 6.4.20 Bahri - National Shipping Co. of Saudi Arabia
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


