|
시장보고서
상품코드
2121376
알파 방사체 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Alpha Emitters - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
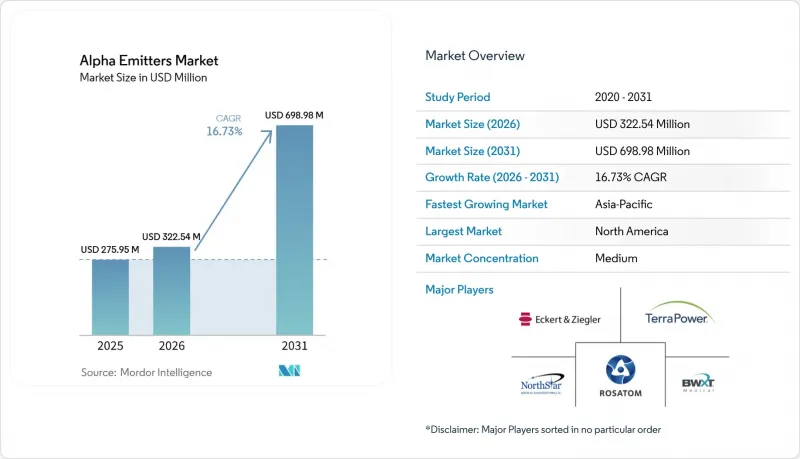
에 따르면 알파 방사체 시장 규모는 2025년에 2억 7,595만 달러로 평가되며, 2026년 3억 2,254만 달러에서 2031년까지 6억 9,898만 달러에 달할 것으로 추정되고 있으며, 예측 기간(2026-2031년)에 CAGR은 16.73%에 달할 전망입니다.
이 보고서는 방사성 핵종 유형(아스타틴-211, 라듐-223, 악티늄-225 등), 용도(전립선암, 골전이, 난소암, 췌장암, 내분비 종양, 기타),최종사용자(병원, 학술 의료 센터 등), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 알파 방사성 물질 시장의 동향 및 인사이트
치료가 어려운 고형암 발생률 증가가 수요를 견인
알파 방사성 물질 시장은 치료가 어려운 고형암, 특히 환자가 이전의 전신 요법에 충분한 반응을 보이지 않게된 경우의 치료 옵션에 대한 수요 증가와 밀접한 관련이 있습니다. 세계보건기구(WHO)는 2022년 2,000만 건에 비해 2050년에는 3,500만 건의 신규 암 사례가 발생할 것으로 예측하고 있으며, 이에 따라 추가적인 치료 옵션이 필요할 수 있는 난치성 및 전이성 질환 환자 수가 더욱 증가할 것으로 보입니다. 골 전이 및 내성 고형암이 중요하게 여겨지는 이유는 많은 환자가 화학요법, 안드로겐 경로 억제제 또는 원발 병변에 대해 이미 시행된 기타 치료를 받은 후에도 병세가 진행되고 있기 때문입니다. 알파선은 DNA의 이중 가닥 절단을 유발할 가능성이 있으며, 이는 종양이 이전 치료로 인한 손상을 복구하는 능력을 획득하여 기존 치료법에 대한 반응이 저하된 경우에 효과적입니다. 전립선암의 1차 치료법이 개선됨에 따라 생존 기간이 연장되었고, 치료 후반 단계에서 골 미세 전이를 겪는 환자가 증가하고 있습니다. 이로 인해 라듐-223의 임상적 적용 범위가 확대될 가능성이 있습니다. 핵의학 프로토콜이 업데이트됨에 따라 전이성 거세 저항성 전립선암 관리에서 다른 전신 요법 선택지가 모두 소진된 후뿐만 아니라 더 초기 단계에서도 방사성동위원소 요법을 고려할 것을 권장하게 되었습니다.
뛰어난 종양 사멸 효율이 임상의의 신뢰를 높입니다.
알파 입자는 40-90µm의 경로 길이에 걸쳐 50-230 keV/µm의 에너지를 방출하며, 기존 방사선에 비해 상대 생물학적 효능(RBE)이 3-7인 것으로 보고되고 있습니다. 이러한 물리적 특성으로 인해 주변 조직의 넓은 범위가 아닌 제한된 범위에만 방사선이 조사되므로, 불균일한 종양에 대한 사용이 지지받고 있습니다. 특히 전문적인 치료 계획이 필요한 약제의 경우, 의사가 검증된 근거와 일상 진료 경험을 모두 고려할 수 있다면 알파 방사성 물질 시장은 혜택을 볼 것입니다. 2026년 2월에 발표된 PEACE-3 임상시험의 최종 결과에 따르면 전이성 거세 저항성 전립선암 및 골 전이가 있는 환자에서라듐-223과 엔잘타미드의 병용 요법은 엔잘타미드 단독 요법에 비해 사망 위험을 24% 감소시켰습니다. 전체 생존 기간의 중앙값은 병용군에서 38.2개월, 엔잘타미드 단독군에서 32.6개월이었으며, 하저드비는 0.76(p=0.0096)으로, 치료 결정에 명확한 임상적 근거가 추가되었습니다. 방사선의 도달 범위가 짧기 때문에 인접한 정상 조직에 대한 선량 조사량이 제한될 가능성이 있으며, 이는 독성에 대한 우려, 재치료 검토, 국소 방사선 치료 옵션 검토시 의사의 판단에 영향을 미칠 수 있습니다.
생산 능력 부족이 공급 병목 현상을 유발
알파 방사성 물질 시장에서는 생산자들이 새로운 생산 능력에 투자하고 있음에도 불구하고 동위원소 생산량과 확대되는 임상 프로그램의 수요 사이에는 여전히 격차가 존재합니다. 악티늄-225의 반감기는 9.9일이므로, 제조, 품질 검사, 출하, 환자에게 투여하는 데 할당되는 시간은 제한적이며, 각 공정은 운영상 이전 공정의 결과에 의존하게 됩니다. 따라서 인증 시설 중 한 곳에서 혼란이 발생하면 대체 재고를 확보할 여지가 제한적이기 때문에 여러 연구 및 치료 일정이 동시에 지연될 가능성이 있습니다. cGMP 등급의 악티늄-225의 현재 공급원은 공급을 필요로 하는 후기 임상 시험 프로그램의 수에 비해 여전히 제한적이어서, 개발자 및 임상 시험 실시 기관에 집중 위험이 발생하고 있습니다. 방사성 의약품의 제조에는 일관된 품질로 상업적 이용이 가능해지기 전에 검증 및 cGMP 인증이 필요하므로 시설 건설만으로는 이 문제를 해결할 수 없습니다. 따라서 새로 발표된 생산 능력이 확보된다 하더라도, 특히 비정기적인 생산 로트가 아닌 안정적인 공급이 필요한 프로그램의 경우, 2027년까지 공급 압박이 지속될 가능성이 있습니다.
부문 분석
라듐-223은 2025년 알파 방사선체 시장에서 61.77%의 점유율을 차지했습니다. 이는 해당 물질이 여전히 유일하게 상업적으로 승인된 알파 방사성 물질이며, 확립된 임상적 위상을 가지고 있었기 때문입니다. 이러한 위상은 증상이 동반된 골 전이가 있는 전이성 거세 저항성 전립선암에서의 사용을 반영하며, 병원 측에서는 이미 적절한 치료 절차가 마련되어 있었습니다. PEACE-3 임상시험 및 시판 후 증거를 통해 적절한 환자에 대한 치료 경로에서 조기 도입을 지원할 수 있는 임상 정보가 추가되었습니다. 액티늄-225에는 막대한 개발 투자가 집중되고 있으며, 후기 단계 평가에 있는 프로그램이 여러개 있는 것은 물론, 개발을 지원하기 위한 cGMP 공급 계약도 증가하고 있습니다. 비스무트-212, 비스무트-213, 테르븀-149 등의 기타 방사성 핵종은 주로 학술연구, 전임상 시험 또는 초기 1상 임상시험 단계에 머물러 있으며, 반감기가 짧고 투여 방법에 제약이 있으며, 당분간은 상업적인 역할이 제한적입니다.
납-212는 2026-2031년에 연평균 성장률(CAGR) 29.57%를 기록할 것으로 예측되며, 알파 방사성 물질 시장에서 가장 빠르게 성장하는 방사성 핵종 범주가 될 전망입니다. 이 원소의 반감기는 10.6시간으로, 표지 및 임상 투여에 적합할 뿐만 아니라, 비스무트-212를 경유하는 붕괴 과정을 통해 종양 부위에 선량을 집중시키는 것을 목적으로 한 연속적인 알파선 및 베타선 방출을 얻을 수 있습니다. AlphaMedix사는 2024년 위장관-췌장 신경내분비종양(GEP-NET)에 대해 FDA의 획기적 치료제(Breakthrough) 지정을 획득했으며, Orano Med사는 2025년 12월 로슈(Roche)사와의 제휴를 확대했습니다. 또한 Bicycle Therapeutics사는 2025년 12월, EphA2·MT1-MMP를 표적으로 하는 펩티드 표적제를 사용하는 자사의 BRC 플랫폼을 위해 납-212의 엔드투엔드 공급망을 구축한다고 발표했습니다. 납-212 수요 확대에 따라 토륨-228 발생기 네트워크의 중요성이 높아지면서, 사이클로트론이나 원자로의 처리 능력에 의존하지 않는 형태로 공급 리스크 분산이 도모될 뿐만 아니라,악티늄-225의 직접 공급이 어려운 지역에서도 보다 광범위한 공급 체계 구축이 지원될 가능성이 있습니다.
지역별 분석
2025년, 북미는 알파 방사성 물질 시장 점유율의 50.09%를 차지했습니다. 이는 FDA 승인을 받은 Xofigo 플랫폼, 확립된 핵의학 센터, 집중된 임상 시험 활동에 힘입은 결과입니다. 미국은 임상적 유효성이 입증된 방사성 의약품에 대한 규제 승인 절차의 혜택을 받고 있는 반면, Orano Med사의 AlphaMedix는 2024년에 FDA로부터 획기적 치료제(Breakthrough Designation) 지정을 받았습니다. 캐나다는 Actineer 벤처 기업 참여를 통해 공급에 기여하고 있습니다. 멕시코는 핵의학 인프라가 비교적 제한적이어서 여전히 초기 단계에 머물러 있습니다. 미시간주, 인디애나주, 필라델피아, 위스콘신주에 액티늄-225 생산 업체가 존재한다는 점은 이 지역에 있으며, 중요한 공급망상의 우위입니다.
미국은 상업용 동위원소 공급의 주요 거점이며, IONETIX, 카디널 헬스, 테라파워 아이소토프스, SHINE 테크놀러지스가 생산 능력을 운영하거나 개발하고 있습니다. SHINE 테크놀러지스는 2026년 4월, 미국 에너지부로부터 의료용 동위원소 제조 인프라를 위해 2억 6,300만 달러의 조건부 자금 지원을 확약받았습니다. 유럽은 지역적으로 두 번째로 큰 비중을 차지하고 있으며, 독일과 프랑스가 핵의학 센터 및 방사성 의약품 생산을 통해 이 지역 활동의 대부분을 차지하고 있습니다. Eckert &Ziegler사는 2024년과 2025년에 Actinium Pharmaceuticals사, GlyTherix사, SK Biopharmaceuticals사와의 계약을 통해 공급망을 확대했습니다. 오라노 메드는 산업 규모의 납-212 전구체 생산 개발을 위해,ATEF 시설에 2억 5,000만 유로(2억 8,430만 달러)를 투자하고 있으며, 이 중 2,200만 유로(2,500만 달러)는 ‘프랑스 2030’ 계획에 따른 프랑스 정부의 지원금입니다. 중동 및 아프리카·남미는 치료 인프라와 동위원소 수입 물류가 미비하여 여전히 시장 기여도가 낮은 상황입니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 18.17%로 성장할 것으로 예측되며, 알파 방사성 물질 시장에서 가장 빠르게 성장하는 지역이 될 전망입니다. 일본은 알파선 치료의 연구 기반이 확립되어 있으며, 신규 방사성 의약품에 대한 신속 심사 제도가 마련되어 있습니다. 오사카 대학에서 실시된 Alpha-T1 임상시험에서는 방사성 요오드 저항성 분화형 갑상선암에 대한 [211At]NaAt의 평가가 이루어졌으며, 11명의 환자에서 내약성과 예비적 유효성이 보고되었습니다. 한국에서는 악티늄-225의 국내 생산이 계획되어 있으며, 이를 통해 공급 경로가 단축되고 개발자의 투여 비용이 절감될 것으로 전망됩니다. 중국의 ‘건강 중국 2030’ 구상에는 첨단 종양 치료법 및 표적형 방사성 핵종 치료에 대한 지원이 포함되어 있습니다. 정부 주도의 동위원소 현지 생산 노력을 통해 예측 기간 내에 수입 의존도를 낮추고, 국내 알파선 치료 생태계 구축이 촉진될 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the alpha emitters market size was valued at USD 275.95 million in 2025 and is estimated to grow from USD 322.54 million in 2026 to reach USD 698.98 million by 2031, at a CAGR of 16.73% during the forecast period (2026-2031).
This report is Segmented by Type of Radionuclide (Astatine-211, Radium-223, Actinium-225, and More), Application (Prostate Cancer, Bone Metastasis, Ovarian Cancer, Pancreatic Cancer, Endocrine Tumors, and Other Applications), End User (Hospitals, Academic Medical Centers, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Alpha Emitters Market Trends and Insights
Escalating Incidence Of Hard-To-Treat Solid Tumors Driving Demand
The Alpha emitters market is linked to the growing need for treatment options in difficult-to-treat solid tumors, particularly where patients no longer respond adequately to earlier systemic therapy. The World Health Organization projected 35 million new cancer cases in 2050, compared with 20 million in 2022, which increases the potential pool of patients with refractory and metastatic disease that may require additional treatment options. Bone-metastatic disease and resistant solid tumors are important because many patients have progressed after chemotherapy, androgen-pathway inhibitors, or other treatments that have already addressed the primary disease. Alpha radiation can produce double-strand DNA damage, which is relevant where tumors have adapted to repair damage from earlier treatment and have become less responsive to conventional approaches. Better first-line prostate cancer treatment can extend survival and leave more patients facing bone micrometastases later in care, which can broaden the clinical window for radium-223. Updated nuclear medicine protocols have encouraged consideration of radionuclide therapy earlier in metastatic castration-resistant prostate cancer management rather than only after every other systemic option has been exhausted.
Superior Tumor-Killing Efficiency Boosting Clinician Confidence
Alpha particles deposit 50 to 230 keV/µm of energy across a 40 to 90 µm path length and have a reported relative biological effectiveness of 3 to 7 compared with conventional radiation. This physical profile supports use in heterogeneous tumors because radiation is delivered over a limited range rather than across a wider area of surrounding tissue. The Alpha emitters market benefits when physicians can consider both controlled evidence and routine-practice experience, especially for agents that require specialized treatment planning. Final PEACE-3 results published in February 2026 showed that radium-223 plus enzalutamide reduced mortality risk by 24% versus enzalutamide alone in patients with metastatic castration-resistant prostate cancer and bone metastases. Median overall survival was 38.2 months with the combination and 32.6 months with enzalutamide alone, with a hazard ratio of 0.76 and p=0.0096, adding a defined clinical result to the treatment discussion. The short radiation path may limit dose to nearby healthy tissue, which can affect toxicity concerns, retreatment considerations, and physician confidence when weighing localized radiation options.
Limited Manufacturing Capacity Creating Supply Bottlenecks
The Alpha emitters market still faces a gap between isotope output and the requirements of expanding clinical programs, even though producers are investing in new capacity. Actinium-225 has a 9.9-day half-life, which leaves limited time for production, quality testing, shipping, and patient administration and makes each step operationally dependent on the last. A disruption at one qualified facility can therefore delay several studies and treatment schedules at the same time because there is limited opportunity to hold replacement inventory. The present supplier base for cGMP-grade actinium-225 remains narrow relative to the number of late-stage programs seeking supply, which creates concentration risk for developers and trial sites. Facility construction alone does not resolve the issue because radiopharmaceutical production requires validation and cGMP qualification before material can support commercial use at consistent quality. Supply pressure may therefore persist into 2027 even as newly announced capacity is built, particularly for programs that need dependable allocations rather than occasional production batches.
Other drivers and restraints analyzed in the detailed report include:
- Strategic Pharmaceutical Investments Accelerating Development
- Expanding Isotope Production Infrastructure Improving Availability
- Specialized Infrastructure Requirements Driving Provider Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Radium-223 held 61.77% of the Alpha emitters market share in 2025 because it remained the only commercially approved alpha emitter and had an established clinical position. Its position reflects use in metastatic castration-resistant prostate cancer with symptomatic bone metastases, where hospitals already had relevant treatment procedures. PEACE-3 and post-market evidence have added clinical information that can support earlier placement in treatment pathways for appropriate patients. Actinium-225 has attracted substantial developmental investment, with several programs in later-stage evaluation and a growing group of cGMP supply agreements intended to support development. Bismuth-212, bismuth-213, and other radionuclides such as terbium-149 remain mainly in academic, preclinical, or early Phase I work, with short half-lives and distribution needs limiting their immediate commercial role.
Lead-212 is projected to record a 29.57% CAGR from 2026 to 2031, making it the fastest-growing radionuclide category in the Alpha emitters market. Its 10.6-hour half-life supports labeling and clinical delivery, while its decay sequence through bismuth-212 provides sequential alpha and beta emissions intended to concentrate dose at the tumor site. AlphaMedix received FDA Breakthrough Designation in 2024 for gastroenteropancreatic neuroendocrine tumors, and Orano Med expanded its collaboration with Roche in December 2025. Bicycle Therapeutics announced an end-to-end lead-212 supply chain in December 2025 for its BRC platform, which uses peptide-targeting agents for EphA2 and MT1-MMP. The growth of lead-212 increases the importance of thorium-228 generator networks, diversifies supply risk beyond cyclotron or reactor capacity, and could support wider distribution where direct actinium-225 supply is difficult.
Complete Report Scope:
- By Type of Radionuclide
- Astatine-211
- Radium-223
- Actinium-225
- Lead-212
- Bismuth-212
- Other Radionuclides
- By Application
- Prostate Cancer
- Bone Metastasis
- Ovarian Cancer
- Pancreatic Cancer
- Endocrine Tumors
- Other Applications
- By End User
- Hospitals
- Academic Medical Centers
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 50.09% of the Alpha emitters market share in 2025, supported by the FDA-approved Xofigo platform, established nuclear medicine centers, and concentrated clinical trial activity. The United States benefits from regulatory pathways for radiopharmaceuticals with demonstrated clinical benefit, while Orano Med's AlphaMedix received FDA Breakthrough Designation in 2024. Canada contributes to supply through its partnership in the Actineer venture. Mexico remains at an earlier stage because nuclear medicine infrastructure is more limited. The presence of actinium-225 producers in Michigan, Indiana, Philadelphia, and Wisconsin gives the region an important supply-chain advantage.
The United States is a major center for commercial isotope supply, with IONETIX, Cardinal Health, TerraPower Isotopes, and SHINE Technologies operating or developing production capacity. SHINE Technologies received a USD 263 million conditional commitment from the US Department of Energy in April 2026 for medical isotope manufacturing infrastructure. Europe held the second-largest geographic position, with Germany and France accounting for much of regional activity through nuclear medicine centers and radiopharmaceutical production. Eckert & Ziegler expanded its supply network through agreements with Actinium Pharmaceuticals, GlyTherix, and SK Biopharmaceuticals during 2024 and 2025. Orano Med is investing EUR 250 million (USD 284.3 million) in its ATEF facility, with EUR 22 million (USD 25 million) of French government support under France 2030, to develop industrial-scale lead-212 precursor production. Middle East and Africa and South America remain smaller contributors because treatment infrastructure and isotope import logistics are less developed.
Asia-Pacific is forecast to grow at an 18.17% CAGR through 2031, making it the fastest-growing regional part of the Alpha emitters market size. Japan has an established alpha therapy research base and accelerated review pathways for novel radiopharmaceuticals. The Alpha-T1 trial at Osaka University evaluated [211At]NaAt in radioiodine-refractory differentiated thyroid cancer and reported tolerability and preliminary efficacy in 11 patients. South Korea's planned domestic actinium-225 production can shorten supply lines and reduce dose costs for developers. China's Healthy China 2030 initiative includes support for advanced oncology modalities and targeted radionuclide therapy. Government-backed isotope localization efforts can reduce import dependence and encourage a domestic alpha therapy ecosystem within the forecast period.
- Actinium Pharmaceutical
- Bayer
- BWXT Medical Ltd
- Cardinal Health
- Eckert & Ziegler
- IONETIX Corporation
- ITM Isotopen Technologien Mnchen SE
- NorthStar Medical Radioisotopes LLC
- Novartis
- NRG
- Nusano
- Orano Med SAS
- SDS Lifesciences Pvt. Ltd
- SHINE Technologies LLC
- State Atomic Energy Corporation (Rosatom)
- TerraPower, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Incidence of Hard-to-Treat Solid Tumors Driving Demand
- 4.2.2 Superior Tumor-Killing Efficiency Boosting Clinician Confidence
- 4.2.3 Strategic Pharmaceutical Investments Accelerating Development
- 4.2.4 Expanding Isotope Production Infrastructure Improving Availability
- 4.2.5 Evolving Regulatory and Reimbursement Frameworks
- 4.2.6 Shift of Big-Pharma Oncology Pipelines Toward Radionuclide-Drug Conjugates (RDCS)
- 4.3 Market Restraints
- 4.3.1 Limited Manufacturing Capacity Creating Supply Bottlenecks
- 4.3.2 Specialized Infrastructure Requirements Driving Provider Costs
- 4.3.3 Inconsistent Reimbursement Guidelines
- 4.3.4 Limited Long-term Safety Data & Low Physician Familiarity
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type of Radionuclide
- 5.1.1 Astatine-211
- 5.1.2 Radium-223
- 5.1.3 Actinium-225
- 5.1.4 Lead-212
- 5.1.5 Bismuth-212
- 5.1.6 Other Radionuclides
- 5.2 By Application
- 5.2.1 Prostate Cancer
- 5.2.2 Bone Metastasis
- 5.2.3 Ovarian Cancer
- 5.2.4 Pancreatic Cancer
- 5.2.5 Endocrine Tumors
- 5.2.6 Other Applications
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Academic Medical Centers
- 5.3.3 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Actinium Pharmaceuticals Inc.
- 6.3.2 Bayer AG
- 6.3.3 BWXT Medical Ltd
- 6.3.4 Cardinal Health Inc.
- 6.3.5 Eckert & Ziegler
- 6.3.6 IONETIX Corporation
- 6.3.7 ITM Isotopen Technologien Mnchen SE
- 6.3.8 NorthStar Medical Radioisotopes LLC
- 6.3.9 Novartis AG (Advanced Accelerator Applications)
- 6.3.10 NRG
- 6.3.11 Nusano
- 6.3.12 Orano Med SAS
- 6.3.13 SDS Lifesciences Pvt. Ltd
- 6.3.14 SHINE Technologies LLC
- 6.3.15 State Atomic Energy Corporation (Rosatom)
- 6.3.16 TerraPower, LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment