

|
시장보고서
상품코드
2121390
농업용 보조제 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Agricultural Adjuvants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
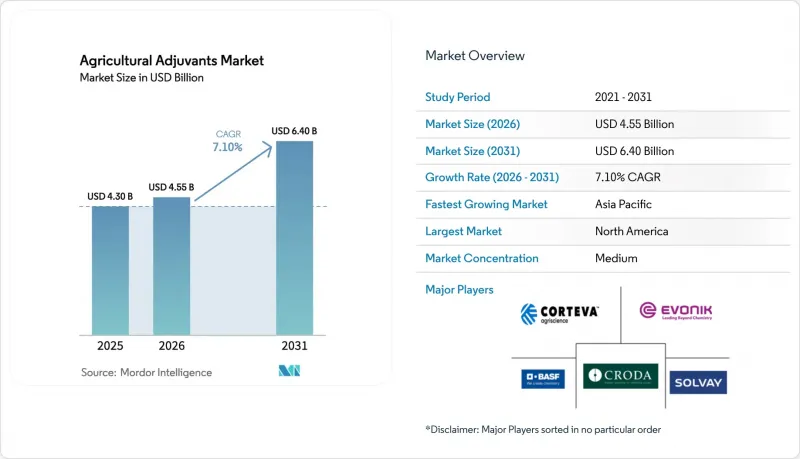
에 의하면, 농업용 보조제 시장 규모는 2025년에 43억 달러로 평가되었고, 2026년 45억 5,000만 달러에서 2031년까지 64억 달러로 확대되어 예측 기간(2026-2031년) CAGR은 7.1%를 기록할 전망입니다.
본 보고서는 유형별(활성화 보조제 및 범용 보조제), 용도별(제초제용 보조제, 살충제용 보조제 등), 작물별(곡물, 유지종자 및 콩류, 과일 및 채소, 기타 작물), 지역별(북미, 남미, 유럽,아시아태평양, 중동, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 농업용 첨가제 시장 동향 및 인사이트
증가하는 식량 수요와 감소하는 경작지
유엔의 예측에 따르면, 2050년까지 세계 인구는 97억 명에 달할 것이며, 추가 경작지에 대한 수요는 1억 6,500만 헥타르에 이를 것으로 전망됩니다. 1인당 경작 가능 면적이 감소하는 가운데, 각국 정부는 살포 보조제를 배합한 약제의 사용을 장려하는 수확량 증대 프로그램을 추진하고 있으며, 이를 통해 살포 횟수를 줄이고 투입 자재의 효율을 높이고 있습니다. 식량 수요와 이용 가능한 농지 간의 이러한 격차 확대로 인해 생산자들은 기존 경작 면적에서 생산성을 극대화할 수밖에 없게 되었으며, 작물 보호 제품에 대한 의존도가 높아지고 있습니다. 농업용 살포 보조제는 약제의 부착, 확산, 흡수를 개선함으로써 이러한 변화를 뒷받침하며, 농약 사용을 최적화하는 동시에 해충 방제 및 잡초 통제를 더욱 효과적으로 수행할 수 있게 합니다.
정밀 농업의 도입이 살포 정밀도를 향상
GPS 유도식 분무기, 가변 살포량 기술(VRT), 센서 기반 살포 시스템과 같은 정밀 농업 기술은 작물 보호 실천에 큰 영향을 미치고 있습니다. 이러한 시스템을 통해 살포량은 15%에서 25%까지 감소하지만, 이는 액적의 분포가 균일하게 유지되는 경우에 한합니다. 따라서 현재는 드리프트 억제 폴리머나 저발포성 계면활성제가 필수 첨가제가 되었습니다. 서유럽에서도 유사한 동향이 관찰됩니다. ‘팜-투-포크(Farm-to-Fork)’ 전략의 50% 감축 목표에 따라, 생산자들은 1리터당 효과를 더욱 높여야만 하는 상황에 놓여 있습니다. 중국에서는 드론을 이용한 살포량이 1헥타르당 5-15리터인 반면, 지상 살포기의 경우 100리터에 달하기 때문에 엽면 피복을 유지하기 위해서는 유기 실리콘계 슈퍼 스프레더가 필수적입니다. 이러한 추세로 인해 농업용 보조제 시장의 모든 하위 부문에서 수요가 가속화되고 있습니다.
혼합 성분에 대한 독성 기준 강화
규제 당국은 보조제에 사용되는 비활성 성분 및 공동 배합 성분에 대한 심사를 강화하고 있습니다. 유럽연합(EU)은 화학물질의 등록, 평가, 허가 및 제한(REACH) 체계를 통해, 미국 환경보호청(EPA)은 계면활성제 및 알킬페놀 에톡실레이트에 대해 더욱 엄격한 독성 기준을 도입했습니다. 2022년, 유럽연합(EU)의 ‘팜 투 포크(Farm to Fork)’ 전략은 2030년까지 농약 사용량을 50% 감축하는 것을 목표로 하고 있습니다. 그 결과, 회원국들은 코덱스 기준을 상회하는 엄격한 잔류 기준치를 시행하고 있습니다. 이러한 조치로 인해 규정 준수 비용이 증가하고 제형 재설계가 필요해지면서 연구개발비 증가로 이어지고 있습니다. 규정 준수 비용은 화학물질마다 고액이 될 가능성이 있으며, 이러한 부담으로 인해 소규모 제형 제조업체는 시장에서 배제되고, 농업용 보조제 시장 점유율은 수직 통합형 대기업으로 이동하고 있습니다. 저온 환경에서의 낮은 성능은 여전히 식물성 계면활성제의 과제로 남아 있으며, 이로 인해 이익률을 압박하는 제제 재설계 주기를 피할 수 없는 상황입니다.
부문 분석
2025년에는 계면활성제 계열 보조제가 가장 큰 부문이 되어 농업용 보조제 시장 점유율의 70.5%를 차지했습니다. 이는 대부분의 발아 후 제초제 라벨에서 계면활성제나 유류의 사용이 여전히 필수로 규정되어 있기 때문입니다. 현대 작물 보호 관행에 영향을 미치는 농업적, 경제적, 규제적 요인의 부양에 힘입어, 농업용 계면활성제계 보조제의 세계적 수요는 크게 증가하고 있습니다. 식량, 사료, 섬유에 대한 전 세계적 수요 증가에 대응하기 위해 농업 시스템이 작동하는 가운데, 농가는 제초제, 살균제, 살충제, 엽면 비료 등 작물 보호 제품의 효율성과 유효성을 점점 더 중요하게 여기고 있습니다.
유틸리티 계열 보조제는 가장 빠르게 성장하는 부문으로, 2031년까지 연평균 성장률(CAGR) 8.4%를 나타낼 것으로 예측됩니다. 이는 농가가 점점 더 엄격해지는 노즐 및 pH 사양을 충족할 수 있도록 지원하는 드리프트 억제 폴리머와 수질 조절제에 의해 주도되고 있습니다. 드론 운용 프로토콜 및 경수 지역에서의 이용 사례가 증가함에 따라, 유틸리티 계열 제품을 포함한 농업용 보조제 시장 규모는 꾸준히 확대될 것으로 전망됩니다. 정밀 농업의 보급으로 인해 범용 첨가제는 농업의 핵심 기술로 자리 잡아가고 있습니다. 드리프트 억제제는 ISO 22866의 액적 기준을 충족하고, 수질 조정제는 글리포세이트의 효과를 40% 저하시킬 가능성이 있는 광물 간의 항균 작용을 중화하며, 소포제는 고압 펌프의 넘침을 방지합니다. 탱크 혼합물에 첨가되는 성분이 늘어날수록 호환성 문제로 인한 위험이 높아지기 때문에 유화액을 안정화시키는 완충제나 폴리머에 대한 수요가 증가하고 있습니다.
지역별 분석
북미는 최대 시장으로, 2025년에는 농업용 보조제 시장 점유율의 35.4%를 차지했습니다. 이는 고도로 기계화된 농장과 광범위한 유통망 덕분에 보조제 패키지가 이미 일상적인 작물 보호 프로그램에 통합되어 있기 때문입니다. 미국의 포화 상태로 인해 추가 경작 면적이 정체되어 있어, 성장률은 전 세계 평균보다 약간 낮을 것으로 예측됩니다. 캐나다에서는 여전히 계면활성제로 최적화된 글리포세이트 살포에 의존하는 카놀라 및 밀 재배 프로그램이 시장에 탄력성을 부여하고 있습니다. 한편, 점적 관개를 통한 채소 재배를 확대하고 있는 멕시코는 북미 시장 전체에서 더 빠른 성장을 이끌고 있습니다.
아시아태평양은 가장 성장세가 두드러지는 지역으로, 중국과 인도가 살포 장비의 현대화를 추진하고 수확량 목표를 상향 조정함에 따라 2031년까지 연평균 성장률(CAGR) 8.1%로 성장할 전망입니다. 중국의 무인 항공기(UAV) 및 스마트 농업 기계에 대한 정책 지원으로 인해, 첨가제 수요는 ‘슈퍼 스프레더’와 ‘드리프트 저감제’에 집중되고 있습니다. 인도의 ‘디지털 농업 미션’은 정밀 살포 장비 구입 비용의 절반을 보조하고 있어, 면화, 유채, 콩류용 활성제 판매를 촉진하고 있습니다. 일본과 호주에서는 고령화가 진행되고 있는 농촌 지역의 드론 도입과 드리프트 제어에 크게 의존하는 면화용 살충제 프로그램이 이 지역의 성장을 보완하고 있습니다.
유럽과 남미에서는 꾸준한 정책 지원과 시장 성장 억제요인이 상쇄되어 완만한 성장이 나타나고 있습니다. 유럽에서는 엄격한 환경 규제가 성장의 주요 원동력이며, 이로 인해 구매 경향이 바이오 혼합 제품으로 이동하고 있으나, 총 판매량 증가로 이어지지는 않고 있습니다. 남미에서는 브라질과 아르헨티나의 농가들이 대두와 옥수수 재배를 확대함에 따라 뚜렷한 연평균 성장률(CAGR)이 나타나고 있습니다. 그러나 환율 변동과 투입 자재 비용 상승이 고품질 보조제 도입을 저해하고 있습니다. 아프리카는 다른 지역에 비해 뒤처져 있지만, 상업 농업의 발전과 드리프트 제어 및 수질 조정을 중시하는 기부금 지원 교육 프로그램의 뒷받침으로 한 자릿수대의 꾸준한 성장을 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the agricultural adjuvants market size was valued at USD 4.30 billion in 2025 and is estimated to grow from USD 4.55 billion in 2026 to USD 6.40 billion by 2031, at a CAGR of 7.1% during the forecast period (2026-2031).
This report is Segmented by Type (Activator Adjuvants and Utility Adjuvants), by Application (Herbicide Adjuvants, Insecticide Adjuvants, and More), by Crop Type (Cereals and Grains, Oilseeds and Pulses, Fruits and Vegetables, and Other Crops) and by Geography (North America, South America, Europe, Asia-Pacific, Middle East, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Agricultural Adjuvants Market Trends and Insights
Growing Food Demand Versus Declining Arable Land
According to United Nations projections, the world's population is projected to reach 9.7 billion by 2050, and demand for additional arable land is projected to reach 165 million hectares. As cultivable land per capita declines, governments are promoting yield intensification programs that encourage the use of adjuvant-enhanced sprays to reduce repeat applications and improve input efficiency. This widening gap between food demand and available farmland compels growers to maximize productivity on existing acreage, increasing dependence on crop protection products. Agricultural adjuvants support this shift by improving spray deposition, spreading, and uptake, enabling more effective pest and weed control while optimizing agrochemical use.
Precision-Farming Adoption Boosting Spray Accuracy
Precision agriculture technologies, such as GPS-guided sprayers, variable rate technology (VRT), and sensor-based application systems, are significantly influencing crop protection practices. Such systems cut spray volumes by 15% to 25%, but only if droplets remain uniform, drift-control polymers and low-foam surfactants are now required additives. Similar trends hold in Western Europe, where the Farm-to-Fork strategy's 50% reduction target forces growers to squeeze more efficacy from each liter. China's drone fleet delivers 5-15 liters per hectare compared with 100 liters from ground rigs, making organosilicone superspreaders indispensable to maintain leaf coverage. These dynamics accelerate demand across every subsegment of the agricultural adjuvants market.
Tightening Toxicology Thresholds for Co-Formulants
Regulatory agencies are intensifying their scrutiny of inert ingredients and co-formulants used in adjuvants. The European Union, through the Registration, Evaluation, Authorisation, and Restriction of Chemicals (REACH) framework, and the Environmental Protection Agency (EPA) have implemented stricter toxicity benchmarks for surfactants and alkylphenol ethoxylates. In 2022, the European Union's Farm to Fork strategy targets a 50% reduction in pesticide use by 2030. As a result, member states are enforcing stringent maximum residue limits that surpass Codex standards. These measures have increased compliance costs and necessitated reformulations, leading to higher R&D expenditures. Compliance costs can reach high per-chemistry level, a burden that sidelines small formulators and shifts share toward vertically integrated majors in the agricultural adjuvants market. Cold-weather performance gaps still plague vegetable-oil surfactants, forcing reformulation cycles that sap margins.
Other drivers and restraints analyzed in the detailed report include:
- Shift to Herbicide-Tolerant Seeds Elevating Adjuvant Need
- Surge in Bio-Based Surfactant Innovation Lowering Toxicity
- Compatibility Gaps with Microbial Biocontrol Agents
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Activator adjuvants were the largest segment, led with 70.5% of the agricultural adjuvants market share in 2025, because surfactants and oils remain mandatory on most post-emergence herbicide labels. The global demand for agricultural activator adjuvants is rising significantly, driven by agronomic, economic, and regulatory factors influencing modern crop protection practices. As agricultural systems work to meet the growing global demand for food, feed, and fiber, farmers are increasingly prioritizing the efficiency and effectiveness of crop protection products, including herbicides, fungicides, insecticides, and foliar nutrients.
Utility adjuvants are fastest fastest-growing segment, forecast to post an 8.4% CAGR through 2031, fueled by drift-control polymers and water conditioners that help growers satisfy ever-tighter nozzle and pH specifications. The agricultural adjuvants market size for utility products is forecast to expand steadily as drone protocols and hard-water fields multiply use cases. Precision rules are embedding utilities into core agronomy. Drift-control agents meet ISO 22866 droplet standards, water conditioners neutralize mineral antagonism that can cut glyphosate performance by 40%, and antifoams protect high-pressure pumps from overflow. Each added tank-mix input increases the risk of incompatibility, which drives demand for buffers and polymers that stabilize emulsions.
Complete Report Scope:
- By Type
- Activator Adjuvants
- Surfactants
- Oil Adjuvants
- Utility Adjuvants
- Drift Control Agents
- Water Conditioners
- Antifoaming Agents
- Acidifiers and Buffers
- Activator Adjuvants
- By Application
- Herbicide Adjuvants
- Insecticide Adjuvants
- Fungicide Adjuvants
- Other Applications
- By Crop Type
- Cereals and Grains
- Oilseeds and Pulses
- Fruits and Vegetables
- Other Crops
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America was the largest region, holding 35.4% of the agricultural adjuvants market share in 2025, as its highly mechanized farms and extensive dealer networks already integrate adjuvant packages into routine crop-protection programs. Growth is projected to increase slightly behind the worldwide pace, because saturation in the United States caps incremental acreage. Canada adds resilience with canola and wheat programs that still depend on surfactant-optimized glyphosate passes, while Mexico, expanding drip-irrigated vegetables, brings faster growth to the continental mix.
Asia-Pacific is the fastest-growing region, on track to expand at an 8.1% CAGR to 2031, as China and India modernize their spraying equipment and push yield targets higher. China's policy backing for Unmanned Aerial Vehicles (UAVs) and smart machinery funnels adjuvant demand into superspreaders and drift-reducers. India's Digital Agriculture Mission funds half of the qualifying costs for precision-spray equipment, stoking sales of activators for cotton, mustard, and pulses. Japan and Australia round out regional growth with drone deployments in aging rural districts and cotton insecticide programs that rely heavily on drift control.
Europe and South America demonstrate moderate performance, balancing steady policy support with market limitations. In Europe, growth is primarily driven by stringent environmental regulations, which are shifting purchasing preferences toward bio-based blends rather than increasing overall volumes. In South America, a notable CAGR is observed as Brazilian and Argentine farmers expand soybean and corn cultivation. However, fluctuating currency values and input costs hinder the adoption of premium adjuvants. Africa lags behind other regions but maintains consistent single-digit growth, supported by the development of commercial farming and donor-funded training programs emphasizing drift control and water conditioning.
- BASF SE
- Corteva Agriscience
- Evonik Industries
- Solvay SA
- Croda International
- Nufarm Ltd
- Helena Agri-Enterprises
- AkzoNobel NV
- Brandt Consolidated
- Wilbur-Ellis Company
- Adjuvant Plus Inc.
- Huntsman Corporation
- Clariant AG
- Momentive Performance Materials
- Interagro Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing food demand versus declining arable land
- 4.2.2 Precision-farming adoption boosting spray accuracy
- 4.2.3 Shift to herbicide-tolerant seeds elevates adjuvant need
- 4.2.4 Surge in bio-based surfactant innovation, lowering toxicity
- 4.2.5 Drone-enabled ultra-low-volume spraying necessitating ultra-spreaders
- 4.2.6 Carbon-credit-linked dose-reduction incentives
- 4.3 Market Restraints
- 4.3.1 Tightening toxicology thresholds for co-formulants
- 4.3.2 Volatility in petrochemical feedstock pricing
- 4.3.3 Compatibility gaps with microbial biocontrol agents
- 4.3.4 AI-guided spray systems reducing broad-spectrum adjuvant use
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Activator Adjuvants
- 5.1.1.1 Surfactants
- 5.1.1.2 Oil Adjuvants
- 5.1.2 Utility Adjuvants
- 5.1.2.1 Drift Control Agents
- 5.1.2.2 Water Conditioners
- 5.1.2.3 Antifoaming Agents
- 5.1.2.4 Acidifiers and Buffers
- 5.1.1 Activator Adjuvants
- 5.2 By Application
- 5.2.1 Herbicide Adjuvants
- 5.2.2 Insecticide Adjuvants
- 5.2.3 Fungicide Adjuvants
- 5.2.4 Other Applications
- 5.3 By Crop Type
- 5.3.1 Cereals and Grains
- 5.3.2 Oilseeds and Pulses
- 5.3.3 Fruits and Vegetables
- 5.3.4 Other Crops
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 France
- 5.4.3.3 United Kingdom
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 Australia
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 BASF SE
- 6.4.2 Corteva Agriscience
- 6.4.3 Evonik Industries
- 6.4.4 Solvay SA
- 6.4.5 Croda International
- 6.4.6 Nufarm Ltd
- 6.4.7 Helena Agri-Enterprises
- 6.4.8 AkzoNobel NV
- 6.4.9 Brandt Consolidated
- 6.4.10 Wilbur-Ellis Company
- 6.4.11 Adjuvant Plus Inc.
- 6.4.12 Huntsman Corporation
- 6.4.13 Clariant AG
- 6.4.14 Momentive Performance Materials
- 6.4.15 Interagro Ltd


