

|
시장보고서
상품코드
2121425
미국의 호흡기 기기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Respiratory Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
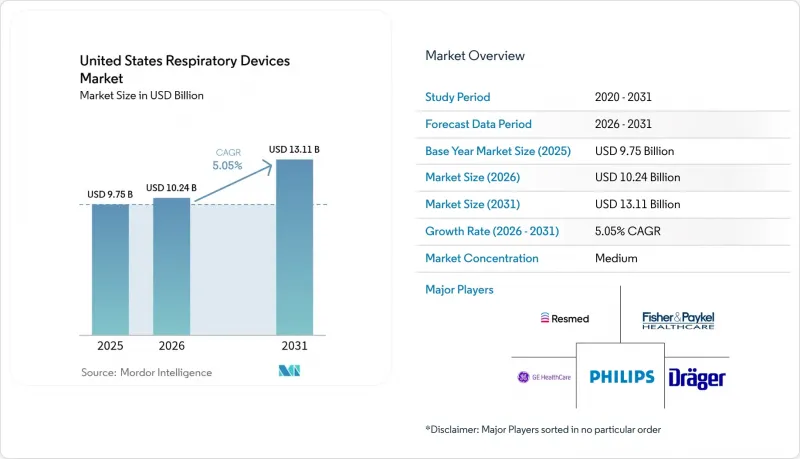
에 의하면, 미국의 호흡기 기기 시장 규모는 2025년에 97억 5,000만 달러로 평가되었고, 2026년 102억 4,000만 달러에서 2031년까지 131억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.05%를 나타낼 전망입니다.
본 보고서는 제품 유형별(진단·모니터링 기기, 치료용 기기, 일회용 제품), 적응증별(만성 폐쇄성 폐질환(COPD), 천식, 수면 무호흡증, 감염증, 기타 호흡기 질환), 최종 사용자별(병원 및 클리닉, 재택 간호 환경 등), 지역별(북동부, 중서부,남동부, 서부, 남서부)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국의 호흡기 기기 시장 동향 및 인사이트
미국 성인의 COPD 및 천식 유병률 증가
COPD는 진단을 받은 성인 1,250만 명에게, 천식은 2,680만 명의 미국인에게 영향을 미치고 있으며, 그 유병률은 남동부 및 중서부의 일부 카운티에서 최고치를 기록하고 있습니다. 주별 COPD 유병률은 하와이주의 3%에서 웨스트버지니아주의 12%까지 폭이 넓으며, 이는 환경 노출 및 의료 접근성에서의 격차를 반영합니다. COPD로 인한 사망률은 성인 10만 명당 41-171명으로, 치료 부담이 여전히 크다는 것을 보여줍니다. 이러한 역학적 추세로 인해, 네뷸라이저, 산소 농축기, 흡기 유량 측정치를 통해 악화를 예측할 수 있는 디지털 흡입기에 대한 수요가 증가하고 있습니다. 천식으로 인한 연간 직접 및 간접 비용은 800억 달러에 육박하며, 비용 대비 효과가 높은 재택용 호흡기 솔루션에 대한 보험사의 관심이 높아지고 있습니다.
고령화와 재택 간호로의 전환
2060년까지 미국인의 4분의 1 가까이가 65세 이상이 될 것으로 예상되며, 이에 따라 재택 치료 및 원격 환자 모니터링으로의 구조적 전환이 진행되고 있습니다. 메디케어 수급자 중 COPD 관련 입원 건수는 최근 24만 건 이상에 달하며, 휴대용 산소 농축기 및 가정용 인공호흡기에 대한 필요성이 더욱 높아지고 있습니다. 원격 환자 모니터링 이용자는 이미 약 5,000만 명에 달하며, 가치 기반 의료 인센티브에 맞추어 보상 제도가 조정됨에 따라 향후 10년 말까지 그 수가 두 배로 늘어날 것으로 예측됩니다. ‘환자 주도 그룹 분류 모델(PDGM)’은 운영상의 복잡성을 가중시키지만, 연결형 호흡기 플랫폼을 활용하여 측정 가능한 치료 성과 개선을 입증한 의료 제공업체에게는 보상이 주어집니다. 장기 인공호흡 관리가 필요한 사례는 지난 20년 동안 2배 이상 증가했으며, 급성기 이후 시설의 수용 능력이 한계에 달하면서 재택용 인공호흡기에 대한 투자가 촉진되고 있습니다.
높은 초기 비용과 병원의 자본 예산 주기
미국의 많은 병원은 주요 장비 구매 예산을 회계 연도당 한 번만 편성하고 있어, 이로 인해 교체 결정이 12-18개월 뒤로 미뤄지고, 첨단 인공호흡기나 영상진단용 초음파 장치의 도입이 지연되고 있습니다. 2025년 의사 보수 일정에 따른 2.93%의 보수 삭감은 특히 유동 자금이 부족한 지방 의료기관에서 영업이익률을 압박하고 있습니다. 가치 기반 보상 제도에서는 설비 투자 신청 시 명확한 임상 결과 증거가 요구되므로, 의료기기 제조업체가 실제 임상 데이터를 제공해야 하는 장벽이 높아지고 있습니다. COPD로 인한 연간 경제적 부담은 500억 달러에 육박하지만, 첨단 진단 기기는 투자 회수 기간이 길기 때문에 특히 환자 수가 적은 의료 기관에서는 도입이 지연될 가능성이 있습니다. 제조업체들은 고액의 초기 비용 부담을 완화하기 위해 리스나 종량제 구독 모델을 제공하고 있지만, 대규모 의료 시스템 이외의 도입 현황은 여전히 제각각입니다.
부문 분석
2025년 미국 호흡기 기기 시장에서 치료용 기기는 46.10%의 점유율을 차지했습니다. 이는 만성 및 급성 증상 모두에 대응하는 양압 호흡 요법(PAP) 시스템과 가정용 인공호흡기가 주도한 결과입니다. 이미 도입된 기기는 높은 수익률을 보이는 소모품에 대한 수요를 창출하고 있으며, AI를 활용한 복약 순응도 알고리즘이 치료 효과를 높이고 있습니다. 진단·모니터링 기기는 FDA 승인을 받은 가정용 폐기능 측정기 및 AI 청진 소프트웨어 덕분에 검사가 진료소에서 가정으로 이동함에 따라, 2031년까지 연평균 성장률(CAGR) 6.42%를 기록하며 여전히 가장 빠르게 성장하는 카테고리입니다. 마스크, 필터, 호흡 회로는 정기적인 교체가 필요하기 때문에 일회용 제품의 도입이 꾸준히 진행되고 있으며, 지속적인 수익이 확보되고 있습니다.
성장의 중요한 전환점이 되고 있는 것은 COPD 치료에 뛰어난 약물 침착 효과를 가져다주는 진동 메쉬식 네뷸라이저로, 이를 통해 주요 보험사의 보험 적용 목록에 추가되는 추세가 진행되고 있습니다. 휴대용 산소 농축기에는 클라우드 연결 기능이 통합되어 있어, 임상의가 원격으로 유량을 조절할 수 있으므로 재택 간호 동향에도 부합합니다. 호흡 수와 수면 중 움직임을 추적하는 진단용 스마트 패치는 수면 무호흡증의 진단 기간을 단축합니다. 이러한 요인들이 결합되어 미국 호흡기 기기 시장 규모에 부가가치를 더하는 한편, 데이터 기반의 사용자 경험을 둘러싼 경쟁을 심화시키고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the United States respiratory devices market size was valued at USD 9.75 billion in 2025 and estimated to grow from USD 10.24 billion in 2026 to reach USD 13.11 billion by 2031, at a CAGR of 5.05% during the forecast period (2026-2031).
This report is Segmented by Product Type (Diagnostic & Monitoring Devices, Therapeutic Devices, Disposables), Indication (COPD, Asthma, Sleep Apnea, Infectious Diseases, Other Respiratory Disorders), End User (Hospitals & Clinics, Home-Care Settings, and More), and Geography (Northeast, Midwest, Southeast, West, Southwest). The Market Forecasts are Provided in Terms of Value (USD).
United States Respiratory Devices Market Trends and Insights
Rising COPD & Asthma Prevalence Among U.S. Adults
COPD affects 12.5 million diagnosed adults and asthma affects 26.8 million Americans, with prevalence peaking in southeastern and midwestern counties. State-level COPD rates vary from 3% in Hawaii to 12% in West Virginia, mirroring disparities in environmental exposures and healthcare access. COPD mortality spans 41-171 deaths per 100,000 adults, underscoring the ongoing therapeutic burden. These epidemiologic patterns fuel demand for nebulizers, oxygen concentrators, and digital inhalers capable of predicting exacerbations by monitoring inspiratory flow metrics. Annual direct and indirect asthma costs near USD 80 billion, intensifying payer interest in cost-effective home-based respiratory solutions.
Aging Demographics and Home-care Shift
Nearly one quarter of Americans will be 65 years or older by 2060, prompting a structural shift toward in-home therapy and remote patient monitoring. Medicare beneficiaries recorded over 240k COPD-related hospitalizations in recent times, amplifying the need for portable oxygen concentrators and home ventilators. Remote patient monitoring users already number about 50 million and are expected to double by the end of the decade as reimbursement aligns with value-based care incentives. The Patient-Driven Groupings Model increases operational complexity but rewards providers that demonstrate measurable outcome improvements using connected respiratory platforms. Long-term mechanical ventilation cases more than doubled over two decades, tightening capacity in post-acute facilities and driving investment in home-compatible ventilators.
High Up-front Cost & Hospital Capital Budget Cycles
Most U.S. hospitals allocate major equipment purchases once per fiscal year, extending replacement decisions 12-18 months and deferring acquisition of advanced ventilators and imaging-grade ultrasound devices. A 2.93% payment cut in the 2025 Physician Fee Schedule compresses operating margins, especially in rural facilities with thin cash reserves. Value-based reimbursement requires clear clinical-outcome evidence for capital requests, raising the bar for device makers to supply real-world data. Although COPD's annual economic toll nears USD 50 billion, the longer payback period for sophisticated diagnostics can slow adoption, particularly where patient volumes are modest. Manufacturers offer leasing and per-use subscription models to mitigate sticker shock, but uptake remains mixed outside large health systems.
Other drivers and restraints analyzed in the detailed report include:
- CMS Reimbursement Expansion for Home Oxygen Therapy & NIV
- Uptake of Smart, Connected Respiratory Devices via Tele-health
- Stringent FDA Approval Timelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Therapeutic devices commanded 46.10% of the 2025 United States respiratory devices market, anchored by positive airway pressure (PAP) systems and home ventilators that address both chronic and acute conditions. The installed base generates high-margin consumables demand, while AI-driven adherence algorithms elevate therapeutic efficacy. Diagnostic & monitoring devices remain the fastest-growing category at a 6.42% CAGR through 2031 as FDA-cleared home-use spirometers and AI auscultation software migrate testing from clinics to living rooms. Disposables retain steady uptake because masks, filters, and breathing circuits require periodic replacement, ensuring recurring revenue.
A key growth inflection stems from vibrating mesh nebulizers that deliver superior deposition in COPD therapy, prompting formulary inclusion by major payers. Portable oxygen concentrators integrate cloud connectivity, allowing clinicians to titrate flow remotely and aligning with home-care trends. Diagnostic smart patches that track respiratory rate and sleep motion shorten sleep-apnea diagnosis cycles. Combined, these factors add incremental value to the United States respiratory devices market size while intensifying competition around data-driven user experiences.
Complete Report Scope:
- By Product Type
- Diagnostic & Monitoring Devices
- Spirometers
- Sleep Test Devices
- Peak Flow Meters
- Pulse Oximeters
- Capnographs
- Other Diagnostic & Monitoring Devices
- Therapeutic Devices
- CPAP Devices
- BiPAP Devices
- Humidifiers
- Nebulizers
- Oxygen Concentrators
- Ventilators (Invasive, Non-invasive)
- Inhalers (MDI, DPI, Soft-Mist)
- Other Therapeutic Devices
- Disposables
- Masks (CPAP, Oxygen, Nebulizer)
- Breathing Circuits
- Filters & Cannulas
- Other Disposables
- Diagnostic & Monitoring Devices
- By Indication
- COPD
- Asthma
- Sleep Apnea
- Infectious Diseases
- Other Respiratory Disorders
- By End User
- Hospitals & Clinics
- Home-care Settings
- Ambulatory Surgical Centers
- Emergency & Trauma Centers
- Long-Term Care Facilities
- By Region
- Northeast
- Midwest
- Southeast
- West
- Southwest
List of Companies Covered in this Report:
- Koninklijke Philips
- Resmed
- Fisher & Paykel Healthcare
- Medtronic
- GE Healthcare
- Dragerwerk AG
- Getinge
- Baxter
- Vyaire Medical
- Hamilton Medical
- Beijing Aeonmed Co. Ltd.
- Mindray
- React Health
- Medical Depot, Inc.
- Asahi Kasei
- AirLife
- Flexicare (Group) Limited (Allied Medical LLC)
- Teleflex
- OMRON Healthcare, Inc
- ICU Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising COPD & Asthma Prevalence Among U.S. Adults
- 4.2.2 Aging Demographics and Home-care Shift
- 4.2.3 CMS Reimbursement Expansion for Home Oxygen Therapy & NIV
- 4.2.4 Uptake of Smart, Connected Respiratory Devices via Tele-health
- 4.2.5 Growth of Ambulatory Surgical Centers Driving Portable Ventilation
- 4.2.6 Wild-fire Smoke Episodes Elevating Home Airway-Care Demand
- 4.3 Market Restraints
- 4.3.1 High Up-front Cost & Hospital Capital Budget Cycles
- 4.3.2 Stringent FDA Approval Timelines
- 4.3.3 Recalls & Safety Concerns Undermining Brand Trust
- 4.3.4 Limited Awareness of Early Diagnosis
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Diagnostic & Monitoring Devices
- 5.1.1.1 Spirometers
- 5.1.1.2 Sleep Test Devices
- 5.1.1.3 Peak Flow Meters
- 5.1.1.4 Pulse Oximeters
- 5.1.1.5 Capnographs
- 5.1.1.6 Other Diagnostic & Monitoring Devices
- 5.1.2 Therapeutic Devices
- 5.1.2.1 CPAP Devices
- 5.1.2.2 BiPAP Devices
- 5.1.2.3 Humidifiers
- 5.1.2.4 Nebulizers
- 5.1.2.5 Oxygen Concentrators
- 5.1.2.6 Ventilators (Invasive, Non-invasive)
- 5.1.2.7 Inhalers (MDI, DPI, Soft-Mist)
- 5.1.2.8 Other Therapeutic Devices
- 5.1.3 Disposables
- 5.1.3.1 Masks (CPAP, Oxygen, Nebulizer)
- 5.1.3.2 Breathing Circuits
- 5.1.3.3 Filters & Cannulas
- 5.1.3.4 Other Disposables
- 5.1.1 Diagnostic & Monitoring Devices
- 5.2 By Indication
- 5.2.1 COPD
- 5.2.2 Asthma
- 5.2.3 Sleep Apnea
- 5.2.4 Infectious Diseases
- 5.2.5 Other Respiratory Disorders
- 5.3 By End User
- 5.3.1 Hospitals & Clinics
- 5.3.2 Home-care Settings
- 5.3.3 Ambulatory Surgical Centers
- 5.3.4 Emergency & Trauma Centers
- 5.3.5 Long-Term Care Facilities
- 5.4 By Region
- 5.4.1 Northeast
- 5.4.2 Midwest
- 5.4.3 Southeast
- 5.4.4 West
- 5.4.5 Southwest
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Koninklijke Philips N.V.
- 6.3.2 ResMed
- 6.3.3 Fisher & Paykel Healthcare Ltd
- 6.3.4 Medtronic plc
- 6.3.5 GE HealthCare
- 6.3.6 Dragerwerk AG
- 6.3.7 Getinge
- 6.3.8 Baxter
- 6.3.9 VYAIRE
- 6.3.10 Hamilton Medical
- 6.3.11 Beijing Aeonmed Co. Ltd.
- 6.3.12 Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- 6.3.13 React Health
- 6.3.14 Medical Depot, Inc.
- 6.3.15 Asahi Kasei Corporation (ZOLL Medical Corporation)
- 6.3.16 AirLife
- 6.3.17 Flexicare (Group) Limited (Allied Medical LLC)
- 6.3.18 Teleflex Incorporated
- 6.3.19 OMRON Healthcare, Inc
- 6.3.20 ICU Medical, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


