|
시장보고서
상품코드
2121431
마이코플라스마 검사 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Mycoplasma Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
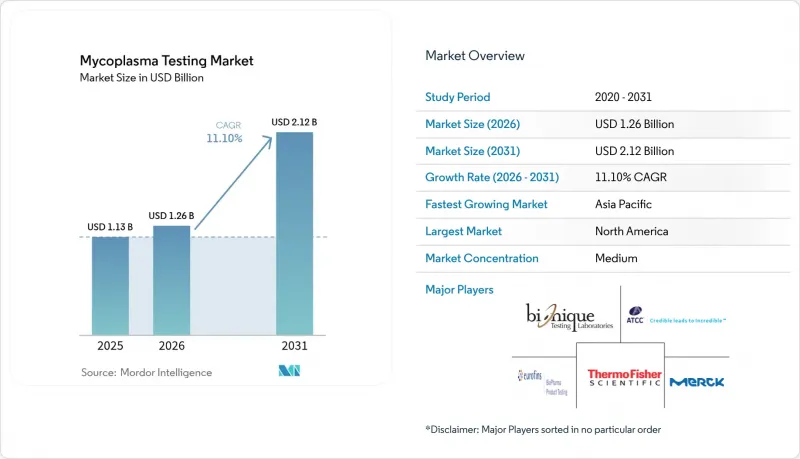
에 의하면, 2026년 마이코플라스마 검사 시장 규모는 12억 6,000만 달러로 추정되며, 2025년 11억 3,000만 달러에서 2031년에는 21억 2,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR)은 11.10%를 기록할 전망입니다.
본 보고서에서는 업계를 제품별(장비, 키트 및 시약, 서비스), 기술별(기존 PCR, QPCR 등),용도별(세포주 품질 관리 등), 최종 사용자별(바이오의약품·바이오기술 기업 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 마이코플라즈마 검사 시장 동향 및 인사이트
바이오의약품 및 세포 및 유전자 치료 제조 시설의 확대
자가 및 동종 요법 플랜트의 생산 능력 확대에 따라, 100% 배치 검사가 필요한 검체량이 수 배로 증가했습니다. 세포 배양에서 오염 발생률은 15%에서 35% 사이이며, FDA 지침에 따라 현재 풀링 처리 후 및 세척 전 마이코플라즈마 검사가 의무화되어 있어 샘플링 빈도가 증가하고 있습니다. 연속 관류형 바이오리액터의 도입으로 실시간 모니터링의 필요성이 높아지고 있으며, 인적 개입을 최소화하면서 높은 처리 능력을 갖춘 자동 분석 장치에 대한 수요가 확대되고 있습니다. 신흥 시장에서 시설을 가동하려면 적합성 시험을 완료해야 하므로, 이에 따라 제3자 검사 서비스에 대한 새로운 수요가 발생하고 있습니다. 이러한 동향들이 합쳐져 예측 연평균 성장률(CAGR)에 2.8%를 더하고 있습니다.
규제 요건에 따라 생물학적 제제에 대한 마이코플라즈마 방출 시험이 의무화되어 있습니다.
FDA의 ‘실험실 개발 검사(LDT) 규정’ 및 EMA의 ‘첨단 치료 의약품(ATMP)에 관한 지침’에서는 마스터 셀 뱅크부터 완제품에 이르기까지 검증된 분석법이 요구됩니다. 유럽의약품청(EMA)의 첨단 치료 의약품(ATMP)에 관한 지침에서는 마스터 셀 뱅크에서 최종 제품 출하에 이르기까지 전체 제조 공정 전반에 걸쳐 종합적인 마이코플라스마 검사가 의무화되어 있습니다. 이러한 규제 변경으로 인해 검증된 방법을 통해 마이코플라스마가 존재하지 않음을 입증해야만 제품을 출시할 수 있게 됨에 따라, 검사 서비스에 대한 불가피한 수요가 발생하고 있습니다. 단계적인 LDT(실험실 개발 검사) 규제가 시행됨에 따라, 규정 준수 관련 지출은 2027년까지 가속화될 전망입니다. 4년에 걸친 새로운 LDT 규제의 단계적 시행에 따라, 검사 기관이 규정 준수를 유지하기 위해 검사 역량을 향상시킬 것으로 예상되어 예측 가능한 수요 증가가 전망됩니다.
자동 검출 시스템 도입에 따른 고액의 설비 투자
엔트리 레벨 자동 분석기의 가격은 10만-50만 달러이며, 연간 서비스 계약료는 5만 달러를 초과합니다. 소규모 CTL이나 대학 부속 검사실은 이러한 지출을 정당화하기 어려워 수동 배양법에 대한 의존이 장기화되고 있습니다. FDA의 LDT 규정 준수 대응에는 검증 비용이 추가되어 자본 예산에 부담이 되기 때문에 단기적인 도입이 억제되고 있습니다. 소규모 수탁 검사 기관은 검체 수가 제한적이고 검사 요건도 다양하기 때문에 자동화에 대한 투자를 정당화하는 데 특히 큰 과제에 직면해 있습니다. 규제 준수를 위한 자동화 시스템의 검증은 복잡하며, 막대한 시간과 비용 부담이 따릅니다. 검증 시험에는 일반적으로 6-12개월이 소요되며, 전문적인 지식도 필요합니다.
부문 분석
2025년, 키트 및 시약은 45.72%의 점유율을 유지하며, 마이코플라스마 검사 시장에서 소모품으로서의 성격을 부각시키고 있습니다. 서비스 부문은 바이오 제조 기업들이 방법 검증 및 일상적인 스크리닝을 인증 검사 기관에 위탁하는 경향이 강해짐에 따라 연평균 성장률(CAGR) 14.15%로 성장할 전망입니다. 엄격한 규제 장벽과 분석 방식의 진화로 인해 기업들은 자체 체계를 구축하기보다는 전문가의 역량을 구매하는 추세입니다. 유로핀즈가 전 세계 45곳 이상에 구축한 거점 네트워크는 규모 확대가 가져다주는 비용 효율성이 개별 기업에서는 재현할 수 없음을 보여줍니다.
자동화 대응 기기는 구매자가 이를 장기 시약 계약과 연계하는 경우가 많기 때문에 꾸준하기는 하지만 성장 속도는 완만합니다. BIOFIRE 플랫폼과 Rapid Micro Biosystems사의 바이알 리더는 속도와 약전 준수를 양립시키고 있다는 점에서 매력적입니다. 서비스가 성장함에 따라 키트 공급업체들은 공급 수익을 확보하기 위한 시약 대여 모델 하에서 제3자 검사 기관과 제휴하고 있습니다. 이러한 시너지 효과로 인해 구매자와 공급자 간의 상호 의존 관계가 강화되어 두 부문의 판매량이 증가하고 있습니다.
qPCR은 확립된 프로토콜과 폭넓은 장비 가용성 덕분에 2025년 마이코플라즈마 검사 시장 점유율의 63.85%를 차지하고 있습니다. 15.75%의 성장률을 자랑하는 디지털 PCR은 표준 곡선에 따른 오차를 줄이고, 유전자 치료용 로트에 필수적인 희귀 현상을 검출합니다. 감도 향상은 견고한 정량화를 요구하는 규제 당국 감사관들에게도 지지를 받고 있습니다. 기존 PCR은 구형 시설에 있어 여전히 비용 면에서 유력한 선택지이며, ELISA와 DNA 염색은 틈새 학술 용도에서 여전히 중요한 역할을 하고 있습니다. 차세대 염기서열 분석은 병원체의 다중 스크리닝을 가능하게 할 것으로 기대되지만, 규제 당국의 합의가 필요한 상황입니다.
현재 규제 당국은 출하 검사에서 배양법과 동등한 핵산 분석법을 인정하고 있으며, 이는 디지털 PCR의 보급을 촉진하고 있습니다. 장비 제조업체들은 반응 혼합액을 수천 개의 구획으로 분할하여 검출 한계를 낮추는 마이크로플루이딕스 칩 형식에 대한 투자를 진행하고 있습니다. AI의 활용으로 조작자의 기술 요건이 더욱 완화되어, 실험실에서의 보다 광범위한 도입이 가능해졌습니다.
지역별 분석
북미는 2025년 매출의 40.25%를 차지하며 선두 자리를 유지했습니다. 이는 FDA의 감독, 성숙한 바이오프로세싱 인프라, 그리고 기술의 조기 도입이 안정적인 수요를 뒷받침하고 있기 때문입니다. 이 지역의 바이오 클러스터 밀도와 자금 조달의 용이성이 배양법에서 자동 PCR 시스템으로의 신속한 전환을 촉진하고 있습니다. 서비스 제공업체는 혁신 기업과의 지리적 근접성을 활용하여 적시(JIT) 검체 물류 및 규정 준수 감사를 실현하고 있습니다.
유럽은 이에 이어 EMA의 일관된 규제 프레임워크와 다국간 로트 릴리스를 촉진하는 조화된 약전(pharmacopoeia)을 갖추고 있습니다. 독일, 스페인, 영국에 GMP 시설이 위치해 있어 EU의 유전자 치료 임상시험과 관련된 마이코플라스마 검사 시장 규모가 확대되고 있습니다. 각 벤더사는 다국어 문서화 및 일련번호 부여 요구에 대응하고 있으며, 이는 정보학을 활용한 분석 플랫폼의 발전을 뒷받침하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 18.10%로 확대되고 있으며, 가장 성장세가 두드러진 시장입니다. 중국의 세포 치료 부문은 정부의 우선 목록 등재 혜택을 받고 있는 반면, 인도의 생산 연계형 인센티브 제도는 백신 수출업체들을 유치하고 있습니다. 싱가포르의 분산형 품질 관리(QC) 실험실은 지역 내 생물제제 공장의 처리 시간을 단축시키고 있습니다. 규제 분절화로 인해 현지에서 유효성 검증이 필요해짐에 따라, 서비스 허브를 단일 거점에 집약하는 세계 기업이 유리한 입지를 점하고 있습니다.
남미와 중동 및 아프리카는 절대적인 매출 규모에서는 뒤처져 있지만, 국내 백신 프로그램과 바이오시밀러 제조 시설이 급증하고 있어 미개척 성장 잠재력을 지니고 있습니다. 물류상의 과제와 콜드체인 인프라 부족으로 인해 고속 PCR 장비의 보급은 더딘 편이지만, 교육 및 서비스 네트워크가 성숙해지면 공중보건에 대한 투자가 향후 수주로 이어질 가능성이 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, mycoplasma testing market size in 2026 is estimated at USD 1.26 billion, growing from 2025 value of USD 1.13 billion with 2031 projections showing USD 2.12 billion, growing at 11.10% CAGR over 2026-2031.
This report Segments the Industry Into by Product (Instruments, Kits and Reagents, Services), Technology (Conventional PCR, QPCR, and More), Application (Cell-Line Quality Control, and More), End User (Biopharma and Biotechnology Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Mycoplasma Testing Market Trends and Insights
Expansion of Biopharma and Cell & Gene Therapy Manufacturing Facilities
Capacity ramp-ups in autologous and allogeneic therapy plants have multiplied sample volumes that require 100% batch testing. Contamination prevalence in cell cultures ranges between 15% and 35%, and FDA guidance now mandates mycoplasma testing after pooling and prior to washing, increasing sampling frequency. Continuous perfusion bioreactors raise real-time monitoring needs, pushing demand for automated analyzers that handle higher throughputs with minimal human intervention. Facility roll-outs in emerging markets must complete qualification studies, creating greenfield demand for third-party test services. Together, these trends add 2.8 percentage points to the forecast CAGR.
Regulatory Mandates Require Mycoplasma Release Testing for Biologics
The FDA's laboratory developed tests rule and EMA guidance for advanced therapy medicinal Products require validated assays from a master cell bank to a finished drug. The European Medicines Agency's guidelines for Advanced Therapy Medicinal Products mandate comprehensive mycoplasma testing throughout the manufacturing process, from master cell banks to final product release. These regulatory changes create non-discretionary demand for testing services, as manufacturers cannot release products without demonstrating mycoplasma absence through validated methods. Compliance spending accelerates through 2027 as phased LDT oversight takes effect.The phased implementation of new LDT regulations over four years creates predictable demand growth as laboratories upgrade their testing capabilities to maintain compliance.
High Capital Expenditure for Implementing Automated Detection Systems
Entry-level automated analyzers cost USD 100,000-500,000, with annual service contracts topping USD 50,000. Smaller CTLs and academic labs struggle to justify such outlays, prolonging reliance on manual culture methods. FDA LDT compliance adds validation costs and strains capital budgets, curbing near-term uptake. Smaller contract testing laboratories face particular challenges in justifying automation investments given their limited sample volumes and diverse testing requirements. The complexity of validating automated systems for regulatory compliance adds significant time and cost burdens, with validation studies typically requiring 6-12 months and specialized expertise.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Incidents of Cell-Culture Contamination
- Rising Demand for Rapid, High-Sensitivity PCR-Based Assays
- False-Positive/-Negative Retest Delays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Kits and reagents maintained a 45.72% share in 2025, underlining their consumable nature within the Mycoplasma testing market. The Services segment is set to expand at 14.15% CAGR as biomanufacturers delegate method validation and routine screening to accredited laboratories. High regulatory hurdles and evolving assay formats encourage companies to buy expert capacity instead of building it. Eurofins' network of 45+ global sites illustrates how scale produces cost-efficiencies that individual firms cannot replicate.
Automation-ready instruments show steady but slower growth because purchasers often tie them to long-term reagent contracts. The BIOFIRE platform and Rapid Micro Biosystems' vial-reader appeal by blending speed with pharmacopeial compliance. As services grow, kit vendors align with third-party labs under reagent-rental models that lock in supply revenues. This synergy consolidates buyer-supplier dependencies and drives volume in both categories.
qPCR holds 63.85% of the 2025 Mycoplasma testing market share thanks to entrenched protocols and broad instrument availability. Digital PCR, with a 15.75% growth rate, mitigates standard-curve errors and detects rare events vital for gene-therapy lots. Sensitivity gains resonate with regulatory auditors seeking robust quantification. Conventional PCR remains a budget choice for legacy facilities, while ELISA and DNA staining stay relevant in niche academic applications. Next-generation sequencing promises multiplex pathogen screens but awaits regulatory consensus.
Regulatory bodies now accept nucleic-acid methods equivalent to culture for release testing, catalysing digital PCR uptake. Instrument makers invest in microfluidic chip formats that slice reaction mixes into thousands of partitions, lowering detection thresholds. AI augmentation further lessens operator skill barriers, unlocking broader lab adoption.
Complete Report Scope:
- By Product & Service
- Instruments
- Real-time PCR Systems
- Rapid Microfluidic Analyzers
- Automated Detection Platforms
- Other Instruments
- Kits & Reagents
- PCR Assay Kits
- ELISA Kits
- Enzymatic Assay Kits
- Fluorescent-Staining Reagents
- Others
- Services
- Instruments
- By Technology
- Conventional PCR
- qPCR
- Digital PCR
- ELISA
- Enzymatic Methods
- DNA Staining
- Next-Generation Sequencing
- Other NAATs
- By Application
- Cell-Line Quality Control
- Bioproduction Batch-Release Testing
- Raw-Material & Media Testing
- Gene & Cell Therapy Manufacturing
- Vaccine & Virus Testing
- Other Applications
- By End User
- Biopharma & Biotechnology Companies
- Contract Manufacturing Organizations (CMOs)
- Academic & Research Institutes
- Cell Banks & Repositories
- Diagnostic & Reference Laboratories
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 40.25% of 2025 revenue as FDA oversight, mature bioprocessing infrastructure, and early technology adoption underpin stable demand. The region's biocluster density and capital availability encourage rapid replacement of culture methods with automated PCR systems. Service providers leverage proximity to innovators, enabling just-in-time sample logistics and compliance audits.
Europe follows with a cohesive regulatory framework from the EMA and harmonised pharmacopoeias that facilitate multi-country lot release. The Mycoplasma testing market size tied to EU gene-therapy trials rises as Germany, Spain, and the United Kingdom host GMP facilities. Vendors cater to multi-language documentation and serialization demands, spurring informatics-enabled assay platforms.
Asia-Pacific represents the fastest-growing arena, expanding at 18.10% CAGR. China's cell-therapy sector benefits from government priority listings, while India's production-linked incentive schemes attract vaccine exporters. Singapore's decentralized QC labs shorten turnaround times for regional biologics plants. Fragmented regulations necessitate local validation, favouring global companies that co-locate service hubs.
South America and the Middle East & Africa trail in absolute revenue but offer untapped upside as domestic vaccine programs and biosimilar plants proliferate. Logistics hurdles and limited cold-chain infrastructure slow penetration of rapid PCR devices, yet public-health investments could unlock future orders once training and service networks mature.
- Thermo Fisher Scientific
- Charles River Laboratories Intl. Inc.
- Merck
- Lonza Group Ltd.
- Eurofins
- Sartorius
- Agilent Technologies
- ATCC
- PromoCell
- Minerva Biolabs GmbH
- bioMerieux
- Bionique Testing Laboratories
- WuXi App Tec
- SGS
- Danaher
- Rapid Micro Biosystems
- MicroBioLogics Inc.
- InvivoGen
- Mycoplasma Experience Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Biopharma and Cell & Gene Therapy (CGT) Manufacturing Facilities
- 4.2.2 Regulatory Mandates Require Mycoplasma Release Testing for Biologics
- 4.2.3 Increasing Incidents of Cell-Culture contamination
- 4.2.4 Rising Demand for Rapid, High-Sensitivity PCR-Based Assays
- 4.2.5 Decentralised QC Labs in Emerging Biotech Hubs
- 4.2.6 Venture Capital-Backed Proliferation of Synthetic Biology Startups
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure (CAPEX) for Implementing Automated Detection Systems
- 4.3.2 False-Positive/-Negative Retest Delays
- 4.3.3 Skilled Molecular-QA Workforce Shortages
- 4.3.4 Regulatory Lag Surrounding Approval of Microfluidic and Next-Gen Assays
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product & Service
- 5.1.1 Instruments
- 5.1.1.1 Real-time PCR Systems
- 5.1.1.2 Rapid Microfluidic Analyzers
- 5.1.1.3 Automated Detection Platforms
- 5.1.1.4 Other Instruments
- 5.1.2 Kits & Reagents
- 5.1.2.1 PCR Assay Kits
- 5.1.2.2 ELISA Kits
- 5.1.2.3 Enzymatic Assay Kits
- 5.1.2.4 Fluorescent-Staining Reagents
- 5.1.2.5 Others
- 5.1.3 Services
- 5.1.1 Instruments
- 5.2 By Technology
- 5.2.1 Conventional PCR
- 5.2.2 qPCR
- 5.2.3 Digital PCR
- 5.2.4 ELISA
- 5.2.5 Enzymatic Methods
- 5.2.6 DNA Staining
- 5.2.7 Next-Generation Sequencing
- 5.2.8 Other NAATs
- 5.3 By Application
- 5.3.1 Cell-Line Quality Control
- 5.3.2 Bioproduction Batch-Release Testing
- 5.3.3 Raw-Material & Media Testing
- 5.3.4 Gene & Cell Therapy Manufacturing
- 5.3.5 Vaccine & Virus Testing
- 5.3.6 Other Applications
- 5.4 By End User
- 5.4.1 Biopharma & Biotechnology Companies
- 5.4.2 Contract Manufacturing Organizations (CMOs)
- 5.4.3 Academic & Research Institutes
- 5.4.4 Cell Banks & Repositories
- 5.4.5 Diagnostic & Reference Laboratories
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Thermo Fisher Scientific Inc.
- 6.3.2 Charles River Laboratories Intl. Inc.
- 6.3.3 Merck KGaA
- 6.3.4 Lonza Group Ltd.
- 6.3.5 Eurofins Scientific SE
- 6.3.6 Sartorius AG
- 6.3.7 Agilent Technologies
- 6.3.8 ATCC
- 6.3.9 PromoCell GmbH
- 6.3.10 Minerva Biolabs GmbH
- 6.3.11 bioMerieux SA
- 6.3.12 Bionique Testing Laboratories Inc.
- 6.3.13 WuXi AppTec
- 6.3.14 SGS SA
- 6.3.15 Danaher Corporation
- 6.3.16 Rapid Micro Biosystems
- 6.3.17 MicroBioLogics Inc.
- 6.3.18 InvivoGen
- 6.3.19 Mycoplasma Experience Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment