

|
시장보고서
상품코드
2121464
화학 센서 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Chemical Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
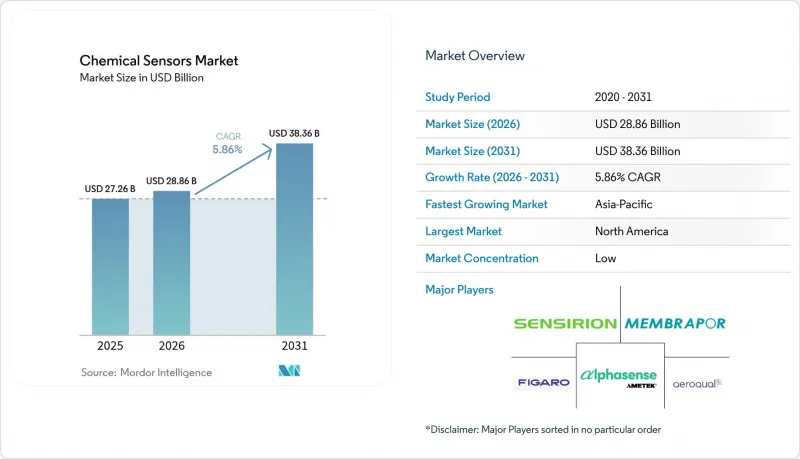
화학 센서 시장 규모는 2026년에 288억 6,000만 달러로 추정되며, 2025년 272억 6,000만 달러에서 확대되어 2031년에는 383억 6,000만 달러에 달할 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 5.86%가 될 것으로 전망됩니다.
본 보고서는 제품 유형(전기화학 센서, 광학 센서 등), 기술(CMOS 집적 센서, MEMS 기반 센서 등), 용도(환경 모니터링, 의료 진단, 자동차 배기가스 및 차량 실내 공기 등), 분석 대상 상(기상, 액상, 고상), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 화학 센서 시장의 동향 및 인사이트
엄격한 환경 규제가 산업용 가스 감지 수요를 견인
2024년 미국 국가 대기질 기준(NAAQS) 개정에 따라 PM2.5의 연간 허용치가 하향 조정되었으며, 시설은 이산화황 및 이산화질소의 전기화학식 측정 데이터를 실시간으로 전송하는 멀티 가스 모니터의 설치를 의무화했습니다. 유럽연합(EU)도 같은 해 산업 배출 지침을 개정하여, 처리량이 100톤을 초과하는 화학 공장에 대해 휘발성 유기 화합물(VOC) 측정값을 거의 지속적으로 공개하도록 의무화했습니다. 중국은 2025년 중반까지 대기 환경 모니터링 네트워크를 1,800곳으로 확대했으며, 각 관측 지점에서는 오존, 일산화탄소, 질소산화물 측정 셀이 가동되고 있어, 이 모든 것을 합쳐 4억 달러 규모의 조달 시장이 형성되었습니다. 인도의 중앙공해관리위원회는 화력발전소에 배출원 모니터링 시스템 도입을 의무화함에 따라, 2025년 초에는 센서 출하대수가 전년 대비 31% 급증했습니다. 정유소에서는 촉매 비드식 엘리먼트를 적외선식 헤드로 교체함으로써 오경보를 40% 줄이고 교정 주기를 2배로 연장하고 있어, 이러한 규제 측면의 호재가 더욱 강화되고 있습니다.
의료 진단 분야에서의 소형화된 전기화학 센서 채택 확대
미국 식품의약국(FDA)은 2024년, 폼팩터를 15mm 미만으로 소형화한 7개의 새로운 현장 진단용 전기화학 플랫폼을 승인하여 병원 및 가정에서의 사용 사례를 개척했습니다. 애보트(Abbott)사의 ‘FreeStyle Libre’는 2024년에 53억 달러의 매출을 기록하며 전년 대비 21% 증가했습니다. 이는 보험 환급을 원동력으로 한 암페로메트릭 방식의 포도당 산화효소 스택의 보급을 뒷받침하는 결과입니다. 센시리온(Sensirion)은 2025년 3월, 인공호흡기 회로에 적합한 10mm 정사각형 이산화탄소 센서를 발표했습니다. 이 센서의 비용은 적외선 방식 대체 제품의 3분의 1 수준입니다. 유럽의 체외진단용 의료기기 규정(IVDR)은 2024년 5월 검출 한계에 관한 규제를 강화했으며, 이에 따라 젖산의 검출 한계를 1µM 미만으로 낮추는 나노 구조 전극의 개발이 촉진되었습니다. 2024년에는 지구력 운동선수를 위한 스크린 인쇄 방식의 땀 중 젖산 패치가 출시되어, 이미 2-25 mM 범위를 실시간으로 측정할 수 있게 되었습니다.
비용에 민감한 업계에서는 교정 및 유지보수 비용이 도입의 장벽이 되고 있습니다.
90-180일마다 현장에서 진행하는 교정에는 기기 1대당 150-300달러의 비용이 소요되며, 5년간의 운영 기간 동안 하드웨어 초기 투자액을 금세 상회하게 됩니다. 2024년에 340개 식품 가공업체를 대상으로 실시한 조사에 따르면, 1개 거점당 연간 유지비가 1만 8,000달러로 추정되며, 이는 설비 투자액의 2.8배에 해당하므로 도입 범위 확대를 저해하고 있습니다. 순이익률이 5% 미만인 창고 운영 사업자의 경우, 서비스 계약이 예산을 압박하기 때문에 연속 감시 장치보다 휴대용 스팟 체크를 선호합니다. NFPA는 2025년에 주거용 일산화탄소 감지기의 점검 주기를 7년 주기로 완화했지만, 산업용 장치는 여전히 분기별 일정이 유지되고 있어 이러한 비용 격차를 고착화시키고 있습니다.
부문 분석
2025년 매출액 중 전기화학식 센서가 32.31%를 차지하고 있으며, 정유소 및 하수 처리장에서의 황화수소, 일산화탄소, 이산화질소 경보 장치로는 여전히 주류를 이루고 있습니다. 광학식 장치는 유지보수 간격을 24개월 이상으로 연장할 수 있는 비분산형 적외선(NDIR) 센서로 전환이 진행됨에 따라 2031년까지 연평균 성장률(CAGR) 6.98%로 확대되고 있습니다.
한때 가연성 가스 감지의 주력 제품이었던 촉매 비드식 센서는 본질 안전 규정에 따라 점화가 수반되지 않는 광학식이 권장됨에 따라 시장 점유율이 17.60% 미만으로 떨어졌습니다. 현재 수요의 21.70%를 차지하는 반도체 금속 산화물 장치는 5달러 미만의 가격대가 중요한 저예산 실내 공기 감지 용도에서 주류를 이루고 있습니다. 천연가스 파이프라인 검사에서 적외선 분광법의 업그레이드로 인해 10억 분의 1 단위의 메탄 검출이 가능해졌으며, 이것이 광학식 센서의 보급을 가속화하는 주요 이유입니다. 미국의 메탄 감축 인센티브로 인해 이러한 모듈에 대한 수요는 연간 2억 8,000만 달러 증가하고 있습니다. 전기화학식 단일 가스 감지기는 여전히 개인보호구 분야에서 주류를 이루고 있습니다. 이는 전해액의 소모가 재구매와 예측 가능한 교체 주기를 가져와, 소모품 매출 측면에서 화학 센서 시장의 견조한 성장세를 유지하고 있기 때문입니다.
MEMS 파생 제품은 5mm 실리콘 다이에 감지 소자와 혼합 신호 ASIC을 통합함으로써 2025년 매출의 27.02%를 차지했습니다. 웨이퍼 레벨 패키징은 조립 비용을 대폭 절감하여 소매용 공기질 모니터의 가격을 50달러 미만으로 낮췄습니다. 롤 투 롤(R2R) 그라비어 인쇄 기술로 일회용 바이오 센싱 스트립의 단가가 0.10달러까지 하락함에 따라, 프린트형 및 플렉서블형은 연평균 성장률(CAGR) 6.86%를 기록하며 스포츠 분야와 분산형 의료 분야에서 새로운 가능성을 열어가고 있습니다.
현재 18.70%의 점유율을 차지하는 CMOS 집적형 유닛은 온칩 보정 기능을 탑재하여 부품 비용을 30% 절감합니다. 적외선 차단 제품은 수요의 약 20.80%를 차지하며, 광학 수명이 10년을 초과하는 HVAC, 인큐베이터, 온실 등에서 사용되고 있습니다. 표면탄성파(SAW) 제품 라인은 시장 점유율이 약 12.80%로, 화학무기 경보와 같은 틈새 방위 용도에 국한되어 있지만, 충격 및 진동 시험에 관한 표준화가 진전됨에 따라 운송 안전 분야에서의 매력이 높아지고 있습니다. 현재 ISO 27891 규격에서는 MEMS 가스 센서 칩에 대해 1,500g의 충격을 받아도 드리프트가 발생하지 않아야 한다고 요구하고 있으며, 주요 공급업체 대부분이 이 기준을 충족함에 따라 자동차 및 산업 분야 구매자들의 신뢰가 더욱 높아지고 있습니다.
지역별 분석
북미는 2025년 매출의 46.55%를 차지했으며, 이러한 선두 위상은 OSHA(미국 직업안전보건청)의 엄격한 밀폐 공간 관련 법규와 혈당 모니터링 수혜자를 320만 명 늘린 메디케어의 확대에 힘입은 것입니다. 2024년 PM2.5 기준에 따라 3억 4,000만 달러 규모의 센서 교체 열풍이 일고 있으며,캐나다는 오존 및 미세먼지 관측 네트워크를 외딴 지역 사회까지 확대하기 위해 1억 8,000만 캐나다 달러(1억 3,300만 달러)를 배정했습니다.
유럽은 매출의 27.98%를 차지했습니다. 이 지역의 유로 7 배기가스 기준 도입으로 인해 -40-85°C 범위에서 ±10%의 정확도가 의무화되면서, 전기화학식 및 고체식 스택에 대한 안정적인 수주가 발생하고 있습니다. 독일은 각각 1초 미만의 측정이 가능한 이중화된 검출기가 필요한 수소 충전소에 5억 유로(5억 6,500만 달러)를 배정했습니다. 한편, 영국은 포름알데히드의 허용 농도를 0.3 ppm으로 낮추었으며, 이로 인해 각 연구소의 장비 업그레이드가 촉진되었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.88%를 기록하며, 다른 모든 지역을 능가하는 성장이 예상됩니다. 중국의 1,800개 노드로 구성된 대기 모니터링 네트워크와 공장용 VOC 규제, 인도의 배출원 모니터링 도입, 그리고 일본의 수소 연료 로드맵이 맞물려 수십억 달러 규모의 입찰 시장이 창출될 전망입니다. 한국의 반도체 VOC 관련 법에 따라 연간 8,500만 달러의 수요가 추가로 예상됩니다. 중동 및 아프리카 및 남미는 여전히 시장 규모가 작지만, 적외선 메탄 감지기를 핵심으로 하는 국가 차원의 가스 파이프라인 안전 법규로의 전환이 진행되고 있어, 현지 시스템 통합업체들에게 장기적인 비즈니스 기회가 창출되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the chemical sensors market size in 2026 is estimated at USD 28.86 billion, growing from 2025 value of USD 27.26 billion with 2031 projections showing USD 38.36 billion, growing at 5.86% CAGR over 2026-2031.
This report is Segmented by Product Type (Electrochemical Sensors, Optical Sensors, and More), Technology (CMOS-Integrated Sensors, MEMS-Based Sensors, and More), Application (Environmental Monitoring, Medical Diagnostics, Automotive Emissions and Cabin Air, and More), Analyte Phase (Gas Phase, Liquid Phase, and Solid Phase), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Chemical Sensors Market Trends and Insights
Stringent Environmental Regulations Driving Demand For Industrial Gas Detection
Revisions to the U.S. National Ambient Air Quality Standards in 2024 lowered the annual PM2.5 limit, obliging facilities to install multi-gas monitors that stream electrochemical sulfur-dioxide and nitrogen-dioxide data in real time. The European Union amended its Industrial Emissions Directive the same year, forcing chemical plants over 100 tonnes throughput to publish near-continuous volatile-organic-compound readouts. China expanded its ambient network to 1,800 stations by mid-2025 and each site runs ozone, carbon-monoxide, and nitrogen-oxides cells that collectively created a USD 400 million procurement pool. India's Central Pollution Control Board mandated Source Emission Monitoring Systems for thermal plants, which spurred a 31% YoY spike in sensor shipments during early 2025. Refineries swapping catalytic-bead elements for infrared heads have cut false alarms by 40% and doubled calibration intervals, reinforcing this regulatory tailwind.
Growing Adoption Of Miniaturized Electrochemical Sensors In Medical Diagnostics
The U.S. FDA cleared seven new point-of-care electrochemical platforms in 2024 that shrink form factors under 15 mm, opening hospital and at-home use cases. Abbott's FreeStyle Libre posted USD 5.3 billion revenue in 2024, up 21% YoY, underscoring reimbursement-led diffusion of amperometric glucose oxidase stacks. Sensirion introduced a 10 mm-square carbon-dioxide cell in March 2025 that fits ventilator circuits at one-third the cost of infrared alternatives. Europe's In Vitro Diagnostic Regulation tightened detection-limit rules in May 2024, prompting nanostructured electrodes that drop lactate thresholds below 1 µM. Screen-printed sweat-lactate patches launched for endurance athletes in 2024 and already measure 2-25 mM ranges on the fly.
Calibration And Maintenance Costs Limit Adoption In Cost-Sensitive Industries
Field calibration every 90-180 days costs USD 150-300 per instrument and quickly eclipses hardware outlays over a five-year run. A 2024 survey of 340 food processors pegged annual upkeep at USD 18,000 per site, 2.8 times capex, discouraging broader coverage. Warehousing operators running net margins below 5% favor handheld spot checks over continuous monitors because service contracts strain budgets. NFPA eased residential carbon-monoxide detector intervals to seven-year cycles in 2025, but industrial units remain on quarterly schedules, cementing this cost divide.
Other drivers and restraints analyzed in the detailed report include:
- Expansion Of Industrial Automation And Process Safety Systems
- Emergence Of Flexible Printed Chemical Sensors For Disposable IoT Devices
- Sensor Drift And Limited Lifespan Affect Long-Term Reliability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electrochemical cells captured 32.31% of 2025 revenue and remain the preferred route for hydrogen-sulfide, carbon-monoxide, and nitrogen-dioxide alarms in refineries and wastewater plants. Optical devices are expanding at a 6.98% CAGR through 2031 as operators migrate toward non-dispersive infrared heads that extend maintenance intervals beyond 24 months.
Catalytic-bead sensors, once a staple for combustible gas, are slipping below 17.60% share because intrinsic-safety rules encourage ignition-free optics. Semiconductor metal-oxide devices, now 21.70% of demand, dominate budget indoor-air applications where sub-USD 5 price points matter. Infrared spectroscopy upgrades in natural-gas pipeline inspection push parts-per-billion methane detection and are a key reason optical traction is accelerating. U.S. methane-reduction incentives add a USD 280 million annual pull for these modules. Electrochemical single-gas badges still rule personal protective gear because electrolyte depletion drives repeat sales and predictable replacement cycles, keeping the chemical sensors market robust in consumables revenue.
MEMS variants delivered 27.02% of 2025 revenue by slipping sensing elements and mixed-signal ASICs onto 5 mm silicon dies. Wafer-level packaging slashes assembly overhead and has pulled retail air-quality monitors under USD 50. Printed and flexible formats are logging a 6.86% CAGR as roll-to-roll gravure drops unit cost to USD 0.10 for single-use biosensing strips, opening new frontiers in athletics and decentralized medicine.
CMOS-integrated units, currently 18.70% share, add on-chip calibration that pares bill-of-materials by 30%. Infrared blocks represent about 20.80% of demand, serving HVAC, incubators, and greenhouses where optical lifetime exceeds a decade. Surface-acoustic-wave lines, roughly 12.80% share, stay in niche defense roles for chemical warfare agent alerts, but standardization work on shock and vibration tests is making them more attractive in transport safety. ISO 27891 now requires MEMS gas chips to survive 1,500 g shock with no drift, a hurdle most mainline suppliers have cleared, shoring up confidence in automotive and industrial buyers.
Complete Report Scope:
- By Product Type
- Electrochemical Sensors
- Optical Sensors
- Pellistor/Catalytic Bead Sensors
- Semiconductor Sensors
- Other Product Type
- By Technology
- CMOS-Integrated Sensors
- MEMS-Based Sensors
- NDIR and Infrared Sensors
- SAW and Acoustic Sensors
- Printed/Flexible Sensors
- By Application
- Industrial Safety and Process Control
- Environmental Monitoring
- Medical Diagnostics
- Automotive Emissions and Cabin Air
- Oil and Gas Exploration and Refining
- Homeland Security and Defense
- Other Application
- By Analyte Phase
- Gas Phase
- Liquid Phase
- Solid Phase
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 46.55% of 2025 revenue, a lead built on strict OSHA confined-space laws and Medicare expansion that added 3.2 million glucose-monitoring beneficiaries. The 2024 PM2.5 standard drove a USD 340 million sensor retrofit wave, and Canada earmarked CAD 180 million (USD 133 million) to extend ozone and particulate networks into remote communities.
Europe contributed 27.98% of sales; its shift to Euro 7 exhaust norms mandates +-10% accuracy across -40-85 °C, generating steady orders for electrochemical and solid-state stacks. Germany carved EUR 500 million (USD 565 million) for hydrogen stations that each need redundant sub-second detectors, while the United Kingdom cut the formaldehyde limit to 0.3 ppm, spurring upgrades across laboratories.
Asia-Pacific is projected to outpace all regions at a 6.88% CAGR through 2031. China's 1,800-node air network and factory VOC rules, India's Source Emission Monitoring rollout, and Japan's hydrogen-fuel road map combine to unlock multi-billion-dollar tenders. South Korea's semiconductor VOC law adds another USD 85 million annual pull. Middle East and Africa and South America remain smaller slices but are moving toward national gas-pipeline safety laws that hinge on infrared methane trackers, creating long-tail opportunities for local integrators.
- Alphasense Limited
- Figaro Engineering Inc.
- Membrapor AG
- Sensirion AG
- Aeroqual Limited
- SGX Sensortech Limited
- Nemoto & Co., Ltd.
- SPEC Sensors, LLC
- Sensitron S.r.l.
- NTM Sensors
- Dynament Limited
- City Technology Limited
- Gas Sensing Solutions Ltd.
- Zhengzhou Winsen Electronics Technology Co., Ltd.
- Sensorix GmbH
- DD-Scientific Ltd.
- SST Sensing Ltd.
- Crowcon Detection Instruments Limited
- PureAire Monitoring Systems, Inc.
- Aeroqual Limited (repeat for completeness)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors
- 4.3 Industry Value Chain Analysis
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Market Drivers
- 4.6.1 Stringent Environmental Regulations Driving Demand For Industrial Gas Detection
- 4.6.2 Growing Adoption Of Miniaturized Electrochemical Sensors In Medical Diagnostics
- 4.6.3 Expansion Of Industrial Automation And Process Safety Systems
- 4.6.4 Emergence Of Flexible Printed Chemical Sensors for Disposable IoT Devices
- 4.6.5 Integration Of Chemical Sensors into Hydrogen Infrastructure Safety Systems
- 4.6.6 Rapid Proliferation Of Indoor Air Quality Mandates In Commercial Real Estate
- 4.7 Market Restraints
- 4.7.1 Calibration And Maintenance Costs Limit Adoption In Cost-Sensitive Industries
- 4.7.2 Sensor Drift And Limited Lifespan Affect Long-Term Reliability
- 4.7.3 Supply Chain Bottlenecks For Specialty Electrochemical Catalysts
- 4.7.4 Data Governance Concerns Slowing Deployment Of Cloud-Connected Sensors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Electrochemical Sensors
- 5.1.2 Optical Sensors
- 5.1.3 Pellistor/Catalytic Bead Sensors
- 5.1.4 Semiconductor Sensors
- 5.1.5 Other Product Type
- 5.2 By Technology
- 5.2.1 CMOS-Integrated Sensors
- 5.2.2 MEMS-Based Sensors
- 5.2.3 NDIR and Infrared Sensors
- 5.2.4 SAW and Acoustic Sensors
- 5.2.5 Printed/Flexible Sensors
- 5.3 By Application
- 5.3.1 Industrial Safety and Process Control
- 5.3.2 Environmental Monitoring
- 5.3.3 Medical Diagnostics
- 5.3.4 Automotive Emissions and Cabin Air
- 5.3.5 Oil and Gas Exploration and Refining
- 5.3.6 Homeland Security and Defense
- 5.3.7 Other Application
- 5.4 By Analyte Phase
- 5.4.1 Gas Phase
- 5.4.2 Liquid Phase
- 5.4.3 Solid Phase
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Alphasense Limited
- 6.4.2 Figaro Engineering Inc.
- 6.4.3 Membrapor AG
- 6.4.4 Sensirion AG
- 6.4.5 Aeroqual Limited
- 6.4.6 SGX Sensortech Limited
- 6.4.7 Nemoto & Co., Ltd.
- 6.4.8 SPEC Sensors, LLC
- 6.4.9 Sensitron S.r.l.
- 6.4.10 NTM Sensors
- 6.4.11 Dynament Limited
- 6.4.12 City Technology Limited
- 6.4.13 Gas Sensing Solutions Ltd.
- 6.4.14 Zhengzhou Winsen Electronics Technology Co., Ltd.
- 6.4.15 Sensorix GmbH
- 6.4.16 DD-Scientific Ltd.
- 6.4.17 SST Sensing Ltd.
- 6.4.18 Crowcon Detection Instruments Limited
- 6.4.19 PureAire Monitoring Systems, Inc.
- 6.4.20 Aeroqual Limited (repeat for completeness)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


