

|
시장보고서
상품코드
2121465
전자 처방전 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)E-prescribing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
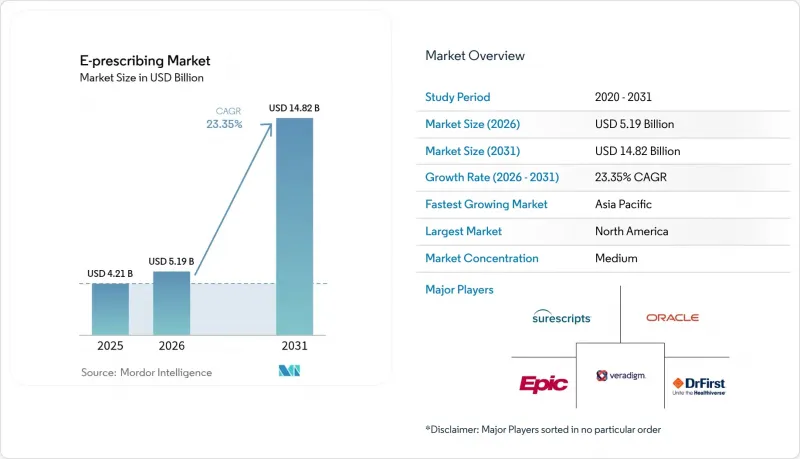
에 의하면, 전자 처방전 시장 규모는 2025년에 42억 1,000만 달러로 평가되었고, 2026년 51억 9,000만 달러에서 2031년까지 148억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 23.35%를 기록할 전망입니다.
본 보고서는 구성 요소(하드웨어 등), 시스템 유형(독립형 시스템 등), 제공 형태(클라우드 기반, 웹형 등), 처방전 유형(NewRx 등), 최종 사용자(병원 등), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 전자 처방전 시장 동향 및 인사이트
전자 처방전 도입에 관한 정부의 의무화
전자 처방전 의무화에 관한 법률에 따라 전 세계적으로 처방 워크플로우 재편이 진행되고 있습니다. 미국 마약단속국(DEA)이 도입할 예정인 특별 등록 체계에서는 3단계 원격의료 인가 제도가 도입되며, 임상의는 주별 원격의료 자격을 보유해야 하고, 스케줄 II-V 의약품에 대해서는 전자 처방전 사용이 의무화됩니다. 2022년 1월 이후, 규제 약물 여부와 관계없이 모든 처방전을 전자화하도록 의무화한 캘리포니아주의 규정은 규제가 얼마나 빠르게 확대되고 있는지를 보여주고 있으며, 현재 35개 주에서 EPCS(전자 처방전 시스템) 관련 법을 시행하고 있습니다. CMS(미국 의료보험의료서비스센터)는 2028년 1월 NCPDP SCRIPT 표준 버전 2023011로의 전환을 이미 확정했으며, 시스템에 실시간 급여 도구 및 강화된 처방약 목록 데이터 지원을 의무화하고 있습니다. 각 주의 처방약 모니터링 프로그램을 확인하도록 의무화하는 연방 요건이 3년 이내에 시행될 예정이며, 이로 인해 전자 처방전이 규제 약물의 유일한 안전한 경로로 더욱 자리 잡게 될 것입니다. 이러한 연쇄적인 규제로 인해 전자 처방전 시장을 자연 성장률을 훨씬 능가하는 속도로 견인하는 업데이트 주기가 형성되고 있습니다.
의약품 안전성과 의료의 질에 대한 관심이 높아지고 있다.
환자 안전 확보가 시급한 과제로 대두됨에 따라, 의료 시스템은 미국에서 연간 12만 5,000명의 사망과 관련된 실수를 줄이기 위해 첨단 처방 도구의 도입을 촉구받고 있습니다. Surescripts사의 ‘Sig IQ’는 2024년에 41억 건의 환자 지시를 처리했으며, 자유 형식의 텍스트를 구조화된 지시로 변환함으로써 이상반응으로 인한 응급실 방문을 줄였습니다. Epic Systems사는 약물 상호작용을 선별하고 최적의 투여량을 제안하는 100개 이상의 AI 기반 처방 관리 기능을 통합했습니다. 또한 DEA는 EPCS에 대해 오인식률이 0.001 미만인 생체 인증을 의무화하고 있어, 이에 따라 보안 요건이 강화되면서 프리미엄 플랫폼이 유리한 입장에 놓이게 되었습니다. 약물 요법 관리 시스템은 현재 처방 이력과 실시간 복약 준수 상황 모니터링을 결합하여, 연간 2,500억 달러에 달하는 복약 불이행으로 인한 비용 문제를 해결하고 있습니다. 실시간 급여 도구는 화면상에서 비용 및 처방약 목록에 대한 피드백을 제공함으로써 처방 1건당 37달러를 절감하고, 안전성을 한층 더 높이고 있습니다.
데이터 개인정보 보호 및 사이버 보안에 대한 우려
의료 분야는 여전히 랜섬웨어의 주요 표적이 되고 있습니다. 체인지 헬스케어(Change Healthcare)에 대한 공격으로 인해 미국 환자의 3분의 1 이상에서 처방 워크플로가 중단되어, 긴급 상황에서 종이 문서를 통한 처리를 할 수밖에 없었습니다. DEA는 또한 범죄자들이 대량의 부정 처방전을 작성할 수 있게 하는 EHR 인증 정보 도난에 대해서도 경고하고 있습니다. '의료 사이버 보안 개선법(Health Care Cybersecurity Improvement Act)'과 같은 입법안은 메디케어 지급을 보안 대책의 구축 현황과 연계하는 것으로, 소규모 진료소에게는 추가적인 비용 부담이 됩니다. 2단계 인증 의무화, 디지털 서명, 상세한 감사 추적 기록 도입은 운영상의 복잡성을 더욱 가중시킵니다. 지방이나 소규모 의료 기관의 경우, 엄격한 요건을 충족하기 위한 자금이나 전문 지식이 부족한 경우가 많아 도입이 지연되고, 의료 서비스가 충분히 제공되지 않는 지역의 전자 처방전 시장 축소로 이어지고 있습니다.
부문 분석
2025년에는 소프트웨어가 매출의 64.92%를 차지할 것으로 예상되며, 이는 병원 및 진료소 전반에 걸친 핵심 라이선싱 수요를 반영합니다. 반면, 서비스 부문은 연평균 성장률(CAGR) 26.12%를 나타낼 것으로 예측되며, 이는 조직들이 현재 도입 지원, 규제 관련 지침, 지속적인 최적화를 얼마나 중요하게 여기는지를 여실히 보여줍니다. 2024년 Surescripts에서 발생한 41억 건의 Sig IQ 지시는 기본적인 데이터 전송에서 부가가치 있는 약물 관리로의 전환을 보여줍니다.
서비스의 급속한 성장은 기술만으로는 처방 관련 과제를 해결할 수 없음을 뒷받침합니다. 현재 도입 과정에는 대면 교육, 변경 관리 워크숍, 헬프데스크 아웃소싱 등이 일상적으로 포함됩니다. 이러한 서비스의 추가로 공급업체는 정착도가 높은 구독형 수익을 얻게 되며, 성숙한 지역에서도 전자 처방 시장이 유지되고 있습니다. DEA의 생체 인증 요건 및 향후 SCRIPT 기준에 대응하기 위한 정기적인 업그레이드가 이 부문의 장기적인 성장 궤도를 공고히 하고 있습니다.
통합형 EHR(전자건강기록) 또는 HIS(병원정보시스템) 솔루션은 진료 현장의 워크플로우에 통합되어 있다는 강점을 살려, 2025년에는 전자 처방 시장의 71.62%를 차지했습니다. 모바일 우선 앱은 회진이나 재택 방문 중에 즉시 처방 입력이 가능한 보안 태블릿 및 스마트폰 덕분에 연평균 성장률(CAGR) 26.05%라는 기세로 추격하고 있습니다. 독립형 시스템은 EHR의 전면 도입이 여전히 현실적이지 않은 틈새 환경에서 여전히 중요한 역할을 수행하고 있습니다.
Epic사가 전개하는 AI 탑재 처방 도구의 확산은 EHR 대기업들이 어떻게 시장 점유율을 지키고 있는지를 보여주고 있으며, 한편 소규모 모바일 계열의 신규 진출기업들은 사용 편의성과 저렴한 초기 비용을 무기로 경쟁하고 있습니다. 모바일 솔루션은 아웃리치 프로그램, 임시 진료소, 재해 피해 지역에서도 활용되고 있습니다. 그러나 통합형 제품군은 복잡한 다제 병용 관리에 필수적인 검사 수치, 문제 목록, 의사결정 지원 기능에 대한 보다 심층적인 접근을 여전히 제공합니다.
지역별 분석
2025년, 북미는 전자 처방 시장에서 38.11%의 점유율을 차지하며 시장을 주도했습니다. 이는 성숙한 네트워크 인프라와 강력한 연방 정부의 규제에 힘입은 결과입니다. 같은 해 Surescripts는 미국 플랫폼에서 25억 건의 처방전을 처리하며 그 확고한 입지를 부각시켰습니다. Change Healthcare의 정보 유출 사건과 같은 끊임없는 사이버 보안 문제와 지속되는 데이터 공유 과제는 이 지역의 향후 투자 필요성을 부각시키고 있지만, 메디케어 및 민간 보험에 통합된 인센티브가 성장 모멘텀을 유지하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 25.02%로 가장 빠른 성장 궤도를 보였습니다. 일본에서는 모든 국민의 마이넘버 ID와 처방전 이력을 연계하는 전국 규모의 데이터베이스 도입이 추진되고 있는 반면, 중국에서는 ‘삼의 연계’ 정책 하에 진료·보험·약국을 통합한 네트워크 구축이 진행되고 있습니다. 인도, 한국, 호주 정부도 마찬가지로 전국적인 의약품 감시 시스템을 우선시하고 있으며, 이를 통해 의료 제공업체는 레거시 시스템의 제약 없이 클라우드 및 모바일 솔루션을 도입할 수 있는 획기적인 기회가 창출되고 있습니다. 2027년까지 중국에서 1,380억 달러에 달할 것으로 예상되는 의료 지출은 전자 처방전 시장의 확대에 큰 여지를 제공합니다.
유럽에서는 독일의 ‘e-Rezept’ 프로그램과 현재월310만 건의 재처방 요청을 처리하고 있는 NHS의 모바일 앱을 통한 처방 서비스가 주도하며 꾸준한 진전이 나타나고 있습니다. EU 27개 회원국의 다양한 규제 환경이 조화로운 발전을 늦추고 있지만, 엄격한 데이터 보호 체계가 소비자의 신뢰를 뒷받침하고 있습니다. 남미, 중동 및 아프리카는 여전히 발전 단계에 있지만 매력적인 시장입니다. 브라질, 사우디아라비아, 아랍에미리트에서는 공공 부문의 디지털화가 초기 프로젝트를 주도하고 있습니다. 따라서 전 세계적인 전망으로는 북미와 유럽의 성숙한 이용 현황에 더해, 아시아태평양의 급속한 확대 및 신흥 지역에서의 선별적인 시범 도입이 결합되어 전자 처방전 시장의 장기적인 성장이 지속될 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the electronic prescribing market size was valued at USD 4.21 billion in 2025 and estimated to grow from USD 5.19 billion in 2026 to reach USD 14.82 billion by 2031, at a CAGR of 23.35% during the forecast period (2026-2031).
This report is Segmented by Component (Hardware, and More), Type of System (Stand-Alone Systems, and More), Delivery Mode (Cloud-Based, Web-Based, and More), Prescription Type (NewRx. And More), End User (Hospitals, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global E-prescribing Market Trends and Insights
Government Mandates for Electronic Prescription Adoption
Mandatory e-prescribing laws are realigning prescription workflows worldwide. The DEA's forthcoming special registration framework introduces three tiers of telemedicine authorization, obliging clinicians to hold state-specific telemedicine credentials and use electronic prescriptions for Schedule II-V drugs. California's rule that all prescriptions-controlled or not-be electronic since January 2022 shows how quickly mandates expand, with 35 states now enforcing EPCS legislation. CMS has already confirmed the transition to NCPDP SCRIPT Standard version 2023011 in January 2028, compelling systems to support real-time benefit tools and enhanced formulary data. A federal requirement to check state Prescription Drug Monitoring Programs is set for implementation within three years, further cementing e-prescribing as the only secure route for controlled substances. These cascading rules create a replacement cycle that drives the electronic prescribing market far beyond organic growth.
Rising Focus On Medication Safety And Quality Of Care
Patient-safety imperatives push healthcare systems to adopt advanced prescribing tools that reduce errors linked to 125,000 deaths a year in the United States. Surescripts' Sig IQ translated 4.1 billion patient directions in 2024, converting free text to structured instructions that cut emergency department visits for adverse events. Epic Systems embedded more than 100 AI-based prescription management features that screen interactions and suggest optimal dosing. The DEA also requires biometric authentication with a false match rate below 0.001 for EPCS, escalating security needs that favor premium platforms. Medication therapy management systems now combine prescription histories with real-time adherence monitoring, addressing USD 250 billion in annual non-adherence costs. Real-time benefit tools further enhance safety by saving patients USD 37 per prescription through on-screen cost and formulary feedback.
Data Privacy And Cybersecurity Concerns
Healthcare remains a prime ransomware target. The Change Healthcare attack interrupted prescription workflows for more than one-third of U.S. patients, forcing emergency paper-based processes. The DEA has also warned about EHR credential theft that allows criminals to generate massive volumes of fraudulent scripts. Legislative proposals like the Health Care Cybersecurity Improvement Act would tie Medicare payments to security readiness, adding cost burdens for small practices. Mandatory two-factor authentication, digital signatures, and detailed audit trails further raise operating complexity. Rural or small providers often lack funds and expertise to meet stringent requirements, slowing adoption and narrowing the electronic prescribing market in underserved regions.
Other drivers and restraints analyzed in the detailed report include:
- Need For Healthcare Cost Reduction And Operational Efficiency
- Growing Penetration Of Cloud-Based Healthcare IT Infrastructure
- Lack Of Interoperability And Data Standardization
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025 software accounted for 64.92% of revenue, reflecting core licensing demand across hospitals and clinics. Services, however, projected at a 26.12% CAGR, underline how organizations now value onboarding support, regulatory guidance, and continuous optimization. Surescripts' 4.1 billion Sig IQ instructions in 2024 illustrate a shift from basic data transport to value-added medication management.
The services boom reinforces that technology alone does not solve prescribing challenges. Implementation now routinely covers classroom training, change-management workshops, and help-desk outsourcing. This service overlay creates sticky, subscription-like income for vendors and sustains the electronic prescribing market even in mature geographies. Recurrent upgrades to meet DEA biometrics or upcoming SCRIPT standards secure the segment's long-term growth trajectory.
Integrated EHR or HIS solutions held 71.62% of the electronic prescribing market in 2025, capitalizing on their embedded role in point-of-care workflow. Mobile-first apps are catching up with a 26.05% CAGR thanks to secure tablets and smartphones that enable immediate order entry during rounds or home visits. Stand-alone systems stay relevant in niche environments where full EHR rollouts remain impractical.
Epic's wave of AI-enabled prescribing tools demonstrates how EHR giants defend share, while smaller mobile entrants compete on usability and low upfront cost. Mobile solutions also serve outreach programs, pop-up clinics, and disaster zones. Yet integrated suites still provide deeper access to lab values, problem lists, and decision support-capabilities crucial for complex polypharmacy management.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Type of System
- Stand-alone Systems
- Integrated EHR/HIS Systems
- Mobile-first Apps
- By Delivery Mode
- Cloud-based
- Web-based
- On-premise
- API Platform-as-a-Service
- By Prescription Type
- NewRx
- Refill / Renewal
- Controlled Substances (EPCS)
- Specialty Drugs
- By End User
- Hospitals
- Clinics
- Pharmacies & Mail-order
- Telehealth Providers
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America dominated the electronic prescribing market with 38.11% share in 2025, sustained by mature network infrastructure and strong federal mandates. Surescripts routed 2.5 billion prescriptions on its U.S. platform that year, highlighting entrenched adoption. Persistent cybersecurity events such as the Change Healthcare breach and ongoing data-sharing challenges underscore the region's future investment needs, yet incentives embedded in Medicare and commercial insurance maintain growth momentum.
Asia-Pacific posted the fastest trajectory at 25.02% CAGR through 2031. Japan is rolling out a nationwide database that links every citizen's My Number ID to prescription histories, while China builds integrated treatment-insurance-pharmacy networks under its three-medical linkage policy. Governments in India, South Korea, and Australia are equally prioritizing national drug monitoring systems, creating leapfrog opportunities that let providers deploy cloud and mobile solutions without legacy constraints. A projected USD 138 billion healthcare outlay in China by 2027 offers substantial room for electronic prescribing market expansion.
Europe exhibits steady progress driven by Germany's e-Rezept program and the NHS mobile-app prescription service that now handles 3.1 million repeat requests monthly. Diverse regulatory environments across 27 EU states slow harmonization, but strict data-protection frameworks bolster consumer trust. South America along with the Middle East & Africa remain nascent but attractive; public-sector digitization drives early projects in Brazil, Saudi Arabia, and the United Arab Emirates. The global outlook therefore pairs mature usage in North America and Europe with rapid scale-up in Asia-Pacific and selective pilot adoption across emerging regions, sustaining long-term growth for the electronic prescribing market.
- Veradigm
- Surescripts
- Epic Systems
- Oracle
- DrFirst
- eClinicalWorks
- NextGen Healthcare
- Meditech
- Greenway Health
- Practice Fusion
- McKesson (CoverMyMeds)
- Omnicell
- RelayHealth (Change Healthcare)
- RxNT
- DoseSpot
- CompuGroup Medical (eMDs)
- WellSky
- Altera Digital Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Mandates for Electronic Prescription Adoption
- 4.2.2 Rising Focus on Medication Safety And Quality of Care
- 4.2.3 Need For Healthcare Cost Reduction and Operational Efficiency
- 4.2.4 Growing Penetration of Cloud-Based Healthcare IT Infrastructure
- 4.2.5 Expansion of Telehealth and Digital Pharmacy Ecosystems
- 4.2.6 Emerging Value-Based Care and Medication Price Transparency
- 4.3 Market Restraints
- 4.3.1 Data Privacy and Cybersecurity Concerns
- 4.3.2 Lack of Interoperability and Data Standardization
- 4.3.3 Provider Workflow Disruption and Usability Barriers
- 4.3.4 Limited Technical Expertise in Small and Rural Practices
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Type of System
- 5.2.1 Stand-alone Systems
- 5.2.2 Integrated EHR/HIS Systems
- 5.2.3 Mobile-first Apps
- 5.3 By Delivery Mode
- 5.3.1 Cloud-based
- 5.3.2 Web-based
- 5.3.3 On-premise
- 5.3.4 API Platform-as-a-Service
- 5.4 By Prescription Type
- 5.4.1 NewRx
- 5.4.2 Refill / Renewal
- 5.4.3 Controlled Substances (EPCS)
- 5.4.4 Specialty Drugs
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Clinics
- 5.5.3 Pharmacies & Mail-order
- 5.5.4 Telehealth Providers
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Veradigm LLC
- 6.3.2 Surescripts
- 6.3.3 Epic Systems Corporation
- 6.3.4 Oracle (Cerner)
- 6.3.5 DrFirst
- 6.3.6 eClinicalWorks
- 6.3.7 NextGen Healthcare
- 6.3.8 MEDITECH
- 6.3.9 Greenway Health
- 6.3.10 Practice Fusion
- 6.3.11 McKesson (CoverMyMeds)
- 6.3.12 Omnicell
- 6.3.13 RelayHealth (Change Healthcare)
- 6.3.14 RxNT
- 6.3.15 DoseSpot
- 6.3.16 CompuGroup Medical (eMDs)
- 6.3.17 WellSky
- 6.3.18 Altera Digital Health
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


