|
시장보고서
상품코드
2121466
문서 관리 시스템 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Document Management Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
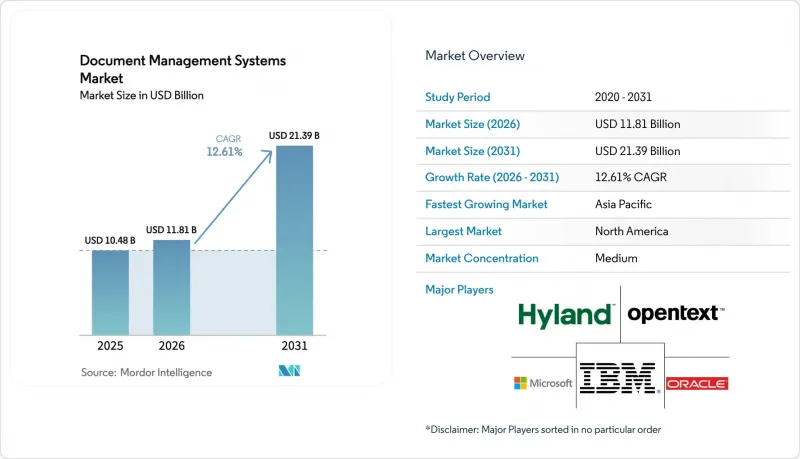
문서 관리 시스템 시장 규모는 2025년 104억 8,000만 달러, 2026년 118억 1,000만 달러에서 2031년까지 213억 9,000만 달러로 확대될 것으로 예측되고 있어 2026-2031년 CAGR 12.61%를 기록할 전망입니다.
본 보고서는 구성 요소(소프트웨어 및 서비스), 도입 형태(클라우드 및 On-Premise), 최종 사용자 산업(은행 및 금융 서비스, 제조 및 건설, 기타), 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 문서 관리 시스템 시장 동향 및 인사이트
종이 없는 환경으로의 급속한 전환
정부의 규제는 자발적인 지속가능성 노력보다 훨씬 빠른 속도로 디지털화를 가속화하고 있습니다. 미국 국립문서보관소는 모든 연방 기관에 2026년 12월까지 영구 보존 기록을 디지털화할 것을 요구하고 있습니다. 일본의 디지털청은 모든 도도부현에 2025년 4월까지 종이 없는 워크플로우를 도입하도록 지시했으며, 이로 인해 조달량이 35% 급증했습니다. 캐논은 2025년 자사의 클라우드 스캔 서비스를 통해 180억 페이지를 처리했으며, 이는 2024년 대비 22% 증가한 수치입니다. 이는 저장소로 유입되는 아날로그 컨텐츠의 급증 현상을 여실히 보여줍니다. 캡처량 증가는 스토리지 비용을 절감하지만, 메타데이터 태깅에 드는 노력을 가중시킵니다. 이러한 상충 관계로 인해 수동 인덱싱보다 AI를 활용한 자동 분류가 우선시되고 있습니다. 따라서 기업들은 규정 준수를 충족하면서도 운영 비용을 대폭 절감할 수 있는 머신러닝 강화 기능을 통합한 플랫폼을 우선적으로 선택하고 있습니다.
협업 제품군에 통합된 클라우드 네이티브 DMS 플랫폼
각 하이퍼스케일러 기업들은 현재 시간이 많이 소요되는 조달 프로세스를 생략하고, 협업 도구에 리포지토리를 직접 통합하고 있습니다. 마이크로소프트는 2024년 3월에 ‘SharePoint Embedded’를 출시했으며, 2025년 1월까지 200개 이상의 ISV가 이 서비스를 채택했습니다. Box는 2025년 6월에 Google Workspace와의 통합을 강화했으며, 시범 도입 기업에서는 버전 관리 오류가 40% 감소했습니다. 번들형 솔루션은 원활한 상호 운용성을 실현하기 위해 15-20%의 가격 프리미엄이 책정되어 있어, 이로 인해 DMS 전문 벤더들은 횡단적인 기능이 아닌 특정 산업 분야의 전문성으로 경쟁할 수밖에 없게 되었습니다.
규제 대상인 백오피스 업무에서 사용자들의 변화에 대한 뿌리 깊은 저항
딜로이트의 조사에 따르면, 금융 서비스 분야의 컴플라이언스 담당자 중 38%는 디지털 서명의 증거력에 의문을 품고 있으며, 여전히 제출 서류를 인쇄하여 수작업으로 검토하고 있는 것으로 나타났습니다. 공증인의 인증을 의무화하는 민법 관할 구역에서는 하이브리드 프로세스가 유지되고 있으며, 이로 인해 변경 관리 프로그램 기간이 2년으로 연장되고, 기업당 교육 예산이 50만-200만 달러로 불어나고 있습니다. 이러한 저항은 ROI 달성을 지연시키고, 클라우드 전환의 추진력을 약화시키고 있습니다.
부문 분석
마이그레이션의 복잡성, AI 튜닝, 규정 준수 대응 방안 수립이 사내 역량을 초과함에 따라 서비스 시장은 연평균 성장률(CAGR) 17.21%로 확대되고 있습니다. KnowledgeLake는 6주 만에 4억 5,000만 건의 연방 정부 문서를 SharePoint Online으로 마이그레이션하고, 그 과정에서 보존 정책을 즉시 재매핑했습니다. EY와 Adobe는 자문 서비스와 전자 서명 패키지를 결합하여 불과 12주 만에 바젤 III 준수 감사 추적을 제공합니다. 2025년 시점에서 소프트웨어 라이선스는 66.12%의 시장 점유율을 차지했습니다. 소프트웨어는 여전히 필수적이지만, 하이퍼스케일러에 의한 가격 압박으로 인해 라이선스 비용은 연간 10-15% 하락하고 있습니다.
구매자들이 턴키 방식의 성과를 요구하는 가운데, IBM, Hyland, OpenText 등 강력한 컨설팅 부서를 보유한 벤더들은 지속성이 높은 수익을 창출하고 있습니다. 마찬가지로, 24시간 IT 지원 체계를 갖추지 못한 중견 기업들에게는 매니지드 서비스가 매력적입니다. DocuWare의 클라우드 서비스는 백업과 패치 적용을 번들로 제공함으로써 총소유비용(TCO)을 30% 절감하고 있습니다. 그 결과, 문서 관리 시스템의 서비스 시장 규모는 라이선스 수익보다 빠르게 확대되고 있으며, 벤더의 비즈니스 모델을 재편하고 있습니다.
지역별 분석
북미는 미국 연방 정부의 디지털화 기한과 2027년 3월까지 모든 연방 부처가 클라우드 저장소로 이전하도록 요구하는 캐나다의 지침에 힘입어 2025년 매출의 37.53%를 차지했습니다. Microsoft 365의 높은 보급률이 도입을 가속화하고 있지만, 기업들이 플랫폼의 수명 주기를 연장하고 교체보다는 AI 애드온에 주력하고 있어 성장세는 완만해지고 있습니다.
아시아태평양은 2031년까지 연평균 18.43%의 성장률이 예상됩니다. 인도의 ‘디지털 인디아(Digital India)’ 프로그램은 2025-2026 회계연도 예산에서 전자정부(e-거버넌스)에 14,903 카롤 루피(18억 달러)를 배정했습니다. 중국의 ‘디지털 실크로드’는 국경을 넘는 무역 서류의 표준화를 도모하기 위해 국영 기업에 대한 도입에 자금을 지원하고 있습니다. 일본은 2025년 4월까지 ‘종이 없는 현’의 실현을 의무화했으며, 이로 인해 수주량이 35% 증가했습니다. 호주의 개정 개인정보보호법에서는 정보 유출 발생 후 72시간 이내에 통지할 의무가 부과되어, 이에 따라 조직들은 실시간 감사 추적을 도입해야 하는 상황에 처해 있습니다.
유럽, 중동 및 아프리카는 GDPR(EU 개인정보보호규정) 및 현지화 규정에 의해 형성된 조각보 같은 상황에 놓여 있습니다. EU의 데이터 거버넌스법은 벤더에게 지역별 데이터센터 운영을 의무화하고 있습니다. 독일의 사이버 보안 기관은 중요 인프라에 대해 On-Premise 또는 하이브리드형 도입을 권장하고 있습니다. 두바이 스마트 2030과 같은 걸프 국가들의 스마트 시티 프로그램에서는 전자정부 서비스에 리포지토리가 통합되어 있습니다. 남아프리카공화국의 POPIA는 은행 및 통신 사업자에게 동의에 기반한 관리가 이루어지는 아카이브 도입을 추진하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.02According to Mordor Intelligence, the document management systems market size is projected to expand from USD 10.48 billion in 2025 and USD 11.81 billion in 2026 to USD 21.39 billion by 2031, registering a CAGR of 12.61% between 2026 to 2031.
This report is Segmented by Component (Software, and Services), Deployment Mode (Cloud, and On-Premise), End-User Industry (Banking and Financial Services, Manufacturing and Construction, and More), and Geography (North America, South America, Europe, Asia Pacific, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Document Management Systems Market Trends and Insights
Rapid Shift Toward Paper-Free Processes
Government mandates are accelerating digital conversion far faster than voluntary sustainability initiatives. The U.S. National Archives requires every federal agency to digitize permanent records by December 2026. Japan's Digital Agency ordered all prefectures to adopt paperless workflows by April 2025, triggering a 35% jump in procurements. Canon processed 18 billion pages through its cloud-scanning service in 2025, up 22% from 2024, illustrating the flood of analog content entering repositories. Rising capture volumes trim storage costs but inflate metadata-tagging labor, a trade-off that favors AI-driven auto-classification over manual indexing. Enterprises therefore prioritize platforms with built-in machine-learning enrichers that satisfy compliance while slashing operating expense.
Cloud-Native DMS Platforms Bundled Inside Collaboration Suites
Hyperscalers now embed repositories directly in collaboration tools, bypassing lengthy procurement. Microsoft launched SharePoint Embedded in March 2024; by January 2025, more than 200 ISVs had adopted the service. Box deepened integration with Google Workspace in June 2025, and pilot clients recorded 40% fewer version-control errors. Bundled offerings command 15-20% price premiums because they deliver seamless interoperability, forcing pure-play vendors to compete on vertical depth rather than horizontal features.
Persistent User-Change Resistance in Regulated Back-Office Functions
Deloitte found that 38% of financial-services compliance staff still print filings for manual review, doubting the evidentiary strength of digital signatures. Civil-law jurisdictions that require notarized deeds maintain hybrid processes, prolonging change-management programs to two years and inflating training budgets to USD 0.5-2 million per enterprise. Resistance delays ROI and moderates cloud-migration momentum.
Other drivers and restraints analyzed in the detailed report include:
- Surge in AI-Enhanced Search and Auto-Classification Accuracy
- Strict Data-Sovereignty Rules Driving Compliant Roll-Outs
- High E-Discovery Costs From Poor Metadata Hygiene
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services are growing at a 17.21% CAGR because migration complexity, AI tuning, and compliance mapping outstrip in-house skills. KnowledgeLake migrated 450 million federal documents to SharePoint Online in six weeks, remapping retention policies on the fly. EY and Adobe deliver Basel III audit trails in only 12 weeks through a bundled advisory and e-signature package. Software licenses held a 66.12% market share in 2025. Software remains indispensable, yet license fees fall 10-15% annually under hyperscaler price pressure.
As buyers seek turnkey outcomes, vendors with strong consulting arms, such as IBM, Hyland, and OpenText, capture stickier revenue. Managed services likewise appeal to mid-market firms lacking 24-hour IT coverage; DocuWare's cloud service bundles backup and patching to cut the total cost of ownership by 30%. Consequently, the document management systems market size for services is expanding faster than license revenue and reshaping vendor business models.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Mode
- Cloud
- On-Premise
- By End-User Industry
- Banking and Financial Services
- Manufacturing and Construction
- Education
- Healthcare
- Retail
- Legal
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America delivered 37.53% of 2025 revenue, helped by U.S. federal digitization deadlines and a Canadian directive that all federal departments move to cloud repositories by March 2027. High Microsoft 365 penetration speeds deployment, yet growth moderates as enterprises stretch platform life cycles and focus on AI add-ons rather than replacements.
Asia Pacific will grow at 18.43% through 2031. India's Digital India program earmarked INR 14,903 crore (USD 1.8 billion) for e-governance in its 2025-2026 budget. China's Digital Silk Road funds state-enterprise deployments to standardize cross-border trade documents. Japan mandated paperless prefectures by April 2025, spurring a 35% order increase. Australia's amended Privacy Act requires breach notification within 72 hours, pushing organizations toward real-time audit trails.
Europe, the Middle East, and Africa form a patchwork shaped by GDPR and localization rules. The EU Data Governance Act obliges vendors to run regional data centers. Germany's cybersecurity agency advises on-premise or hybrid deployments for critical infrastructure. Gulf smart-city programs such as Dubai Smart 2030 embed repositories into e-government services. South Africa's POPIA drives banks and telecoms toward consent-managed archives.
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software Inc.
- Oracle Corporation
- Box Inc.
- Adobe Inc.
- Laserfiche
- M-Files Corp.
- Alfresco (Hyland)
- Dropbox Business
- Zoho Corporation
- DocStar (Epicor)
- AODocs
- LogicalDOC Srl
- Agiloft Inc.
- Synergis Technologies
- Everteam
- FileHold Systems
- PaperSave
- DocuWare GmbH
- Newgen Software Technologies
- Canon Inc.
- Xerox Holdings Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Shift Toward Paper-Free Processes
- 4.2.2 Cloud-Native DMS Platforms Bundled Inside Collaboration Suites
- 4.2.3 Surge in AI-Enhanced Search and Auto-Classification Accuracy
- 4.2.4 Strict Data-Sovereignty Rules Driving Compliant Roll-Outs
- 4.2.5 Rise of Industry-Specific Templates Shortening Deployment Cycles
- 4.2.6 Generative-AI Copilots Unlocking Content-in-Context Workflows
- 4.3 Market Restraints
- 4.3.1 Persistent User-Change Resistance in Regulated Back-Office Functions
- 4.3.2 High E-Discovery Costs From Poor Metadata Hygiene
- 4.3.3 Cyber-Insurance Premiums Rising After DMS-Centred Ransomware Events
- 4.3.4 Vendor Lock-In Concerns Slowing Migration From Legacy ECMs
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Pricing Analysis
- 4.9 Industry Ecosystem Analysis
- 4.10 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By End-User Industry
- 5.3.1 Banking and Financial Services
- 5.3.2 Manufacturing and Construction
- 5.3.3 Education
- 5.3.4 Healthcare
- 5.3.5 Retail
- 5.3.6 Legal
- 5.3.7 Other End-User Industries
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 South Korea
- 5.4.4.4 India
- 5.4.4.5 Australia
- 5.4.4.6 New Zealand
- 5.4.4.7 Rest of Asia Pacific
- 5.4.5 Middle East
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Kenya
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 OpenText Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Hyland Software Inc.
- 6.4.5 Oracle Corporation
- 6.4.6 Box Inc.
- 6.4.7 Adobe Inc.
- 6.4.8 Laserfiche
- 6.4.9 M-Files Corp.
- 6.4.10 Alfresco (Hyland)
- 6.4.11 Dropbox Business
- 6.4.12 Zoho Corporation
- 6.4.13 DocStar (Epicor)
- 6.4.14 AODocs
- 6.4.15 LogicalDOC Srl
- 6.4.16 Agiloft Inc.
- 6.4.17 Synergis Technologies
- 6.4.18 Everteam
- 6.4.19 FileHold Systems
- 6.4.20 PaperSave
- 6.4.21 DocuWare GmbH
- 6.4.22 Newgen Software Technologies
- 6.4.23 Canon Inc.
- 6.4.24 Xerox Holdings Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment