

|
시장보고서
상품코드
2121509
스마트 마이닝 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Smart Mining - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
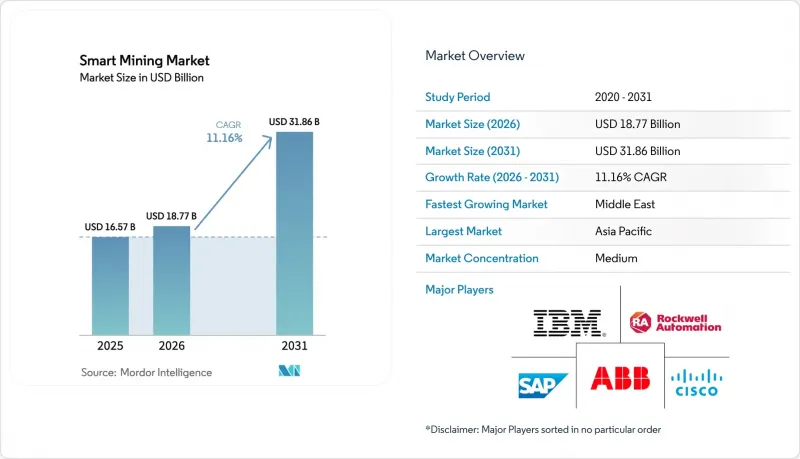
에 의하면, 스마트 마이닝 시장 규모는 2025년에 165억 7,000만 달러, 2026년에 187억 7,000만 달러에 이르고, 2031년까지 318억 6,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 11.16%를 기록할 전망입니다.
본 보고서는 솔루션별(스마트 제어 시스템, 스마트 자산 관리 등), 서비스 유형별(시스템 통합, 컨설팅 서비스, 엔지니어링 및 유지보수, 매니지드 서비스), 채굴 방식별(지하 채굴, 노천 채굴), 기술별(사물인터넷(IoT), 로봇공학 및 자동화 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 스마트 마이닝 시장 동향 및 인사이트력
자율 주행 운반 차량의 도입
차량 군 단위의 무인 트럭 도입으로 교대 근무에 따른 가동 중단 시간이 해소되고, 지리 공간 원격 측정 데이터가 광산 계획 알고리즘에 반영됨으로써 채굴 전략이 실시간으로 최적화됩니다. 리오 틴토(Rio Tinto)는 2025년 필바라(Pilbara) 지역에서 360대 이상의 자율 주행 운반 트럭을 운영하여, 유인 차량에 비해 디젤 1리터당 톤킬로미터를 15% 향상시켰습니다. 코마츠의 ‘FrontRunner’ 플랫폼은 현재 네바다 골드 마인즈(Nevada Gold Mines)에서 혼합 차량 군을 관리하고 있으며, 수동 조작으로는 유지할 수 없는 24시간 가동률을 목표로 하고 있습니다. 400톤 트럭의 개조 비용은 50만-80만 달러가 소요되기 때문에 인건비가 저렴한 지역의 광산 기업들은 상품 가격이 안정될 때까지 구매를 미루고 있습니다. 라틴아메리카나 아프리카에서는 승인 절차가 세분화되어 있어 가동 시작까지 최대 12개월이 지연될 수도 있지만, 조기에 도입한 사업자는 동종 업계 경쟁사 대비 두 자릿수의 생산성 향상을 실현하고 있습니다.
IoT·AI를 활용한 예측 유지보수
센서 네트워크와 엣지 분석 엔진을 통해 예기치 못한 가동 중단 시간이 계획된 작업 기간으로 전환되어, 처리 능력과 예비 부품 예산을 확보할 수 있습니다. 47개 광산에 도입된 ABB의 ‘Ability’ 플랫폼은 베어링 고장을 몇 주 전에 예측하는 진동 및 오일 품질 모니터링을 통해 유지보수 비용을 12% 절감하고 종합 설비 효율(OEE)을 9% 향상시켰습니다. SAP는 자사의 ‘Asset Intelligence Network’를 딜로이트의 모델과 연계하여 칠레의 구리 광산에서 컨베이어의 긴급 수리를 18% 줄였습니다. 산업용 가속도계의 가격은 2020년 120달러에서 2025년에는 35달러로 하락하여, 도입 대상 설비의 범위가 확대되고 있습니다. 기존의 감시 제어 및 데이터 수집(SCADA) 시스템은 여전히 플러그 앤 플레이형 센서를 지원하지 않으며, 최상위 기업을 제외한 곳에서는 데이터 사이언스 역량이 여전히 부족한 실정입니다.
높은 설비 투자(CAPEX)와 ROI의 불확실성
대규모 스마트 마이닝 도입에는 대개 5,000만 미달러 이상의 비용이 소요되며, 상품 가격의 변동이 심하기 때문에 구리, 금, 철광석 생산 업체의 경우 투자 회수 기간이 4년 이상 걸릴 수도 있습니다. 맥킨지의 2024년 조사에 따르면, 경영진의 38%가 특히 현지 통화가 달러로 표시된 설비 대출 대비 가치가 하락한 경우, 수익성이 불확실하다는 이유로 프로젝트를 연기하고 있다고 응답했습니다. 아프리카와 동남아시아의 중소 광산 기업들은 무형 자산에 대한 은행 대출 확보에 어려움을 겪고 있으며, 대신 금리가 높은 벤더 리스에 의존하고 있습니다. 탄소 가격 제도를 둘러싼 규제 불확실성은 내부 평가를 불투명하게 만들고 있습니다. 이는 자율 주행 운송 및 에너지 최적화를 통해 달성된 배출 감축을 광산 기업이 아직 수익화할 수 없기 때문입니다.
부문별 분석
제어 시스템은 2025년 매출의 39.87%를 차지하며, 노천 채굴 및 지하 광산 전체의 환기, 전력 배분, 공정 루프를 총괄하는 중추 지휘층으로서의 역할을 반영하고 있습니다. 제어 시스템에 기인한 스마트 마이닝 시장 규모는 2025년에 70억 달러를 넘어설 것으로 예상되며, 이는 이 부문의 확고한 입지를 뒷받침합니다. 사업자들은 에너지 부하, 컨베이어 성능, 가스 농도에 대한 실시간 가시성을 중시하고 있으며, 이 모든 것은 현재 디지털 트윈을 통합한 SCADA 프레임워크를 통해 제공되고 있습니다. 오픈 플랫폼 아키텍처의 부상으로 광산 사업자는 대규모 시스템 개편 없이도 분석 및 가시화 모듈을 추가할 수 있게 되어, 자본을 절약하면서 점진적인 현대화가 가능해졌습니다.
자율 주행을 통한 운반 및 굴착은 가장 빠르게 성장하는 솔루션 카테고리이며, 2031년까지 연평균 성장률(CAGR) 12.57%로 성장할 전망입니다. 운반 톤당 15-20%의 생산성 향상은 물론, 타이어 마모 감소 및 연료 소비량 절감이 그 경제적 타당성을 뒷받침하고 있습니다. 리오 틴토, BHP, 포트 에스크 메탈스 그룹은 2025년에 각각 90대 이상의 자율 주행 트럭을 도입하여 스마트 마이닝 시장을 완전 무인 차량 군으로 이끌었습니다. 안전 및 보안 시스템, 특히 LiDAR 기반 충돌 회피 시스템의 경우, 2024년 미국 광산 안전 보건국(MSHA)이 근접 감지 관련 규제를 강화함에 따라 수요가 급증했습니다. 데이터 관리 소프트웨어는 트럭, 드릴, 분쇄기에서 얻어지는 페타바이트 규모의 텔레메트리 데이터를 실행 가능한 인사이트력으로 변환하고, 스트립비 개선 및 분쇄기 초크 설정 최적화를 실현함으로써 솔루션군을 완성하고 있습니다.
각 광산 기업은 독자적인 장비 프로토콜과 클라우드 네이티브 분석 기법을 이해하는 전문가에 의존하고 있기 때문에 2025년 서비스 수익 중 47.63%를 시스템 통합이 차지했습니다. 이러한 통합업체들의 스마트 마이닝 시장 점유율은 하드웨어, 소프트웨어 및 변경 관리를 다년 계약 하에 일괄 제공하기 때문에 여전히 높은 수준을 유지하고 있습니다. 한편, 매니지드 서비스는 24시간 365일 모니터링 및 사이버 보안에 대한 책임을 인증된 제어 센터를 보유한 벤더에 위탁하려는 광산 기업 수요에 힘입어 연평균 성장률(CAGR) 11.93%로 확대되고 있습니다. 액센츄어는 이러한 수요에 부응하기 위해 2024년에 광업용 매니지드 서비스 직원 수를 22% 증원했습니다.
컨설팅은 미래를 대비한 네트워크 설계가 필수적인 그린필드 프로젝트에서 여전히 핵심적인 위치를 차지하고 있지만, ‘서비스형(as-a-service)’ 모델에 따라 수익원은 일시적인 엔지니어링 업무에서 지속적인 지원으로 전환되고 있습니다. 유지보수 서비스 분야에서는 일정 기반의 스케줄에서 벗어나, 차량군의 텔레메트리 데이터에서 도출된 예측 모델이 도입되고 있습니다. 이러한 서비스 전반이 사내에 디지털 팀을 보유하지 않은 중견 기업의 진입 장벽을 낮춤으로써 스마트 마이닝 시장을 혁신하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 35.24%를 차지하고 있으며, 이를 주도하는 요인은 연간 생산 능력 120만 톤 이상의 석탄 광산에 대해 2024년 말까지 스마트 광산 시스템 도입을 의무화한 중국의 정책입니다. 호주의 필바라 철광석 클러스터는 여전히 ‘리빙 랩(Living Lab)’으로서의 역할을 수행하고 있으며, 주 정부의 830만 달러 공동 출자가 중견 광산 사업자들의 자율 운송 시범 사업을 촉진하고 있습니다. 또한 이 지역에는 리튬과 희토류 광상이 집중되어 있어, 배터리 기가팩토리로공급을 확보하기 위한 대규모 디지털 투자를 유치하고 있습니다.
북미에서는 광산 사업자가 간섭 위험 없이 LTE 및 5G를 도입할 수 있도록 견고한 전용 주파수 대역 규제가 마련되어 있습니다. 뉴몬트(Newmont)사의 페나스키트(Penaskit) 광산에서는 2024년에 전용 LTE가 도입되어 120대의 연결 기기를 지원함으로써 드릴과 굴삭기의 원격 문제 해결이 가능해졌습니다. 엣지 AI 칩과 배출량 추적 대시보드를 개발하는 스타트업에는 벤처 캐피탈이 유입되고 있어 기술 공급망이 확대되고 있습니다.
유럽의 성장은 석탄 산업의 쇠퇴와 신규 광산 허가 취득이 사회적 저항에 직면하고 있어 완만합니다. 그러나 스칸디나비아의 광산 운영사는 탄소 중립 목표를 달성하기 위해 배터리 구동 자율 주행 트럭을 선도적으로 도입하며, 틈새 기술 분야에서의 리더십 역할을 보여주고 있습니다. 남미에는 고품위 구리 및 리튬 광상이 있으며, 코델코(Codelco)는 2024년 추키카마타(Chuquicamata) 지하 광산에 자율 운반 시스템을 도입하여 디젤 연료 소비량을 12% 절감했습니다. 중동 및 아프리카의 일부 시장은 빠르게 성숙하고 있습니다. 사우디아라비아의 마아덴(Ma'aden)은 2024년, 컨베이어와 분쇄기를 최적화하여 에너지 효율을 15% 향상시키기 위해 지멘스(Siemens)에 4,700만 달러 규모의 자동화 계약을 발주했습니다. 중동은 가장 빠르게 성장하는 지역으로, 2031년까지 연평균 성장률(CAGR)이 12.19%에 달할 전망입니다. 이는 정부 계열 펀드의 자금 지원과 수백 킬로미터 떨어진 현장을 관리하는 원격 운영 센터에 의해 뒷받침되고 있습니다. 아프리카에서는 송전망의 신뢰성이나 프로젝트 자금 조달의 제약으로 여전히 어려움을 겪고 있지만, 남아프리카의 백금 광산에서는 개정된 안전 규정을 준수하기 위해 수요에 대응하는 환기 시스템 도입이 진행되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the smart mining market size is projected to be USD 16.57 billion in 2025, USD 18.77 billion in 2026, and reach USD 31.86 billion by 2031, growing at a CAGR of 11.16% from 2026 to 2031.
This report is Segmented by Solution (Smart Control Systems, Smart Asset Management, and More), Service Type (System Integration, Consulting Services, Engineering and Maintenance, Managed Services), Mining Type (Underground Mining, and Surface (Open-Pit) Mining), Technology (Internet of Things (IoT), Robotics and Automation, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Mining Market Trends and Insights
Autonomous Haulage Adoption
Fleet-scale driverless trucks eliminate shift change downtime and feed geospatial telemetry into mine-planning algorithms that refine pit strategy in real time. Rio Tinto operated more than 360 autonomous haul trucks in the Pilbara during 2025 and lifted tonne-kilometers per liter of diesel by 15% compared with crewed fleets. Komatsu's FrontRunner platform now manages mixed fleets at Nevada Gold Mines, targeting around-the-clock utilization rates that manual operations cannot sustain. Retrofitting a 400-ton truck costs USD 500,000-800,000, so miners in low-labor-cost jurisdictions defer purchases until commodity prices stabilize. Fragmented approval processes in Latin America and Africa extend commissioning by up to 12 months, yet operators that move early secure double-digit production gains over peers.
IoT-AI Predictive Maintenance
Sensor networks and edge analytics engines shift unplanned downtime into scheduled work windows, protecting throughput and spare parts budgets. ABB's Ability platform at 47 mines cut maintenance expense by 12% and raised overall equipment effectiveness by 9% through vibration and oil-quality monitoring that predicts bearing failures weeks in advance. SAP linked its Asset Intelligence Network with Deloitte models to reduce emergency conveyor repairs by 18% at a Chilean copper site. Industrial accelerometer prices fell from USD 120 in 2020 to USD 35 in 2025, expanding addressable fleets. Legacy supervisory control and data-acquisition systems still resist plug-and-play sensors, and data-science capability remains scarce outside top-tier companies.
High CAPEX and ROI Uncertainty
Large smart-mining rollouts often top USD 50 million, and volatile commodity cycles stretch payback periods to more than 4 years for copper, gold, and iron-ore producers. McKinsey's 2024 survey found that 38% of executives are delaying projects due to unclear returns, especially when local currencies depreciate against USD-linked equipment financing. Smaller African and Southeast Asian miners struggle to secure bank credit for intangible assets, relying instead on vendor leasing, which carries higher interest rates. Regulatory uncertainty surrounding carbon-pricing schemes clouds internal valuations because miners cannot yet monetize emissions cuts achieved by autonomous haulage and energy optimization.
Other drivers and restraints analyzed in the detailed report include:
- Private 5G Roll-Outs
- Surge in Critical-Mineral Demand
- Cyber-Security Vulnerabilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Control systems captured 39.87% of 2025 revenue, reflecting their role as the central command layer that orchestrates ventilation, power distribution, and process loops across open-pit and underground sites. The smart mining market size attributed to control systems surpassed USD 7 billion in 2025, confirming the segment's entrenched status. Operators value real-time visibility into energy load, conveyor performance, and gas levels, all delivered through SCADA frameworks that now integrate digital twins. The rise of open-platform architectures lets miners bolt on analytics and visualization modules without forklift upgrades, preserving capital and enabling incremental modernization.
Autonomous haulage and drilling is the fastest-growing solution category, advancing at a 12.57% CAGR through 2031. Productivity gains of 15-20% per tonne hauled, along with reduced tire wear and lower fuel burn, underpin the economic case. Rio Tinto, BHP, and Fortescue Metals Group each deployed 90-plus autonomous trucks in 2025, pulling the smart mining market toward fully crewless fleets. Safety and security systems, particularly LiDAR-based collision-avoidance systems, saw a surge in demand after the United States Mine Safety and Health Administration tightened proximity-detection mandates in 2024. Data-management software rounds out the stack by turning petabytes of truck, drill, and crusher telemetry into actionable insights that improve strip ratios and optimize crusher choke settings.
System integration accounted for 47.63% of 2025 service revenue, as miners depend on specialists who understand proprietary equipment protocols and cloud-native analytics. Smart mining market share for these integrators remains high because they bundle hardware, software, and change management under multi-year contracts. Managed services, however, are advancing at an 11.93% CAGR, fueled by miners that offload 24/7 monitoring and cyber-security liability to vendors with certified control centers. Accenture expanded its mining managed-services headcount by 22% in 2024 to meet this demand.
Consulting retains a core position for greenfield projects that must blueprint future-proof networks, yet as-a-service models shift revenue from one-time engineering to recurring support. Maintenance services adopt predictive models derived from fleet telemetry, moving away from calendar-based schedules. Collectively, services transform the smart mining market by lowering entry barriers for mid-tier operators that lack in-house digital teams.
Complete Report Scope:
- By Solution
- Smart Control Systems
- Smart Asset Management
- Safety and Security Systems
- Data Management and Analytics Software
- Monitoring and Visualization
- Autonomous Haulage and Drilling
- Other Solutions
- By Service Type
- System Integration
- Consulting Services
- Engineering and Maintenance
- Managed Services
- By Mining Type
- Underground Mining
- Surface (Open-Pit) Mining
- By Technology
- Internet of Things (IoT)
- Artificial Intelligence and Analytics
- Robotics and Automation
- Connectivity (5G/LTE)
- Cloud and Edge Computing
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia Pacific commanded 35.24% of 2025 revenue, led by China's mandate that coal mines above 1.2 million-ton annual capacity install smart-mine systems by the end of 2024. Australia's Pilbara iron-ore cluster remains a living lab, with state co-funding of USD 8.3 million catalyzing autonomous-haulage pilots across mid-tier operations. The region also benefits from concentrated lithium and rare-earth deposits that attract significant digital investment to secure supply for battery gigafactories.
North America follows with robust private-spectrum rules that let miners deploy LTE and 5G without interference risk. Newmont's Penasquito site integrated private LTE in 2024, supporting 120 connected devices that enabled remote troubleshooting of drills and shovels. Venture capital is flowing into start-ups developing edge AI chips and emissions-tracking dashboards, widening the technology supply chain.
Europe's growth is slower because coal declines and greenfield mine permitting faces social resistance. Scandinavian operators, however, are pioneering battery-electric autonomous trucks to meet carbon-neutrality goals, signaling a niche tech leadership role. South America hosts high-grade copper and lithium belts; Codelco installed autonomous haulage at Chuquicamata underground in 2024 to cut diesel burn by 12%. Select Middle East and Africa markets mature quickly. Saudi Arabia's Ma'aden awarded a USD 47 million automation contract to Siemens in 2024 to optimize conveyors and crushers for a 15% energy-efficiency gain. The Middle East is the fastest-growing region, with a 12.19% CAGR through 2031, buoyed by sovereign wealth funding and remote operations centers that manage sites hundreds of kilometers away. Africa continues to struggle with grid reliability and limited project finance, yet South African platinum mines are installing ventilation-on-demand systems to comply with revised safety laws.
- ABB Ltd
- Caterpillar Inc.
- Cisco Systems Inc.
- Komatsu Ltd
- Epiroc AB
- Hexagon AB
- Sandvik AB
- Rockwell Automation Inc.
- SAP SE
- Trimble Inc.
- IBM Corporation
- Wenco International Mining Systems Ltd
- Symboticware Inc.
- Metso Outotec Oyj
- Siemens AG
- Hitachi Construction Machinery Co., Ltd.
- Honeywell International Inc.
- Schneider Electric SE
- Accenture plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Autonomous Haulage Adoption
- 4.2.2 IoT-AI Predictive Maintenance
- 4.2.3 Safety-Driven Monitoring Demand
- 4.2.4 Private 5G Roll-Outs
- 4.2.5 Sustainability-Linked Financing Incentives
- 4.2.6 Surge in Critical-Mineral Demand
- 4.3 Market Restraints
- 4.3.1 High CAPEX and ROI Uncertainty
- 4.3.2 Legacy-System Integration Gaps
- 4.3.3 Cyber-Security Vulnerabilities
- 4.3.4 Skilled Digital-Talent Shortage
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Rivalry
- 4.7.5 Threat of Substitutes
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 Smart Control Systems
- 5.1.2 Smart Asset Management
- 5.1.3 Safety and Security Systems
- 5.1.4 Data Management and Analytics Software
- 5.1.5 Monitoring and Visualization
- 5.1.6 Autonomous Haulage and Drilling
- 5.1.7 Other Solutions
- 5.2 By Service Type
- 5.2.1 System Integration
- 5.2.2 Consulting Services
- 5.2.3 Engineering and Maintenance
- 5.2.4 Managed Services
- 5.3 By Mining Type
- 5.3.1 Underground Mining
- 5.3.2 Surface (Open-Pit) Mining
- 5.4 By Technology
- 5.4.1 Internet of Things (IoT)
- 5.4.2 Artificial Intelligence and Analytics
- 5.4.3 Robotics and Automation
- 5.4.4 Connectivity (5G/LTE)
- 5.4.5 Cloud and Edge Computing
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)}
- 6.4.1 ABB Ltd
- 6.4.2 Caterpillar Inc.
- 6.4.3 Cisco Systems Inc.
- 6.4.4 Komatsu Ltd
- 6.4.5 Epiroc AB
- 6.4.6 Hexagon AB
- 6.4.7 Sandvik AB
- 6.4.8 Rockwell Automation Inc.
- 6.4.9 SAP SE
- 6.4.10 Trimble Inc.
- 6.4.11 IBM Corporation
- 6.4.12 Wenco International Mining Systems Ltd
- 6.4.13 Symboticware Inc.
- 6.4.14 Metso Outotec Oyj
- 6.4.15 Siemens AG
- 6.4.16 Hitachi Construction Machinery Co., Ltd.
- 6.4.17 Honeywell International Inc.
- 6.4.18 Schneider Electric SE
- 6.4.19 Accenture plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


