|
시장보고서
상품코드
2121530
자동차 레인 센서 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Automotive Rain Sensor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
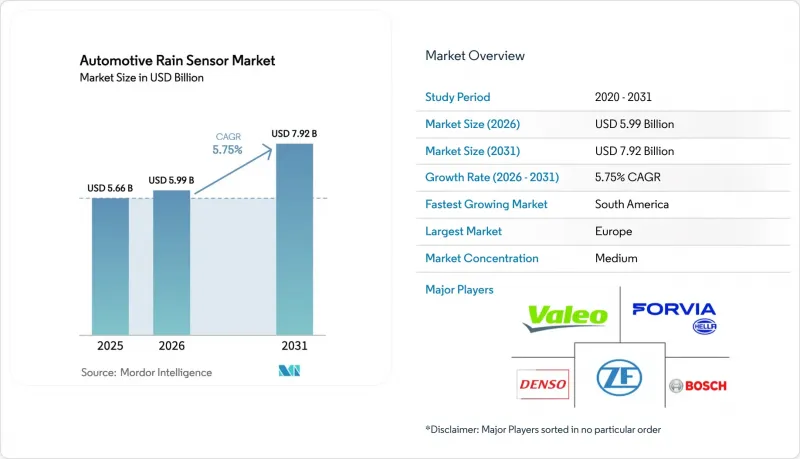
에 의하면, 자동차 레인 센서(빗방울 감지 센서) 시장 규모는 2025년 56억 6,000만 달러에서 2026년에는 59억 9,000만 달러로 성장하고, 2026-2031년 CAGR 5.75%로 성장을 지속하여 2031년에는 79억 2,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 차종(승용차(해치백, 세단 등), 상용차(소형 상용차(LCV) 등)),기술(광학식(CCD/CMOS) 등), 판매 채널(OEM 탑재, 애프터마켓용 개조), 용도(ADAS 센서 퓨전 모듈 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
전 세계 자동차용 레인 센서 시장 동향 및 인사이트
ADAS의 보급 확대에 따라 다기능 환경 감지가 필수적입니다.
레벨 2+ 및 레벨 3 지각 스택에서는 카메라 렌즈나 LiDAR 창을 깨끗하게 유지하기 위해 빗방울, 빛, 안개에 관한 정확한 데이터가 필요하며, 이에 따라 센서는 단순한 편의성을 위한 부가 기능에서 안전성을 뒷받침하는 핵심 요소로 그 역할이 재정의되고 있습니다. 유럽의 OEM 프로그램에서는 하네스의 경량화와 진단 기능 통합을 도모하기 위해 광학식 레인 센서와 습도·광 센서를 단일 PCB 위에 통합하고 있습니다. 중국의 자동차 제조업체들은 향후 도입될 NCAP의 시인성 평가 기준을 충족하기 위해 이 아키텍처를 채택하고 있는 반면, 북미의 트럭 제조업체들은 자동 긴급 제동 시스템의 작동 시간을 연장하기 위해 전방 시야 클러스터에 비 감지 기능을 통합하고 있습니다. 고해상도 CCD 어레이는 물방울 분류 정확도를 향상시키고, 그 데이터를 융합 소프트웨어에 공급함으로써 와이퍼 속도, 어댑티브 헤드라이트 및 디포거의 제어 로직을 단일 제어 루프 내에서 조정합니다. 그 결과, 조달 팀은 현재 와이퍼의 응답 지연뿐만 아니라 레이더와 카메라의 연동을 통한 지표를 기준으로 성능을 평가하게 되었으며, 멀티 센서의 채택은 1차 공급업체의 수익원에 있어 매우 중요해졌습니다.
전동화와 차량용 고전압 아키텍처가 도입을 가속화
400V 및 800V에서 작동하는 E 플랫폼은 신호 처리용 ASIC 및 레이저 트림 처리된 VCSEL 이미터에 안정적인 전력 여유를 제공하며, 이들은 고습도 과도 상태에서 12V 동급 제품을 능가하는 성능을 발휘합니다. 중앙 집중형 컴퓨팅 도메인은 보안이 강화된 CAN-FD 링크를 통해 원시 물방울 벡터를 존 컨트롤러로 전송하며, 여기서 머신 러닝 모델이 와이퍼 작동 타이밍을 최적화함으로써 와이퍼 블레이드의 수명을 연장하고 HVAC 부하를 줄입니다. 무선 펌웨어 릴리스를 통해 OEM 업체들은 감지 임계값을 반복적으로 최적화할 수 있으며, 예측 유지보수 알림과 연동된 종량제 수익 모델을 구현할 수 있습니다. 따라서 배터리식 전기차 브랜드들은 레인 센서를 단순한 수동적인 유리용 액세서리가 아닌 에너지 관리 자산으로 간주하여, 앞유리 김서림 제거 주기를 최대 6%까지 줄이고 있습니다.
엔트리 레벨 A/B 부문 차량의 높은 가격 민감도
인도, 아세안 일부 지역 및 라틴아메리카의 비용 중심 플랫폼에서는 계기판의 전체 전자 기기 스택에 할당되는 예산이 75달러 미만이며, 25-30달러 상당의 빗방울 감지 모듈을 도입할 여력은 극히 적습니다. 인도의 국내 조달 규정에 따라 현지에서 생산되지 않는 PCBA에 대한 수입 관세가 인상되어 1차 공급업체의 수익성이 압박을 받고 있으며, 채택률이 둔화되고 있습니다. OEM 업체들은 통합형 MEMS의 가격이 15달러 미만으로 떨어질 때까지 전장 4미터 미만의 차량에 수동식 가변 간헐 와이퍼를 계속 채택하고 있습니다. 현지에서 유리 본딩에 관한 제휴 관계를 구축한 공급업체는 운송비 할증료를 절감할 수 있지만, 현재 소량 주문이 이러한 설비 투자를 저해하고 있습니다.
부문 분석
승용차용 레인 센서 시장 규모는 2025년에 시장 점유율의 70.88%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 6.30%라는 견조한 성장세로 시장을 주도할 것으로 전망됩니다. 세단 모델의 경우 등급에 관계없이 일관된 탑재율이 유지되고 있지만, 해치백 모델에서는 여전히 고가 등급으로 한정되어 있습니다. 경상용 밴 차량의 경우, 운전자의 주의 산만과 보험금 청구를 최소화하기 위해 자동 와이퍼가 사양으로 채택되고 있지만, 중형 트럭에서는 사후 장착의 복잡성으로 인해 도입이 지연되고 있습니다. 수요 동향을 살펴보면, SUV의 구성비가 10포인트 상승할 때마다 시스템 평균 부품 원가(BOM) 상한이 4달러 상승하여, 1차 공급업체의 이익률 유지에 기여하고 있습니다. 예측 기간 동안, SUV의 전면 유리 면적이 넓어 정전용량식 어레이에서 물방울 노이즈가 증가함에 따라, 각 OEM 업체들은 폭우 시에도 ±2ml의 감도 정밀도를 유지할 수 있는 광학식 아키텍처를 계속해서 채택할 전망입니다.
승용차의 모델 체인지 주기는 교체 주기가 빠른 소형 상용차 플릿에 비해 판매 대수 증가폭은 완만하지만, 더 안정적입니다. 텔레매틱스 도입을 검토 중인 차량 운영 사업자들에 따르면, 예측 와이퍼 제어 기능이 활성화되면 전면 유리 수리 청구 건수가 7% 감소한다는 보고가 있어, 비즈니스 케이스의 타당성이 입증되고 있습니다. 전반적으로 SUV의 보급으로 인해 자동차용 레인 센서 시장은 기능이 풍부한 패키지에 편중된 상태가 지속되고 있으며, 대량 생산되는 해치백 차량의 낮은 이익률과 균형을 이루고 있습니다.
광학식 CCD/CMOS 디바이스는 검증된 우수한 신호 대 잡음비 덕분에 2025년 매출의 81.10%를 차지했습니다. 상위 5개사의 광학식 컨트롤러 ASIC은 이미 실리콘 리비전 B 단계에 도달했으며, 비용 곡선이 횡보하고 있어 MEMS 진출기업들에게는 가격 대비 성능 면에서 진입의 여지가 생기고 있습니다. 정전용량식/MEMS 기반 디바이스는 유리 접합 허용 오차 문제를 피할 수 있어 연평균 성장률(CAGR) 8.25%를 기록할 전망이며, 고도의 자외선 차단 기능을 갖춘 적층 전면 유리를 채택한 차량에 최적입니다. 적외선 반사형 하이브리드 센서는 -25°C 이하에서 결빙 방지 성능이 요구되는 틈새 시장을 확보하고 있지만, 단위당 비용은 높습니다.
전략 로드맵에 따르면, MEMS 공급업체들은 공통 다이 공간에 환경광 센서와 적외선 근접 센서를 통합하여 PCB 실적를 35% 줄이고 있습니다. 한편, 광학계 주요 제조업체는 AI 엣지 추론 코어를 통합하여 생산량을 확보하고, 자가 보정 기능을 갖춘 물방울 인식을 실현함으로써 사양 면에서의 우위를 유지하고 있습니다. 향후 전망은 대체가 아닌 공존이 특징이 될 것입니다. 광학 시스템은 프리미엄 시장 및 가혹한 사용 환경을 위한 틈새 시장을 유지하고, MEMS는 보급을 추진해 나갈 것입니다.
지역별 분석
유럽의 37.55%라는 점유율은 엄격한 UNECE 가시성 기준과 비·빛·습도 융합 기술에 대해 2점의 안전 점수를 부여하는 2025년 NCAP 평가를 반영한 것으로, B부문 해치백 이상 차량에서 센서 탑재가 당연한 사양으로 자리 잡았습니다. 또한, 이 대륙에서 확립된 프리미엄 차종의 구성으로 인해, 높은 이익률을 자랑하는 광학식 어레이가 시장을 독점하고 있습니다. 브라질 상파울루에 위치한 대량 생산 OEM 거점이 주도하는 남미는 연평균 성장률(CAGR) 9.85%로 가장 빠르게 성장하고 있습니다. 엔트리 모델에서 소형 SUV로 소비자의 차량 전환이 이루어짐에 따라 자동 와이퍼의 부품 명세서(BOM)에 여유가 생기고 있으며, 전자 부품의 현지 생산을 촉진하는 연방 정부의 인센티브가 마나우스 근교에서의 센서 하우징 성형 사업 출범을 뒷받침하고 있습니다.
아시아태평양에서는 다소 미묘한 동향이 관찰됩니다. 중국의 신차 평가 프로그램에서는 2027년부터 자동 시야 관리 기능에 평가 점수가 부여될 예정이며, 이미 연간 2,500만 대 규모에 달한 제조 거점에서 안정적인 출하가 확보될 전망입니다. 인도 및 아세안(ASEAN) 일부 지역에서는 수입 전자 부품에 대한 과세가 비용을 상승시키는 장벽으로 작용하고 있습니다. 그럼에도 불구하고 전기차(EV) 보급 확대 추세에 따라 레인 센서의 중요성이 재조명되고 있습니다. 태국이나 인도네시아로 수출되는 1만 5,000달러 미만의 중국산 마이크로 전기차에는 우측 핸들 사양에 쉽게 적용할 수 있도록 기본적인 정전용량식 센서가 탑재되어 있습니다. 따라서 아시아태평양은 여전히 최대의 성장 동력인 동시에 가장 세분화된 경쟁의 장이기도 합니다. 북미에서의 보급 속도는 눈부시다기보다는 꾸준한 편이지만, 평균 거래 가격이 높기 때문에 주류인 픽업 트럭이나 SUV에 복잡한 센서 퓨전 패키지를 탑재하는 것이 가능해졌습니다. OTA(Over-the-Air) 업데이트 문화는 전면 유리의 예측 유지보수를 위한 구독 모델의 토대가 되어, 하드웨어의 상품화를 완화하는 지속적인 수익을 창출하고 있습니다.
기타 혜택:
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모·성장률 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.02According to Mordor Intelligence, the automotive rain sensor market size is expected to grow from USD 5.66 billion in 2025 to USD 5.99 billion in 2026 and is forecast to reach USD 7.92 billion by 2031 at 5.75% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Passenger Cars [Hatchback, Sedan, and More] and Commercial Vehicles (Light Commercial Vehicle (LCV) and More)), Technology (Optical (CCD/CMOS) and More), Sales Channel (OEM-Installed and Aftermarket Retrofit), Application (ADAS Sensor Fusion Modules, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Rain Sensor Market Trends and Insights
Rising ADAS Penetration Mandates Multi-Function Environmental Sensing
Level 2+ and Level 3 perception stacks require precise raindrop, light, and fog data to keep camera lenses and LiDAR windows clear, recasting the sensor from a comfort extra into a core safety enabler. European OEM programs pair optical rain sensors with humidity and light channels on a single PCB for reduced harness weight and unified diagnostics. Chinese brands replicate the architecture to meet forthcoming NCAP visibility scoring, while North American truck makers embed rain detection in forward-vision clusters to extend automatic emergency braking uptime. High-resolution CCD arrays improve droplet classification, feeding fusion software that modulates wiper speed, adaptive headlights, and defogger logic in one control loop. Consequently, procurement teams now benchmark performance against radar-camera synergy metrics rather than wiper latency alone, making multi-sensor wins pivotal to Tier 1 revenue pipelines.
Electrification & Higher Onboard Voltage Architectures Accelerate Adoption
E-platforms working at 400 V and 800 V offer stable power headroom for signal-processing ASICs and laser-trimmed VCSEL emitters that outperform 12 V counterparts under high-humidity transients. Centralized compute domains pull raw droplet vectors over secure CAN-FD links into zone controllers where machine-learning models refine wipe timing, extending blade life, and trimming HVAC load. Over-the-air firmware releases let OEMs iteratively sharpen detection thresholds, opening pay-per-use revenue tiers tied to predictive maintenance alerts. Battery-electric brands, therefore, market rain sensors as energy-management assets, reducing window-defog cycles by up to 6%, rather than passive glass accessories.
High Price Sensitivity in Entry-Level A/B-Segment Cars
Cost-led platforms in India, parts of ASEAN, and Latin America allocate less than USD 75 for the entire instrument-panel electronics stack, leaving marginal headroom for a USD 25-30 rain-sensing module. Domestic content rules in India amplify import tariffs on unlocalized PCBAs, compressing Tier 1 profitability and slowing take rates. OEMs resort to manual-variable-intermittent wipers in sub-4-m vehicles until integrated MEMS pricing drops below USD 15. Suppliers that secure local glass-bonding partnerships can shave freight surcharges, but low-volume orders currently deter such CAPEX outlays.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Automatic Wiper Systems
- Rising Consumer Demand for Comfort & Convenience Features
- Shortage of Automotive-Grade Photodiodes & VCSELs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The automotive rain sensor market size for passenger cars captured 70.88% share in 2025, and is expected to lead at a robust 6.30% CAGR through 2031. Sedan programs maintain consistent attach rates across trim lines, yet hatchbacks remain price-gated to upper variants. Fleets of light commercial vans now specify automatic wiping to minimize driver distraction and insurance claims, though medium trucks lag because of retrofit complexities. Demand alignment shows that every 10-point uptick in SUV mix raises system-average BOM ceiling by USD 4, supporting margin retention for Tier 1s. Over the forecast period, SUVs' larger windshield area drives higher droplet-noise in capacitive arrays, sustaining OEM preference for optical architectures that maintain +-2 ml sensitivity accuracy in heavy downpours.
Passenger-car refresh cycles grant slower but steadier volume accrual compared with high-churn small commercial fleets. Fleet operators investigating telematics report 7% lower windshield repair claims once predictive wipe analytics are activated, strengthening business cases. Overall, SUV proliferation ensures the automotive rain sensor market remains skewed toward feature-rich packages, balancing the lower margins of high-volume hatchbacks.
Optical CCD/CMOS devices controlled 81.10% of 2025 revenue owing to proven signal-to-noise fidelity. With the top five optical controller ASICs already at silicon-revision B or later, cost curves flatten, giving MEMS entrants a price-to-performance opening. Capacitive / MEMS-based devices will clock an 8.25% CAGR as they sidestep glass-coupling tolerances, ideal for vehicles using advanced UV-blocking laminated windshields. Infrared-reflective hybrids capture niche programs needing anti-icing credibility below -25 °C, albeit at higher per-unit cost.
Strategy roadmaps show MEMS suppliers bundling ambient-light sensors and IR proximity in shared die space, trimming PCB footprint by 35%. Conversely, optical incumbents shield volumes by embedding AI-edge inference cores, enabling self-calibrating droplet recognition that sustains specification leadership. Coexistence rather than displacement defines the horizon: optical retains premium and severe-duty niches; MEMS drives democratization.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Hatchback
- Sedan
- SUVs and crossovers
- Commercial Vehicles
- Light Commercial Vehicle (LCV)
- Medium and Heavy Commercial Vehicle
- Passenger Cars
- By Technology
- Optical (CCD/CMOS)
- Infra-red Reflective
- Capacitive / MEMS-based
- By Sales Channel
- OEM-Installed
- Aftermarket Retrofit
- By Application
- Automatic Wiper Control
- Integrated Rain-Light-Humidity Sensing
- ADAS Sensor Fusion Modules
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Turkey
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe's 37.55% share reflects strict UNECE visibility norms and 2025 NCAP scoring that awards two safety points for rain-light-humidity fusion, cementing sensor fitment as an entitlement across B-segment hatchbacks upward. The continent's established premium mix also ensures high-margin optical arrays dominate. South America, led by Brazil's volume OEM hubs in Sao Paulo, is the fastest climber with a 9.85% CAGR. Consumer upgrades from entry to compact SUVs introduce room in the BOM for automated wiping, while federal incentives to localize electronic content spur sensor-housing molding ventures near Manaus.
Asia-Pacific delivers nuanced dynamics. China's New Car Evaluation Program will credit automated visibility management starting in 2027, anchoring stable shipments within a manufacturing base already scaling 25 million vehicles yearly. Hindrances lie in India and parts of ASEAN, where taxation on imported electronics inflates cost. Nonetheless, EV push grants rain sensors renewed relevance: Chinese-built sub-USD 15,000 micro-EVs that export to Thailand and Indonesia include basic capacitive sensors to ease right-hand-drive adaptation. Hence, Asia-Pacific remains both the largest growth reservoir and the most fragmented battlefield. North America's uptake is steady rather than spectacular, yet high average transaction prices allow complex sensor-fusion packages on mainstream pickups and SUVs. Over-the-air update culture seeds subscription models for predictive windshield maintenance, producing recurring revenues that temper hardware commoditization.
- HELLA GmbH & Co. KGaA
- Valeo SA
- DENSO Corporation
- ZF Friedrichshafen AG
- Robert Bosch GmbH
- STMicroelectronics N.V.
- Analog Devices Inc.
- ams-OSRAM AG
- onsemi
- Hamamatsu Photonics K.K.
- Sensata Technologies Inc.
- Melexis NV
- Texas Instruments Inc.
- Panasonic Holdings Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising ADAS penetration mandates multi-function environmental sensing (rain, light, fog)
- 4.2.2 Electrification & higher onboard voltage architectures accelerate adoption of solid-state optical rain sensors
- 4.2.3 Regulatory push for automatic wiper systems
- 4.2.4 Rising consumer demand for comfort & convenience features across mid-segment vehicles
- 4.2.5 Integration of windshield head-up-display (HUD) modules requires cleanliness sensing (under-reported)
- 4.2.6 Automotive over-the-air updates unlock new revenue via subscription-based wiper automation (under-reported)
- 4.3 Market Restraints
- 4.3.1 High price sensitivity in entry-level A/B-segment cars limits sensor attach-rates in India & ASEAN
- 4.3.2 Shortage of automotive-grade photodiodes & VCSELs
- 4.3.3 Windshield design heterogeneity complicates optical coupling & raises validation cost (under-reported)
- 4.3.4 Competition from camera-only ADAS stacks promising software-defined rain detection (under-reported)
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.1.1 Hatchback
- 5.1.1.2 Sedan
- 5.1.1.3 SUVs and crossovers
- 5.1.2 Commercial Vehicles
- 5.1.2.1 Light Commercial Vehicle (LCV)
- 5.1.2.2 Medium and Heavy Commercial Vehicle
- 5.1.1 Passenger Cars
- 5.2 By Technology
- 5.2.1 Optical (CCD/CMOS)
- 5.2.2 Infra-red Reflective
- 5.2.3 Capacitive / MEMS-based
- 5.3 By Sales Channel
- 5.3.1 OEM-Installed
- 5.3.2 Aftermarket Retrofit
- 5.4 By Application
- 5.4.1 Automatic Wiper Control
- 5.4.2 Integrated Rain-Light-Humidity Sensing
- 5.4.3 ADAS Sensor Fusion Modules
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Turkey
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 South Africa
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 HELLA GmbH & Co. KGaA
- 6.4.2 Valeo SA
- 6.4.3 DENSO Corporation
- 6.4.4 ZF Friedrichshafen AG
- 6.4.5 Robert Bosch GmbH
- 6.4.6 STMicroelectronics N.V.
- 6.4.7 Analog Devices Inc.
- 6.4.8 ams-OSRAM AG
- 6.4.9 onsemi
- 6.4.10 Hamamatsu Photonics K.K.
- 6.4.11 Sensata Technologies Inc.
- 6.4.12 Melexis NV
- 6.4.13 Texas Instruments Inc.
- 6.4.14 Panasonic Holdings Corp.
7 Market Opportunities & Future Outlook
- 7.1 Demand surge for combined rain-fog-light sensor modules to support L3 autonomy
- 7.2 Growth of subscription-based "feature-on-demand" wiper services post-2026
- 7.3 Localisation of sensor assembly in India, Brazil & Indonesia to bypass import duties
- 7.4 Development of hydrophobic nano-coated windshields reducing sensor calibration cycles