

|
시장보고서
상품코드
2121555
나노섬유 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Nanofiber - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 나노섬유 시장 규모는 2025년에 15억 8,000만 달러로 평가되었고, 2026년 19억 달러에서 2031년까지 47억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 20.07%를 기록할 전망입니다.
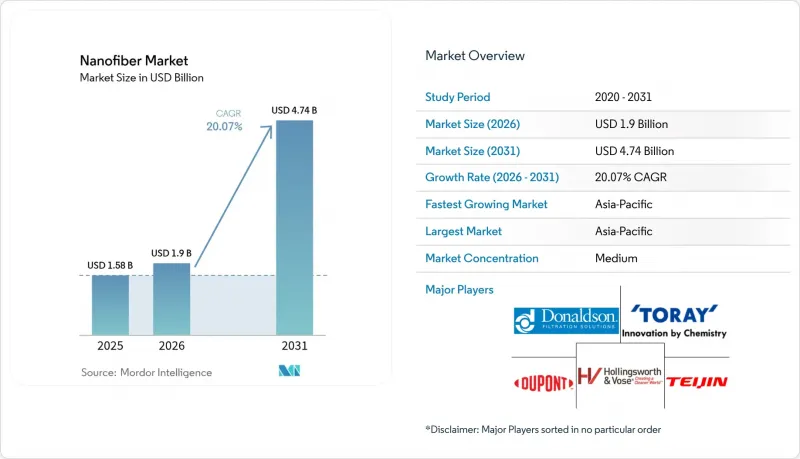
본 보고서는 제품 유형(고분자 나노파이버, 탄소 나노파이버 등), 용도(물 및 공기 여과, 의료 등),제조 기술(일렉트로스피닝(니들 방식), 니들리스 일렉트로스피닝 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 나노섬유 시장 동향 및 인사이트
의료 및 제약 업계 수요 증가
나노섬유를 기반으로 한 약물 전달 플랫폼은 현재 85% 이상의 약물 적재율과 최대 96시간에 걸친 서방형을 실현하여, 치료 순응도를 비약적으로 향상시키고 전신 독성을 저감시키고 있습니다. 세포외 기질과 유사한 구조는 뛰어난 세포 부착성을 뒷받침하여 치유 시간을 단축하고 흉터를 최소화하는 차세대 조직 스캐폴드를 가능하게 합니다. 첨단 상처 피복재를 도입한 병원에서는 환자 회전율 향상으로 인해 치료 비용 절감이 이루어지고 있는 것으로 나타나, 이는 조달 의욕을 높이고 있습니다. 정형외과 분야에서 나노섬유 스캐폴드의 규제 경로가 지속적으로 명확해지고 있어, 개발자가 제품을 시장에 출시하기까지의 위험이 줄어들고 있습니다. 이러한 의료 분야의 획기적인 발전이 맞물려 보험 환급 전망이 밝아지고 있으며, 고부가가치 의료 채널 전반에 걸쳐 지속적인 수요가 강화되고 있습니다.
EV 기가팩토리에서의 고표면적 배터리 세퍼레이터 수요
일렉트로스피닝 공법을 이용한 나노섬유 분리막은 현재 치수 변화 없이 150°C의 온도 변동을 견딜 수 있어, 전기차의 중요한 안전 기준을 충족하고 있습니다. 이온 전도성 향상으로 사이클 수명을 유지하면서 급속 충전 능력을 최대 40% 향상시켰으며, 이러한 장점 덕분에 아시아 및 미국의 기가팩토리에서의 조달 수요가 증가하고 있습니다. 자동화된 롤 투 롤(roll-to-roll) 생산 라인을 통해 연간 생산량은 300만 m²를 초과하며, 기존 폴리올레핀 필름과의 비용 격차가 줄어들고 있습니다. 주요 배터리 제조업체들의 설비 투자로 인해 수년에 걸친 공급 계약이 확정되어, 나노섬유 공급업체들은 예측 가능한 생산량 가시성을 확보하고 있습니다. 중국과 미국의 청정 모빌리티 지원 정책에 따라 새로운 배터리 화학 계열에서 분리막의 채택이 더욱 확대되고 있습니다.
PAN 원료 가격 변동
PAN은 탄소 나노섬유 전구체의 약 90%를 차지하며, 그 현물 가격은 연간 최대 20%까지 변동하기 때문에 하류 공급업체의 이익률 안정성을 저해하고 있습니다. 아크릴로니트릴 원료 부족에 따른 공급 차질은 재고 리스크를 심화시키고 있으며, 생산자들은 원자재 비용을 1kg당 9달러 미만으로 억제하면서 지속가능성 노력을 강화할 수 있는 석유 아스팔트나 리그닌 등의 대체 원료 도입을 모색하고 있습니다. 불순물 관리 및 기계적 성능의 편차로 인해 전환에는 여전히 오랜 기간이 소요되고 있어, PAN 가격 변동 위험에 노출되는 기간이 길어지고 있습니다. 구매자들은 지수 연동형 계약을 통해 헤지를 실시하고 있으나, 장기적인 가격 전망은 여전히 불투명하여 적극적인 생산 능력 확장을 억제하고 있습니다.
부문별 분석
폴리머 부문은 확립된 일렉트로스피닝 생산 라인과 포장, 여과, 의료기기 분야에 걸친 폭넓은 화학적 범용성에 힘입어 2025년 매출의 41.20%를 차지하고 있습니다. 탄수화물 유래 등급은 생산량은 적지만, 최종 사용자가 전 세계 순환 경제의 요구에 부응하는 생분해성 및 바이오 유래 대체재를 추구하고 있기 때문에 연평균 성장률(CAGR) 26.2%로 급속히 성장하고 있습니다. 셀룰로오스 나노섬유는 아라미드에 필적하는 인장 강도를 가지면서도 상온 조건에서 생분해되기 때문에 포장재 공급업체들은 일회용 용도로 이를 채택할 수밖에 없습니다. 키틴 나노섬유는 고유한 항균 특성으로 인해 상처 관리 제품 제조업체들의 관심을 끌고 있으며, 갑각류 폐기물의 유효 활용을 위한 투자를 촉진하고 있습니다. 탄소 나노섬유는 특수 에너지 및 전자 분야에서 널리 이용되고 있지만, 생산 규모와 비용 측면의 과제가 당분간 성장을 저해하고 있습니다.
화합물 기반 제품에 대한 모멘텀은 화석 유래 플라스틱 사용 감축을 목표로 하는 브랜드 소유주들의 노력에 힘입어 더욱 강화되고 있습니다. EU 일부 회원국에서 일회용 합성 섬유에 대한 법적 금지 조치도 이러한 수요를 뒷받침하고 있습니다. 폴리머와 세라믹 상을 혼합한 복합 나노섬유는 고온 여과 틈새 시장에서 중요한 역할을 하고 있습니다. 금속 및 금속 산화물 등급은 높은 전도성이나 광촉매 활성이 필수적인 촉매 및 센서 용도로 사용되고 있습니다. 세라믹 나노섬유는 항공우주 분야 및 용광로 내벽재용 단열재로서 수요를 유지하고 있습니다. 원자재 연구 개발이 임업 및 농업 폐기물 분야로 전환됨에 따라 비용 곡선은 수렴될 것으로 예상되며, 이는 나노섬유 시장 전체의 확장을 촉진할 것입니다.
지역별 분석
아시아태평양은 2025년 매출의 37.60%를 차지하고 있으며, 중국, 일본, 한국은 탄탄한 전자 부품 공급망과 정부 주도의 나노기술 추진 정책의 혜택을 받고 있습니다. 중국의 견고한 전기차(EV) 생산 기반은 나노섬유 분리막에 대한 현지 수요를 끌어올리고 있으며, 한편 엄격한 환경 규제로 인해 공기 여과 시스템 개조 시 나노섬유 분리막 도입이 가속화되고 있습니다. 지속 가능한 소재에 배정된 지역 경제 부양 자금은 리그닌 유래 나노섬유 제조 플랜트에 대한 투자 위험을 더욱 낮춰줍니다. 이러한 생태계가 해당 지역의 연평균 성장률(CAGR) 21.4%를 뒷받침하며, 아시아태평양이 계속해서 전 세계 생산량 성장의 견인차 역할을 할 것임을 확실히 하고 있습니다.
북미는 의료, 국방, 에너지 분야에 보조금을 배분하는 2025 회계연도 ‘국가 나노기술 이니셔티브’ 예산 22억 달러를 보유한 미국의 주도하에 전 세계 수익 창출에 중요한 역할을 하고 있습니다. 고부가가치 헬스케어 프로젝트가 수요의 대부분을 차지하고 있으며, 나노섬유를 활용한 재생의료용 임플란트의 임상시험은 FDA의 패스트트랙 지정을 획득하여 상용화가 가속화되고 있습니다. 국방 기관은 여과 기술 및 방호복의 연구 개발을 지원하며 국내 공급망을 강화하고 있습니다. 캐나다의 청정 기술에 대한 우대 조치와 자동차 산업 거점과의 근접성은 배터리 재료 분야에서의 국경을 초월한 협력을 촉진하고 있습니다. 독일과 프랑스의 엄격한 지속가능성 프레임워크에 힘입은 유럽은 생분해성 나노섬유 포장재 및 HVAC 솔루션 시장을 선도하고 있습니다. ‘호라이즌 유럽(Horizon Europe)’의 보조금은 규모 확대와 표준화를 가속화하는 산학 클러스터를 육성하고 있으며, 한편 REACH 준수 지침은 규제 측면에서의 확실성을 제공합니다. 성장률은 아시아태평양에 미치지 못하지만, 특정 일회용 플라스틱을 금지하는 EU 지침에 따라 외식 산업 및 퍼스널케어 제품 분야에서 대체재에 대한 수요가 발생하고 있습니다. 남미, 중동 및 아프리카에서는 식수 부족 해소 및 농업 효율 향상을 위한 프로그램이 탄력을 받고 있으며, 해수 담수화 및 방출 조절 비료에 대한 나노섬유 막의 조기 도입이 수익을 견인하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the nanofiber market size was valued at USD 1.58 billion in 2025 and estimated to grow from USD 1.9 billion in 2026 to reach USD 4.74 billion by 2031, at a CAGR of 20.07% during the forecast period (2026-2031).
This report is Segmented by Product Type (Polymeric Nanofiber, Carbon Nanofiber, and More), Application (Water and Air Filtration, Medical, and More), Manufacturing Technology (Electrospinning (Needle-Based), Needle-Less Electrospinning, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Nanofiber Market Trends and Insights
Increasing Demand from Medical and Pharmaceutical Industries
Nanofiber-based drug delivery platforms now achieve 85%-plus drug loading and sustained release for up to 96 hours, sharply improving therapeutic adherence and lowering systemic toxicity. Their extracellular-matrix-like architecture supports superior cell attachment, enabling next-generation tissue scaffolds that cut healing time and minimize scarring. Hospitals adopting advanced wound dressings cite patient-turnover gains that translate to reduced care costs, strengthening procurement appetite. Regulatory pathways for nanofiber scaffolds in orthopedics continue to clarify, lowering time-to-market risk for developers. Collectively, these medical breakthroughs elevate reimbursement prospects and reinforce recurring demand across high-value healthcare channels.
Demand for High-Surface-Area Battery Separators in EV Gigafactories
Electrospun nanofiber separators now withstand 150 °C thermal excursions without dimensional loss, addressing critical EV safety standards. Enhancements in ion conductivity are extending fast-charge capability by up to 40% while preserving cycle life, a gain attracting procurement from Asian and US gigafactories. Automated roll-to-roll lines scale output beyond 3 million m2 annually, narrowing cost gaps with conventional polyolefin films. Capital deployment by major cell producers is locking in multiyear supply contracts, providing predictable volume visibility for nanofiber vendors. National clean-mobility incentives in China and the United States further amplify separator adoption in new cell chemistries.
Volatile PAN Feedstock Prices
PAN constitutes about 90% of carbon nanofiber precursors, and its spot price fluctuates by up to 20% annually, eroding margin stability for downstream suppliers. Supply disruptions linked to acrylonitrile feed shortages intensify inventory risk, prompting producers to pursue petroleum-asphaltene or lignin alternatives that can cut raw-material cost below USD 9 per kg while raising sustainability credentials. Transition timeframes remain lengthy due to impurity management and variable mechanical performance, prolonging exposure to PAN volatility. Buyers hedge through index-linked contracts, but long-term pricing visibility is still limited, dampening aggressive capacity expansion.
Other drivers and restraints analyzed in the detailed report include:
- Demand for High-Efficiency Filtration Materials
- Growth in the Automotive Industry
- Difficulty in Shifting Carbon Nanofibers from Lab to Plant Scale
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The polymeric category anchors 41.20% of 2025 revenue, driven by well-established electrospinning lines and broad chemical versatility across packaging, filtration and biomedical devices. Carbohydrate-based grades, while smaller in volume, accelerate at a 26.2% CAGR as end-users pursue biodegradable, bio-sourced alternatives aligned with global circular-economy mandates. Cellulose nanofibers rival aramid tensile strength yet biodegrade under ambient conditions, compelling packaging suppliers to adopt them in single-use applications. Chitin nanofibers attract wound-care producers due to inherent antimicrobial traits, spurring investment in shellfish-waste valorization. Carbon nanofibers find significant use in specialty energy and electronics applications; however, production scale and cost challenges are restraining immediate growth.
Momentum for carbohydrate-based products is amplified by brand-owner commitments to cut fossil plastic use. Legislative bans on single-use synthetic fibers in several EU states compound this pull. Composite nanofibers, which blend polymer and ceramic phases, play a significant role in high-temperature filtration niches. Metal and metal-oxide grades serve catalytic and sensing applications where elevated conductivity or photocatalytic activity is critical. Ceramic nanofibers retain demand for thermal insulation in aerospace and furnace linings. As raw-material R&D migrates toward forestry and agricultural waste streams, cost curves are expected to converge, bolstering the broader nanofiber market.
Complete Report Scope:
- By Product Type
- Polymeric Nanofiber
- Carbon Nanofiber
- Composite Nanofiber
- Metal and Metal Oxide Nanofiber
- Ceramic Nanofiber
- Carbohydrate-based Nanofiber
- By Application
- Water and Air Filtration
- Medical
- Energy Storage
- Automotive and Transportation
- Electronics
- Textiles
- Other Applications
- By Manufacturing Technology
- Electrospinning (Needle-Based)
- Needle-less Electrospinning
- Solution Blow Spinning
- ForceSpinning/Rotary Jet Spinning
- Melt Blowing
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commands 37.60% of 2025 revenue, with China, Japan and South Korea benefitting from deep electronic supply chains and government-backed nanotech initiatives. Robust EV production bases in China elevate local demand for nanofiber separators, while strict environmental guidelines accelerate uptake in air-filtration retrofits. Regional stimulus funds earmarked for sustainable materials further de-risk investment in lignin-derived nanofiber plants. This ecosystem underpins a 21.4% regional CAGR, ensuring Asia-Pacific continues to anchor global volume growth.
North America, driven by the U.S. with its USD 2.2 billion FY-25 National Nanotechnology Initiative budget, which allocates grants to medical, defense, and energy sectors, plays a significant role in global revenue generation. High-value healthcare projects dominate demand; clinical trials for nanofiber-based regenerative implants secure FDA fast-track status, accelerating commercialization. Defense agencies sponsor filtration and protective-wear R&D, fortifying domestic supply chains. Canada's clean-technology incentives and proximity to automotive hubs kindle cross-border collaboration in battery materials. Europe, driven by Germany and France's stringent sustainability frameworks, leads in the market for biodegradable nanofiber packaging and HVAC solutions. Horizon Europe grants foster university-industry clusters that fast-track scale-up and standardization, while REACH compliance guidelines supply regulatory certainty. Although growth rates trail Asia-Pacific, EU directives banning select single-use plastics are opening replacement opportunities in food-service and personal-care products. In South America, the Middle East, and Africa, where programs addressing potable-water scarcity and enhancing agricultural efficiency are gaining traction, revenue is driven by the early adoption of nanofiber membranes in desalination and controlled-release fertilizers.
- Applied Sciences Inc.
- Argonide Corporation
- Asahi Kasei Corporation
- Chuetsu Pulp & Paper Co. Ltd.
- Donaldson Company Inc.
- DuPont
- Esfil Tehno AS
- eSpin Technologies Inc.
- FibeRio Technology Corp.
- Hollingsworth & Vose
- IREMA-Filter GmbH
- Japan Vilene Company Ltd.
- NanoLayr Ltd
- Nanoval GmbH & Co. KG
- NIPPON PAPER INDUSTRIES CO., LTD.
- Pardam SRO
- Rengo Co., Ltd.
- Sappi Ltd.
- SNC Fiber
- Spur AS
- Teijin Limited
- Toray Industries Inc.
- US Global Nanospace Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand from the Medical and Pharmaceutical Industries
- 4.2.2 Demand for High-Surface-Area Battery Separators in EV Gigafactories
- 4.2.3 Demand for High-Efficiency Filtration Materials
- 4.2.4 Growth in the Automotive Industry
- 4.2.5 Expansion in the Textile Industry
- 4.3 Market Restraints
- 4.3.1 Volatile PAN Feedstock Prices
- 4.3.2 Difficulty in Shift of Carbon Nanofibers from Lab Scale to Plant Scale due to Small Size and Complexity
- 4.3.3 Health and Safety Concerns
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Technology Snapshot
- 4.7 Patent Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polymeric Nanofiber
- 5.1.2 Carbon Nanofiber
- 5.1.3 Composite Nanofiber
- 5.1.4 Metal and Metal Oxide Nanofiber
- 5.1.5 Ceramic Nanofiber
- 5.1.6 Carbohydrate-based Nanofiber
- 5.2 By Application
- 5.2.1 Water and Air Filtration
- 5.2.2 Medical
- 5.2.3 Energy Storage
- 5.2.4 Automotive and Transportation
- 5.2.5 Electronics
- 5.2.6 Textiles
- 5.2.7 Other Applications
- 5.3 By Manufacturing Technology
- 5.3.1 Electrospinning (Needle-Based)
- 5.3.2 Needle-less Electrospinning
- 5.3.3 Solution Blow Spinning
- 5.3.4 ForceSpinning/Rotary Jet Spinning
- 5.3.5 Melt Blowing
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-Level Overview, Market-Level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Applied Sciences Inc.
- 6.4.2 Argonide Corporation
- 6.4.3 Asahi Kasei Corporation
- 6.4.4 Chuetsu Pulp & Paper Co. Ltd.
- 6.4.5 Donaldson Company Inc.
- 6.4.6 DuPont
- 6.4.7 Esfil Tehno AS
- 6.4.8 eSpin Technologies Inc.
- 6.4.9 FibeRio Technology Corp.
- 6.4.10 Hollingsworth & Vose
- 6.4.11 IREMA-Filter GmbH
- 6.4.12 Japan Vilene Company Ltd.
- 6.4.13 NanoLayr Ltd
- 6.4.14 Nanoval GmbH & Co. KG
- 6.4.15 NIPPON PAPER INDUSTRIES CO., LTD.
- 6.4.16 Pardam SRO
- 6.4.17 Rengo Co., Ltd.
- 6.4.18 Sappi Ltd.
- 6.4.19 SNC Fiber
- 6.4.20 Spur AS
- 6.4.21 Teijin Limited
- 6.4.22 Toray Industries Inc.
- 6.4.23 US Global Nanospace Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Increasing R&D and High-potential Market for Cellulosic Nanofibers


